

Root, Inc. ROOT shares have fallen 12% in the past month as slower premium growth and higher loss costs temper otherwise resilient profitability. Gross written premium declined in the second quarter, while the accident-period loss ratio moved higher.
The pullback leaves investors weighing Root's return-focused underwriting against a tougher direct auto market. Near-term performance will depend on preserving margins while newer distribution channels and the fourth-quarter pricing-model launch shape the 2027 outlook.
Why ROOT's Premium Growth Has Lost Momentum
Direct auto competition intensified in the second quarter of 2026 as rivals increased marketing and lowered prices. Root responded by cutting acquisition spending that did not meet its return targets. Gross written premium fell 1.9% year over year to $339.7 million, and management expects year-end 2026 policies in force to be relatively flat if current competition persists.
ROOT Preserves Profitability Despite Slower Growth
Root's slower premium growth has not yet undermined earnings. Second-quarter net income increased 15.5% to $25.4 million, while adjusted EBITDA rose 16.5% to $43.8 million. The net combined ratio improved 310 basis points to 92.1%, helped by a lower expense ratio.
That result reflects management's decision to favor target returns over volume when acquisition economics weaken. For the first half of 2026, adjusted EBITDA reached $100.6 million versus $69.5 million a year earlier, and the net combined ratio improved to 91.7% from 95.4%.
Rising Loss Costs Could Keep Pressure on ROOT
Claims trends are the clearest near-term margin risk. The gross accident-period loss ratio rose to 61.6% in the second quarter from 57.4% a year earlier as vehicle repair costs, medical inflation and channel mix pressured loss economics. Accident-period severity per claim increased at a mid-single-digit rate year over year.
Management also expects the normal seasonal rise in loss ratios during the second half of 2026. Potential low-single-digit rate decreases could reduce pricing cushion before the next predictive model has a larger effect, especially if claims severity remains elevated.
ROOT's New Pricing Model Could Shift the 2027 Outlook
Root plans to launch its next predictive pricing model in the fourth quarter of 2026, followed by a state-by-state rollout with a more material impact expected in 2027. The prior model increased customer lifetime values by more than 20%, making improved risk segmentation an important part of the longer-term growth case.
Carvana provides another route to policy growth outside direct acquisition. Carvana said in April that its embedded insurance program with Root had surpassed 200,000 policies sold. Root later extended the exclusive partnership through at least August 2028, adding multi-year visibility to that distribution channel.
ROOT's Mixed Near-Term Signal Meets Strong Style Scores
The near-term picture remains mixed. Root is protecting underwriting returns and expanding distribution, but direct-channel competition, higher loss costs and planned second-half investment could limit growth and margin expansion before the pricing model has a larger effect in 2027.
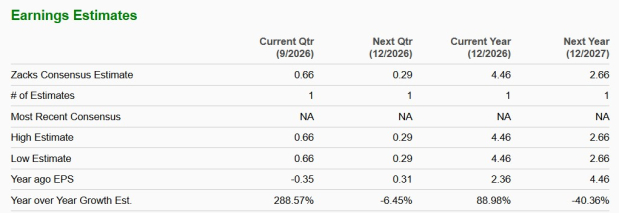
The Zacks Consensus Estimate for 2026 EPS represents an increase while that for 2027 represents a year-over-year decrease.
Image Source: Zacks Investment Research
ROOT currently carries a Zacks Rank #3 (Hold). It also has a Value Score of A, Growth Score of A, Momentum Score of A and VGM Score of A.
Those Style Scores indicate favorable characteristics across the major investing styles, but they are designed to complement the Zacks Rank rather than serve as standalone signals.
Stocks to Consider
Mercury General MCY, Heritage Insurance HRTG and American Integrity Insurance Group, Inc. AII are some top-ranked stocks from the Zacks Property and Casualty Insurance industry. All three stocks currently sport a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for 2026 and 2027 earnings of Mercury General, Heritage Insurance and American Integrity witnessed northbound movement in the last 30 days. In terms of share price movement, Mercury General, Heritage Insurance and American Integrity lost 6.8%, 1.1% and 1.6%, respectively, in the past month.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Root, Inc. (ROOT): Free Stock Analysis Report
Mercury General Corporation (MCY): Free Stock Analysis Report
Heritage Insurance Holdings, Inc. (HRTG): Free Stock Analysis Report
American Integrity Insurance Group, Inc. (AII): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).