

Walmart Inc. WMT continues to command a premium valuation, reflecting investors' confidence in its resilient business model, expanding digital capabilities and improving profitability. However, the stock's elevated valuation raises questions about whether its growth prospects justify the premium.
WMT is currently trading at a forward 12-month price-to-earnings (P/E) multiple of 36.32, exceeding the industry average of 32.73 and its five-year median of 25.20. This premium reflects investors' expectations of sustained earnings growth and successful execution of Walmart's omnichannel strategy. However, the elevated valuation also leaves limited room for earnings disappointments or operational setbacks.
Image Source: Zacks Investment Research
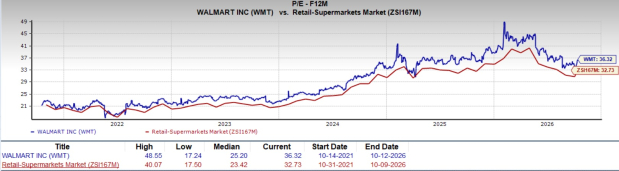
Walmart also trades at a substantially higher valuation than Target Corporation TGT and Dollar General Corporation DG, which currently command forward P/E multiples of 15.78 and 15.32, respectively. Meanwhile, Costco Wholesale Corporation COST commands an even richer valuation at 41.55, highlighting the varying premiums investors are willing to pay for leading retailers.
What's Driving Walmart's Growth Momentum?
Walmart's growth momentum is supported by its ability to combine everyday low prices with digital convenience, operational efficiency and expanding higher-margin businesses. Its extensive store network, competitive pricing and broad merchandise assortment continue to attract customers across income groups. The company's emphasis on affordability remains particularly relevant as consumers prioritize value amid ongoing economic pressures. Continued market share gains, especially in grocery and essential categories, highlight the resilience of its business model.
E-commerce remains a key growth catalyst, supported by faster fulfillment, marketplace expansion and increasing digital adoption. Walmart is leveraging its physical footprint to integrate stores with online operations, enabling convenient pickup and faster deliveries while improving fulfillment efficiency. Global e-commerce sales increased 23% in second-quarter fiscal 2027, underscoring sustained demand for its omnichannel offerings. Expanding delivery capabilities are also strengthening customer engagement and encouraging repeat purchases.
Walmart's growing ecosystem of higher-margin businesses, including advertising, marketplace services and membership programs, is another important strength. Walmart Connect, its third-party marketplace, and Walmart+ are creating additional revenue opportunities beyond traditional retail sales. These businesses are improving profitability, diversifying revenue streams and reinforcing customer loyalty.
Continued investments in automation, artificial intelligence and supply-chain modernization are enhancing productivity and inventory management. Walmart International and Sam's Club provide additional growth opportunities through digital expansion, membership gains and improving market penetration. Together, these initiatives support Walmart's competitive positioning and long-term earnings potential.
How Has WMT Stock Performed Against Its Peers?
Shares of Walmart have gained 5.5% over the past year, outperforming the broader industry's 2.8% growth and the Zacks Retail – Wholesale sector's modest rise of 0.2%.
Image Source: Zacks Investment Research
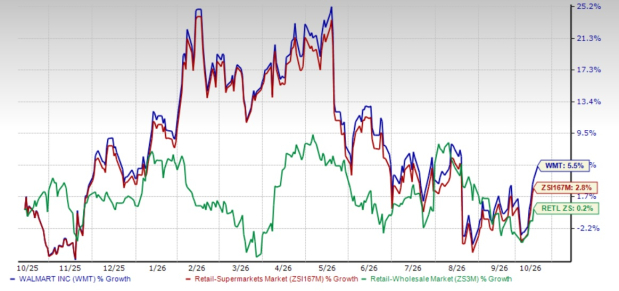
However, the company has underperformed several prominent retail peers like Target and Dollar General while outpacing Costco. Over the past year, TGT and DG have delivered gains of 72.7% and 22%, respectively. Meanwhile, COST has advanced 1.4%, trailing WMT. The mixed performance suggests that although Walmart's fundamentals remain solid, its premium valuation has not translated into market-leading stock appreciation. Sustained earnings momentum may be necessary to justify further upside.
Walmart’s Near-Term Challenges
Despite its long-term strengths, Walmart faces several near-term challenges that could pressure profitability. Elevated fuel costs, aggressive pricing investments and rising operating expenses remain key concerns. Management expects more than $2 billion in incremental fuel-related costs in fiscal 2027, creating additional pressure on distribution and fulfillment expenses.
Walmart's focus on affordability, while supporting market share gains, could weigh on near-term margins. The company implemented more than 11,000 price rollbacks during the second quarter. Tariff-related refunds significantly benefited quarterly profitability, raising questions about the sustainability of the reported growth rate. Management expects third-quarter adjusted operating income growth of 2-4% in constant currency, reflecting continued price investments.
Higher depreciation, self-insurance costs and employee healthcare expenses also contributed to operating expense deleverage. Meanwhile, Walmart U.S. comparable sales growth moderated to 2.6%, partly due to pharmacy-related deflation associated with maximum fair price regulations. These pressures, combined with a premium valuation, could limit near-term stock upside.
What Do Earnings Estimates Indicate for WMT?
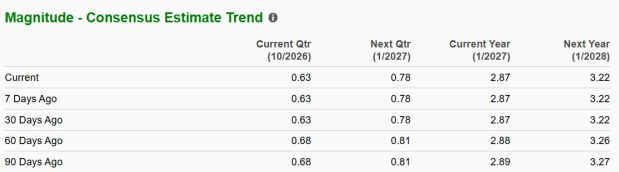
The Zacks Consensus Estimate for Walmart's current fiscal-year earnings per share has remained unchanged at $2.87 over the past 30 days, implying year-over-year growth of 8.7%. Similarly, the consensus estimate for the next fiscal year has held steady at $3.22, suggesting growth of nearly 12%.
Image Source: Zacks Investment Research
Should Investors Buy, Hold or Sell Walmart Stock Now?
Walmart's strong market position, expanding digital ecosystem and growing higher-margin businesses provide a solid foundation for sustained growth. Its emphasis on affordability, convenience and operational efficiency continues to strengthen its competitive advantage. However, the elevated valuation, mixed stock performance and near-term cost pressures suggest that much of the optimism is already priced in. While Walmart remains fundamentally attractive, its current risk-reward profile favors a cautious approach. Existing shareholders may consider retaining their positions, while prospective investors could await a more favorable entry point.
WMT currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Walmart Inc. (WMT): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
Costco Wholesale Corporation (COST): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).