

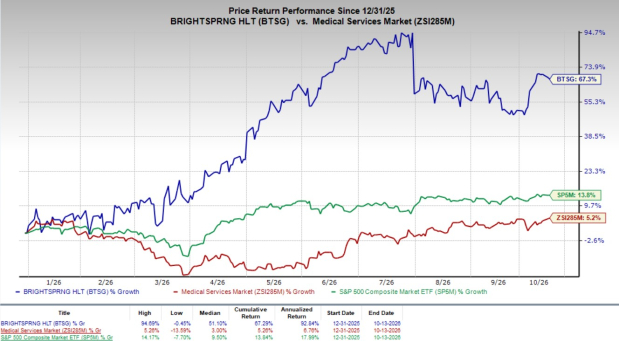
BrightSpring Health Services, Inc.’s BTSG shares have rallied 67.3% year to date, showing impressive momentum. It has significantly outperformed the industry’s 5.2% growth and the S&P 500’s 13.8% gain.
BrightSpring's performance has been supported by broad-based demand across its Pharmacy Solutions and Provider Services segments, improving profitability and progress in integrating acquired home health operations. With healthy fundamentals and strong growth opportunities, this Zacks Rank #3 (Hold) company is likely to maintain the wealth gain for its existing investors. However, adding this stock to one’s portfolio is not advised right now.
Headquartered in Louisville, KY, BrightSpring Health Services is a national home and community-based healthcare services platform serving medically complex patients across all 50 states. It operates through Pharmacy Solutions, which provides medication dispensing, specialty pharmacy and infusion services, and Provider Services, which delivers home health, hospice, rehabilitation, primary care and personal care services to seniors and specialty populations.
What Is Fueling BTSG's Price Rally?
The rally in BrightSpring's shares has been supported by strong execution across its core businesses, particularly Specialty and Infusion. In the first half of 2026, revenues in the segment increased 32.7% year over year to $5.51 billion. Script growth was approximately 30% in the first quarter and 31% in the second quarter. BrightSpring launched 12 LDDs in the first half of 2026, including four exclusive partnerships and eight ultra-narrow arrangements, taking its portfolio to 155. Acute infusion volume grew more than 20% year over year in the second quarter of 2026, and the company has identified another 12-15 states for potential expansion over the next five years.
Provider Services is another important driver. Segment revenues increased 29.1% year over year to $908.4 million in the first half of 2026, led by Home Health Care growth of 49.7%. Higher census, de novo expansion and contributions from acquired Amedisys and LHC branches supported the increase. Nearly 95% of home health branches were rated four stars or above, while timely initiation of care was 99%. For the acquired Amedisys and LHC branches, management reported that integration progressed ahead of initial expectations and raised its anticipated full-year adjusted EBITDA contribution from these assets to approximately $35 million.
BrightSpring is deploying AI and automation across hiring, onboarding, intake, documentation, medication reviews and patient care planning. These initiatives helped lift adjusted EBITDA 44.5% year over year in the first half of 2026, while EBITDA margin expanded by 73 basis points to 5.3%. Management expects additional benefits from technology and process improvements later in 2026 and in early 2027.
BrightSpring’s strategic portfolio changes have improved its financial flexibility. In March 2026, the company completed the sale of its Community Living business to Sevita for $835 million in cash consideration. It used part of the proceeds to repay $300 million of term-loan borrowings and refinance the remaining debt at a lower spread. Leverage declined to 2.15x as of June 30, 2026, compared with 2.99x as of Dec. 31, 2025. Management expects approximately $600 million in operating cash flow for 2026 and intends to pursue tuck-in acquisitions and adjacent growth opportunities at disciplined valuations. The divestiture allowed BrightSpring to concentrate on its pharmacy and provider businesses, while lower leverage created flexibility to invest in expansion.
BrightSpring's strong first-half execution prompted management to raise its full-year 2026 outlook twice. The company expects revenues of $15.1-$15.425 billion and adjusted EBITDA of $820-$845 million. The rise in the outlook boosted investor confidence in BrightSpring’s earnings potential, supporting its share-price rally.
Image Source: Zacks Investment Research
Risks and Challenges
Reimbursement and pricing changes remain the clearest pressure point. Home and Community Pharmacy revenues declined 8.6% year over year in the first half of 2026, reflecting the impact from the Inflation Reduction Act (IRA) and the company's exit from certain uneconomic customers. BrightSpring expects the full-year 2026 IRA impact on this business to total approximately $200 million.
Execution risk also bears watching. The acquired Amedisys and LHC branches are expected to contribute about $35 million of adjusted EBITDA in 2026, but realizing the full benefit depends on admissions, clinician retention, technology conversion and operating standardization. At the same time, BTSG is funding de novo growth, infusion expansion, automation and artificial intelligence initiatives, which can lift costs before productivity benefits are fully realized.
Taking a Look at BTSG’s Estimates
The Zacks Consensus Estimate projects BTSG’s earnings per share (EPS) to grow 82% year over year to $1.82 in 2026 and a further 28.4% to $2.34 in 2027. In the past 60 days, the consensus mark for the company's 2026 EPS has remained stable at $1.82.
Revenues for 2026 are projected to increase 18.8% to $15.34 billion and another 12.7% to $17.28 billion in 2027.
Key Picks
Some better-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2 (Buy), reported a second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. MMSI’s earnings surpassed estimates in the trailing four quarters, the average surprise being 14.1%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BrightSpring Health Services, Inc. (BTSG): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).