

Seagate Technology Holdings plc STX is strengthening its profitability outlook through the growing adoption of its heat-assisted magnetic recording (HAMR)-based Mozaic platform. The company's second-generation Mozaic 4 technology, supporting storage capacities of up to 44 terabytes (TB) per drive, is emerging as a key contributor to margin expansion. By increasing storage density while maintaining relatively stable drive production volumes, Seagate is positioned to improve manufacturing efficiency, lower costs per terabyte and capture greater value from its high-capacity storage portfolio.
The Mozaic 4 platform is gaining traction among major cloud service providers. Seagate is currently ramping production with the world's two largest cloud providers, while additional customer qualifications remain underway. The company expects Mozaic 4 to account for 50% of its HAMR-based exabyte shipments by the end of calendar 2026. Management highlighted that Mozaic 4 shipments increased significantly during the June quarter after initial deliveries began in March. The platform contributed meaningfully to its financial performance and is expected to provide further benefits in the September quarter.
Seagate's improving product mix is already supporting substantial profitability gains. In the fourth quarter of fiscal 2026, non-GAAP gross margin reached 52.7%, expanding 570 basis points sequentially. The improvement reflected favorable pricing, increasing shipments of high-capacity nearline drives and disciplined operational execution. Management emphasized that the transition from 3TB to 4TB per disk provides another opportunity to strengthen profitability through higher areal density and improved cost efficiency.
Strong demand from cloud customers, supported by expanding artificial intelligence (AI) workloads and data retention requirements, further reinforces this opportunity. Seagate's value-based pricing strategy and long-term customer commitments provide additional visibility into revenue and margin growth. Management expects sequential gross margin improvements throughout fiscal 2027, supported by continued Mozaic adoption and favorable supply-demand conditions.
However, manufacturing complexity, customer qualification timelines and temporary inefficiencies during technology transitions could moderate near-term gains. Despite these challenges, improving production yields and a richer mix of higher-capacity drives should support further profitability expansion. Overall, the continued rollout of 44TB Mozaic 4 drives strengthens Seagate's prospects for sustained gross margin improvement in fiscal 2027.
Taking a Look at STX’s Competitors
Western Digital WDC is well-positioned to benefit from rising demand for high-capacity storage driven by AI, cloud and data-intensive workloads. Strong cloud demand, favorable pricing and long-term customer agreements support revenue visibility. Its high-capacity ePMR and UltraSMR drives, along with upcoming HAMR technology, strengthen its position among hyperscale customers. A richer product mix, lower cost per terabyte and operating leverage are supporting margin expansion and cash generation. Western Digital issued encouraging first-quarter fiscal 2027 guidance, projecting non-GAAP revenues of $4.1 billion at the midpoint, plus or minus $100 million, representing 45% year-over-year growth.
NetApp NTAP is benefiting from rising enterprise spending on AI-ready storage, supported by demand for all-flash, Public Cloud and Keystone solutions. Its unified platform and acquisition initiatives strengthen data modernization, AI and migration capabilities. Raised fiscal 2027 guidance signals growth and operating leverage. For the fiscal second quarter, NetApp expects revenues of $2.03-$2.18 billion, non-GAAP gross margin of 67-68%, operating margin of 30.9-31.9% and earnings of $2.54-$2.64 per share. For fiscal 2027, revenues are projected at $7.98-$8.23 billion, with earnings of $9.73-$10.03 per share, reflecting continued growth momentum.
STX Price Performance, Valuation and Estimates
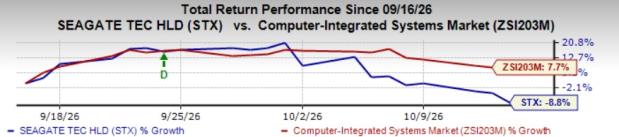
In the past month, STX’s shares have lost 8.8% against the Zacks Computer Integrated Systems industry growth of 7.7%.
Image Source: Zacks Investment Research
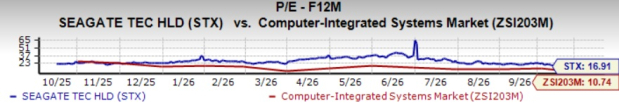
STX’s shares are trading at a forward price-to-earnings multiple of 16.91X, higher than the industry’s 10.74X.
Image Source: Zacks Investment Research
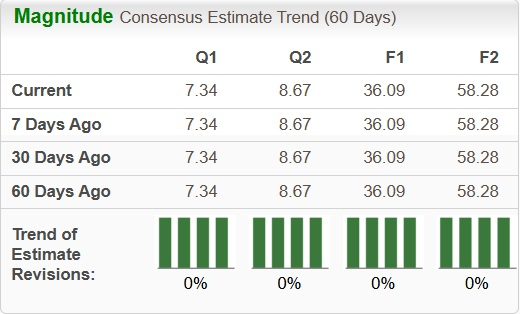
The Zacks Consensus Estimate for STX’s earnings for fiscal 2027 has been unchanged over the past 60 days.
Image Source: Zacks Investment Research
Currently, Seagate carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Western Digital Corporation (WDC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).