

Costco Wholesale Corporation COST pairs durable membership economics with steady sales growth and expanding digital reach. Fourth-quarter fiscal 2026 revenues reached $95.72 billion, while earnings came in at $6.60 per share, excluding a 15-cent nonrecurring benefit related to tariff refunds.
The growth case remains attractive, but the stock already reflects much of that quality. Investors must weigh Costco’s operating consistency against a forward earnings multiple that sits well above its industry and the broader market.
Costco’s Growth Engine Remains Strong
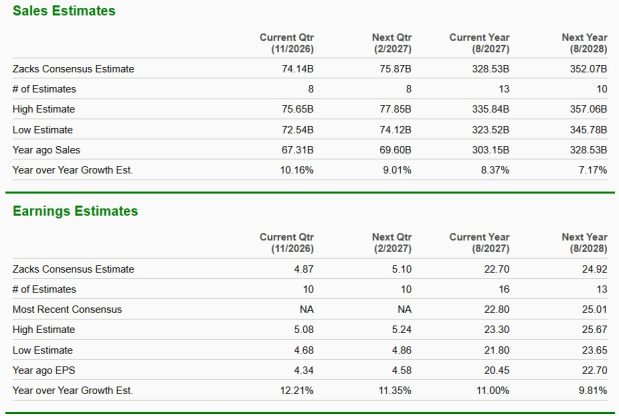
The Zacks Consensus Estimate calls for fiscal 2027 revenues of $328.53 billion, up 8.4% from fiscal 2026. Earnings are projected to rise 11% to $22.70 per share, extending Costco’s multiyear earnings compounding.
Fourth-quarter comparable sales increased 9.4%, or 6.7% after excluding gasoline-price and foreign-exchange effects. Shopping frequency rose 3.3%, supporting the view that growth is being driven by continued member engagement rather than price alone.
Image Source: Zacks Investment Research
COST’s Membership Economics Add Durability
Paid memberships increased 3.8% to 84.1 million in fiscal 2026, while Executive memberships climbed 9.4% to 42.3 million. Executive members accounted for 75.2% of worldwide sales, giving Costco a large base of higher-spending customers.
Renewal rates reached 92.3% in the United States and Canada and 89.8% worldwide. Membership fee income also grew 7.3% in the fourth quarter, reinforcing the recurring-revenue foundation of the warehouse model.
Costco’s Digital Gains Broaden the Opportunity
Digitally enabled sales exceeded $33 billion in fiscal 2026 and increased more than 20%. Fourth-quarter digitally enabled comparable sales rose 19.5%, while website and app traffic advanced 30% as Costco expanded delivery partnerships and personalization efforts.
The competitive benchmark remains demanding. Walmart Inc. WMT reported 23% global e-commerce growth in its fiscal 2027 second quarter, while Target Corporation TGT posted 8.7% digital comparable-sales growth in second-quarter fiscal 2026. Costco’s digital momentum therefore adds another growth channel without replacing its warehouse-led model.
COST’s Premium Valuation Raises the Hurdle
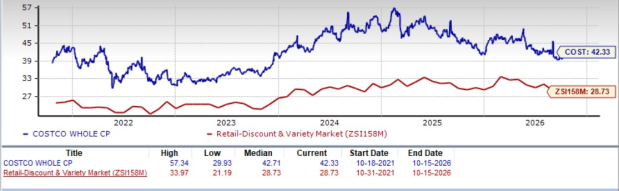
COST trades at 42.3X forward 12-month earnings, compared with 28.7X for the Zacks sub-industry and 19.6X for the S&P 500. The stock’s five-year median multiple is 42.7X, indicating that investors have long assigned Costco a premium valuation.
That premium still reduces the margin for error. Slower earnings growth, softer comparable sales or a reassessment of premium retail valuations could pressure the shares even if the underlying business remains healthy.
Image Source: Zacks Investment Research
Costco Faces Margin and Tariff Pressure
Fourth-quarter gross margin fell 11 basis points to 11.02%. Although gross margin improved 20 basis points excluding gasoline inflation, a $152 million LIFO charge and higher costs in electronics, fuel-related products and other commodities weighed on reported profitability.
Selling, general and administrative expenses improved 27 basis points as a percentage of sales, but only two basis points excluding gasoline inflation. Higher labor, health-care and liability costs, merchandise inflation and tariff uncertainty could limit operating leverage if sales growth moderates.
COST’s Signals Favor Quality Over Value
Costco’s growth profile remains attractive, but its valuation sets a high bar for execution. The current setup supports a measured stance rather than treating operating strength alone as sufficient reason to chase the stock.
COST carries a Zacks Rank #3 (Hold). Its Growth Score of A and VGM Score of B support the quality of its growth characteristics, while a Momentum Score of C is neutral and a Value Score of D underscores the valuation concern. For now, the combination points to patience unless earnings growth or valuation becomes more favorable. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Costco Wholesale Corporation (COST): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Walmart Inc. (WMT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).