

ManpowerGroup MAN reported mixed third-quarter 2026 results, with adjusted earnings meeting the Zacks Consensus Estimate and revenues missing expectations.
Although earnings matched estimates, the top-line miss disappointed investors, triggering a 20% dip in MAN shares after the results were released on Oct. 15.
MAN's adjusted earnings of $1.01 per share were in line with the consensus estimate and increased 22% year over year. Revenues of $4.84 billion lagged the consensus estimate of $4.91 billion by 1.4% but increased 4% year over year (5% in constant currency).
Growth was supported by improving labor demand, with Manpower brand revenues increasing 7% organically in constant currency.
ManpowerGroup Inc. Price, Consensus and EPS Surprise
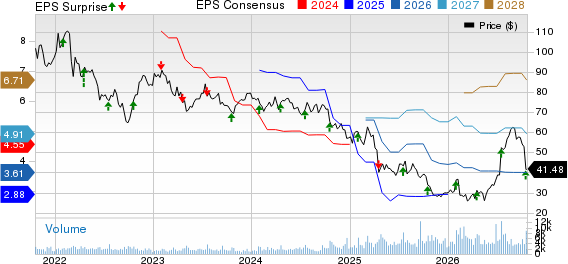
ManpowerGroup Inc. price-consensus-eps-surprise-chart | ManpowerGroup Inc. Quote
MAN Benefits From Improving Regional Demand
Revenues from the Americas increased 13% year over year to $1.2 billion, reflecting continued momentum in the United States and other regional markets. On a constant-currency basis, revenues increased 12%, while organic constant-currency revenues advanced 14%.
The United States registered revenue growth of 6% on both reported and constant-currency bases, with organic constant-currency growth reaching 9%. Canada posted 2% reported revenue growth, while Other Americas revenues increased 33%, reflecting broader regional strength.
Southern Europe, accounting for 46% of consolidated revenues, generated $2.2 billion, up 1% year over year and 2% in constant currency. France reported a 3% revenue decline, partially offset by growth of 4% in Italy and 7% in Spain.
ManpowerGroup Sees Growth Across European Markets
Northern Europe revenues rose 5% year over year to $861 million, increasing 6% in constant currency. Germany delivered strong revenue growth of 20%, while the United Kingdom registered a 7% increase.
However, revenues declined 4% in both the Netherlands and Belgium. The Nordics posted modest reported growth of 2%, with revenues remaining flat in constant currency.
Asia-Pacific Middle East revenues decreased 1% year over year to $515 million but increased 4% in constant currency. Japan and India each recorded a 6% decline in reported revenues, primarily reflecting currency movements, while constant-currency revenues increased 1% and 3%, respectively.
MAN Shows Improving Brand Momentum
The Manpower brand continued to drive growth, with reported revenues increasing 6% year over year. Organic constant-currency revenues advanced 7%, following 8% growth in the preceding quarter.
Experis revenues declined 3% on a reported basis but remained flat organically in constant currency, improving from a 2% decrease in the second quarter. Management highlighted the return to growth for Experis in the United States as an important milestone.
Talent Solutions recorded 1% revenue growth on both reported and organic constant-currency bases. Growth in recruitment process outsourcing and managed service provider activities was partially offset by weaker Right Management performance due to lower outplacement activity.
ManpowerGroup Improves Profitability Through Cost Cuts
Gross margin contracted 70 basis points year over year to 15.9%, reflecting changes in staffing mix, permanent recruitment and career transition activities. Total gross profit was $767 million.
Selling, general and administrative expenses declined to $685 million from $702.3 million a year earlier. Excluding restructuring and transformation charges, adjusted expenses were $666.9 million, representing 13.8% of revenues compared with 15.2% in the prior-year quarter.
Reported operating profit was $82 million, with an operating margin of 1.7%. Adjusted operating profit reached $100 million, highlighting a 2.1% margin.
The company's global transformation program expanded to the United Kingdom during the quarter. Management remains on track to deliver $200 million in annual cost savings by 2028.
MAN's Balance Sheet and Cash Flow Position
ManpowerGroup ended the third quarter with total debt of $1.1 billion and net debt of $870 million. The total debt-to-capitalization ratio stood at 34% compared with 33% at the end of the preceding quarter.
Free cash flow represented an outflow of $17 million compared with an inflow of $45 million in the year-ago quarter. Management attributed the negative performance partly to the timing of managed service provider payments. Excluding these items, free cash flow would have represented an inflow of $75 million.
Capital expenditures totaled $9 million compared with $15 million a year earlier.
ManpowerGroup Provides Q4’26 Outlook
Management expects fourth-quarter 2026 adjusted earnings per share between $1.03 and $1.13, excluding restructuring and transformation costs. The midpoint ($1.08) of the guided range stands lower than the Zacks Consensus Estimate of $1.1. The outlook assumes an effective tax rate of 44% and no currency impact on earnings.
Revenues are projected to increase 3%-7% year over year, or 4%-8% organically in constant currency. Gross margin is expected between 15.8% and 16%, while adjusted EBITA margin is projected at 2.2%-2.4%.
Regionally, Americas revenues are expected to grow 7%-11%, Southern Europe revenues are projected to remain flat or increase 4%, and Northern Europe revenues are anticipated to rise 8%-12%. Asia-Pacific and Middle East revenues are expected to increase 1%-5%.
MAN currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Earnings Snapshot
Accenture plc ACN reported impressive fourth-quarter fiscal 2026 results.
ACN's earnings of $3.29 per share beat the Zacks Consensus Estimate of $3.19 by 3.1%. Earnings rose 9% from adjusted earnings of $3.03 in the year-ago quarter.
Revenues of $18.7 billion topped the consensus mark of $18.01 billion by 3.8% and increased 6% year over year in U.S. dollars.
FactSet Research Systems Inc. FDS reported impressive results for fourth-quarter fiscal 2026.
FDS’s adjusted earnings were $4.52 per share, beating the Zacks Consensus Estimate of $4.32 by 4.6%. The figure jumped 11.6% from the year-ago quarter.
Revenues of $634.7 million topped the consensus mark of $628.2 million by 1% and rose 6.3% year over year.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ManpowerGroup Inc. (MAN): Free Stock Analysis Report
Accenture PLC (ACN): Free Stock Analysis Report
FactSet Research Systems Inc. (FDS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).