

Abbott ABT reported third-quarter 2026 adjusted earnings per share of $1.42, up 9.2% year over year. The figure missed the Zacks Consensus Estimate by 0.7%.
Sales increased 14.5% year over year to $13.01 billion, surpassing the consensus mark by 0.3%. Comparable sales rose 7%, supported by growth across all four operating segments.
Following the earnings announcement, ABT stock fell 3.6% in pre-market trading today.
ABT's Medical Devices Maintain Growth Momentum
Medical Devices sales increased 6.9% year over year on a reported basis to $5.83 billion. Comparable sales advanced 7.8%, reflecting growth across several cardiovascular and diabetes-care businesses.
Electrophysiology sales climbed 15.5% on a comparable basis, while Rhythm Management and Heart Failure advanced 10% and 6%, respectively. Diabetes Care sales grew 6.7%, supported by a 7.7% increase in continuous glucose monitor (CGM) sales. Vascular sales improved 5.7%, while Structural Heart rose 6.9%. Neuromodulation sales declined 1.1%.
Abbott Laboratories Price, Consensus and EPS Surprise
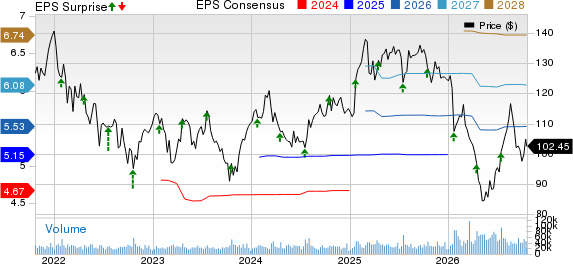
Abbott Laboratories price-consensus-eps-surprise-chart | Abbott Laboratories Quote
Abbott's Diagnostics Gain From Cancer Testing
Diagnostics sales surged 46.7% year over year on a reported basis to $3.31 billion, reflecting contributions from the March 2026 acquisition of Exact Sciences. Comparable sales increased 6.4%.
Cancer Diagnostics sales totaled $968 million and grew 13.8% on a comparable basis. Performance benefited from Cologuard growth and contributions from precision oncology and international operations.
Core Laboratory Diagnostics sales increased 5.4%, driven by balanced growth across the United States, Europe, Japan and Latin America. Rapid and Molecular Diagnostics sales improved 0.9% on a comparable basis, supported by modest growth in both domestic and international markets.
ABT's Nutrition Business Returns to Growth
Nutrition sales increased 5.1% year over year on a reported basis to $2.26 billion. Comparable sales rose 4.9%, reflecting broad-based improvement across the portfolio.
Pediatric Nutrition sales advanced 8.7% on a comparable basis, while Adult Nutrition increased 1.8%. U.S. Nutrition sales climbed 7.9%, supported by 11% growth in domestic Pediatric Nutrition. International Nutrition sales rose 2.8% on a comparable basis. Total Nutrition revenues also improved sequentially by $118 million from the second quarter of 2026.
Abbott's EPD Growth Remains Broad-Based
Established Pharmaceuticals sales increased 6.8% year over year on a reported basis to $1.61 billion. Comparable sales grew 8.4%, reflecting continued expansion across international markets.
Key Emerging Markets sales advanced 10.9% on a comparable basis, supported by double-digit growth in India and several Latin American and Asia-Pacific markets. Sales in other markets increased 1.6% on a comparable basis. Key Emerging Markets generated $1.20 billion in quarterly revenues, while other markets contributed $419 million.
ABT's Q3 Margin Details
In the third quarter, adjusted gross profit increased 17.4% year over year to $7.45 billion. The adjusted gross margin expanded approximately 143 basis points (bps) to 57.2%.
Adjusted selling, general and administrative expenses increased 16.7% year over year to $3.51 billion. Adjusted research and development expenses grew 22.2% to $892 million. Adjusted operating profit rose 16.9% to $3.05 billion, while the adjusted operating margin expanded approximately 49 bps to 23.4%.
Abbott's 2026 and Q4 Financial Guidance
Abbott tightened its full-year 2026 adjusted earnings guidance to $5.50-$5.55 per share, reaffirming the midpoint of its previous $5.45-$5.60 range. The Zacks Consensus Estimate currently stands at $5.53 per share.
The company now projects approximately 6% comparable sales growth for 2026 compared with its previous guidance of 6.5%-7.5%.
For the fourth quarter, management expects adjusted EPS of $1.62-$1.67. The Zacks Consensus Estimate for the same stands at $1.65.
Our Take
Abbott exited the third quarter of 2026 with an earnings miss, while revenues surpassed expectations. Within Diagnostics, Core Laboratory results benefited from balanced growth across the United States, Europe, Japan and Latin America. Cancer Diagnostics gained from Cologuard growth and contributions from precision oncology and international operations. Strong performance in Electrophysiology and Rhythm Management supported Medical Devices results. The expansion of the adjusted gross margin and recovery in Nutrition sales are also encouraging. Meanwhile, higher operating expenses and a reduction in the full-year comparable sales growth outlook remain concerns.
Abbott also highlighted several product developments. The company secured FDA approval for Libre Duo, a dual glucose-ketone wearable sensor, and TactiFlex Duo, an ablation catheter for treating atrial fibrillation. It also received CE Mark approval for Amulet 360, launched the SimpleScreen CRC blood-based colorectal cancer screening test and introduced Similac 360 Total Care Made With Whole Milk in the United States.
ABT’s Zacks Rank and Other Key Picks
Abbott currently carries a Zacks Rank #2 (Buy).
Some other top-ranked stocks from the broader medical space are Phibro Animal Health PAHC, Agilent Technologies A and Globus Medical GMED.
Phibro Animal Health, sporting a Zacks Rank #1 (Strong Buy), reported fourth-quarter fiscal 2026 adjusted EPS of 85 cents, which surpassed the Zacks Consensus Estimate by 18.06%. Revenues of $396.7 million beat the Zacks Consensus Estimate by 8.35%. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
PAHC has an earnings yield of 8.9% compared with the industry’s 2.8%. The company beat earnings estimates in each of the trailing four quarters, the average surprise being 18.36%.
Agilent Technologies,carrying a Zacks Rank #2 at present, posted third-quarter fiscal 2026 adjusted EPS of $1.62, exceeding the Zacks Consensus Estimate by 9.5%. Revenues of $1.88 billion topped the Zacks Consensus Estimate by 2.1%.
A has an earnings yield of 3.7% compared with the industry’s 2.8%. The company’s earnings outpaced estimates in two of the trailing four quarters, broke even once and missed on another one, the average surprise being 3.8%.
Globus Medical,carrying a Zacks Rank #2 at present, posted second-quarter 2026 adjusted EPS of $1.34, exceeding the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million outperformed the Zacks Consensus Estimate by 0.4%.
GMED has an estimated earnings yield of 6.6% against the industry’s 2.3% decline. The company’s earnings outpaced estimates in each of the trailing four quarters, the average surprise being 27.9%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Abbott Laboratories (ABT): Free Stock Analysis Report
Agilent Technologies, Inc. (A): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).