

Hospital operator HCA Healthcare, Inc. HCA is set to report third-quarter 2026 results on Oct. 27, before the opening bell. The Zacks Consensus Estimate for earnings is currently pegged at $6.75 per share on revenues of $19.38 billion.
The third-quarter earnings estimate has seen one upward and one downward revision over the past 30 days. The Zacks Consensus Estimate for earnings indicates a year-over-year decline of 3%, while the same for revenues implies growth of 1.1%.
Image Source: Zacks Investment Research
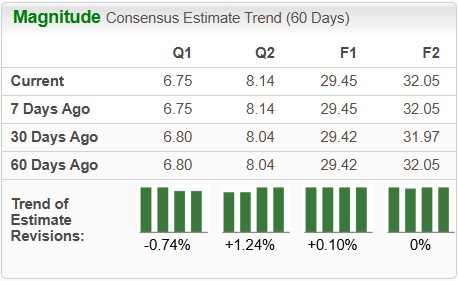
For 2026, the Zacks Consensus Estimate for revenues is pegged at $78.58 billion, implying a rise of 3.9% year over year. The consensus mark for 2026 EPS is pegged at $29.45, implying an increase of 4.4% year over year.
HCA Healthcare’s earnings beat estimates in three of the last four quarters and missed once, with the average surprise being 8%. This is depicted in the figure below.
HCA Healthcare, Inc. Price and EPS Surprise
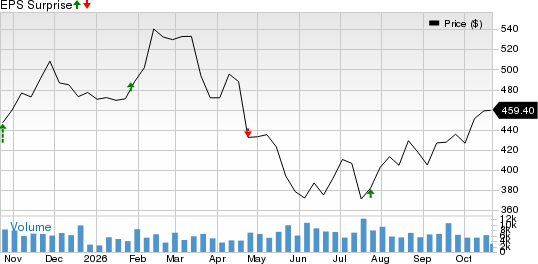
HCA Healthcare, Inc. price-eps-surprise | HCA Healthcare, Inc. Quote
Q3 Earnings Whispers for HCA
Our proven model does not conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That’s not the case here.
HCA has an Earnings ESP of -0.73% and a Zacks Rank #3 at present. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
What’s Shaping HCA Healthcare’s Q3 Results?
The Zacks Consensus Estimate for third-quarter equivalent admissions indicates 1.7% year-over-year growth, whereas our model estimate suggests a 1.9% jump.
The consensus estimate for occupancy is pegged at 73%, up from 71.7% a year ago. The Zacks Consensus Estimate for inpatient revenue per admission indicates a 4.3% year-over-year increase. Our model estimate suggests a 6.6% jump for the same.
While these factors are likely to have positioned HCA Healthcare for growth from the year-ago quarter, rising expenses, lower average length of stay, outpatient surgery cases and revenue per equivalent admission make an earnings beat uncertain.
Our model estimate for third-quarter total operating expenses indicates a 2% increase from a year ago, due to higher salaries & benefits and other operating expenses. We expect other operating expenses to jump 5.4%.
The Zacks Consensus Estimate for average length of stay indicates a 1.3% decline from the year-ago period. Moreover, both the consensus estimate and our model estimate for outpatient surgery cases imply a 1.3% fall from a year ago. The consensus estimate for revenue per equivalent admission suggests a 1% year-over-year decline, while our estimate indicates a milder decrease of 0.4%.
Stocks That Warrant a Look
While an earnings beat looks uncertain for HCA Healthcare, here are some companies from the broader Medical space that you may want to consider, as our model shows that these have the right combination of elements to post an earnings beat this time around:
Phibro Animal Health Corporation PAHC has an Earnings ESP of +2.10% and a Zacks Rank #1 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Phibro’s third-quarter bottom line suggests 8.2% year-over-year growth. Its earnings beat estimates in each of the past four quarters, with an average surprise of 18.4%. PAHC’s revenues for the third quarter are pegged at $378.5 million, suggesting a 4% increase from the year-ago period.
ProMIS Neurosciences, Inc. PMN has an Earnings ESP of +22.43% and a Zacks Rank #2 at present.
The Zacks Consensus Estimate for ProMIS' third-quarter loss is pinned at $1.26 per share, indicating a 79% year-over-year improvement. PMN has witnessed one upward revision against no downward movement over the past 30 days.
Illumina, Inc. ILMN has an Earnings ESP of +9.16% and a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Illumina’s third-quarter bottom line suggests 3% year-over-year growth. Its earnings beat estimates in each of the past four quarters, with an average surprise of 9.7%. ILMN’s revenues for the to-be-reported quarter are pegged at $1.14 billion, indicating a 5% increase from the year-ago period’s level.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
HCA Healthcare, Inc. (HCA): Free Stock Analysis Report
Illumina, Inc. (ILMN): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
Promis Neurosciences (PMN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).