

Norfolk Southern Corporation NSC reported impressive third-quarter 2026 results, wherein both earnings and revenues beat the Zacks Consensus Estimate. Quarterly adjusted earnings (excluding 25 cents from non-recurring items) of $3.62 per share surpassed the consensus estimate of $3.48 by 4% and increased 9.7% year over year.
Railway operating revenues of $3.53 billion beat the consensus estimate of $3.46 billion by 1.8% and increased 13.6% year over year to a quarterly record. The improvement was driven by higher fuel surcharge revenues, 3% volume growth and improved revenue per unit.
Norfolk Southern Corporation Price, Consensus and EPS Surprise
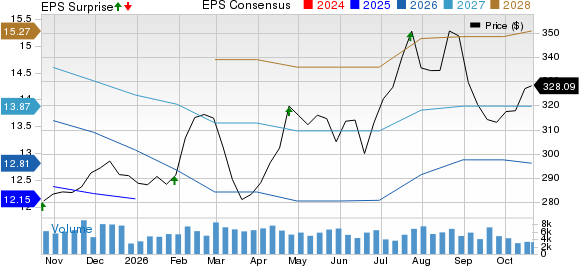
Norfolk Southern Corporation price-consensus-eps-surprise-chart | Norfolk Southern Corporation Quote
NSC's Revenue Highlights
Total railway operating units increased 3% year over year to 1.85 million. Revenue per unit rose 11% to $1,902. Fuel surcharge revenues surged 125% to $468 million.
Excluding fuel surcharges, revenues increased 6% year over year to $3.06 billion, while revenue per unit improved 3% to $1,650.
Norfolk Southern's Merchandise Revenues Rise
Merchandise revenues increased 11% year over year to $2.19 billion, supported by 3% unit growth. Revenue per unit improved 8% to $3,579.
Chemicals revenues rose 16% to $658 million, metals and construction revenues increased 15% to $516 million, and agriculture, forest and consumer products revenues grew 10% to $696 million. Automotive revenues declined 1% to $318 million.
NSC's Intermodal and Coal Businesses Gain
Intermodal revenues jumped 21% year over year to $919 million, with units increasing 3%. Domestic intermodal units grew 10%, while international units declined 8%.
Coal revenues increased 12% to $419 million, supported by 3% unit growth. Export coal tonnage increased 10%, while utility and domestic metallurgical coal tonnage declined 2% and 8%, respectively.
Norfolk Southern's Expenses Weigh on Margins
Adjusted railway operating expenses increased 17% year over year to $2.31 billion. Fuel expenses surged 77% to $420 million, while adjusted compensation and benefits expenses rose 5% to $753 million. Purchased services and rents expenses increased 5% to $546 million.
Adjusted income from railway operations increased 7% to $1.22 billion. However, the adjusted operating ratio (operating expenses as a percentage of revenues) deteriorated 210 basis points year over year to 65.4%.
NSC's Operational Performance Remains Mixed
Train speed declined 5% year over year to 20.9 miles per hour, while terminal dwell increased 4% to 23.2 hours. However, train speed improved 5% sequentially, while terminal dwell improved 3%.
Workforce productivity increased 5% year over year. Merchandise plan compliance declined to 74% from 80%, while the intermodal service composite fell to 84% from 92%.
Norfolk Southern's Liquidity
NSC exited the third quarter with cash and cash equivalents of $1.60 billion compared with $1.53 billion at 2025-end. Long-term debt declined to $15.96 billion from $16.48 billion.
Operating cash flow for the first nine months of 2026 declined to $2.72 billion from $3.30 billion a year ago. Property additions totaled $1.41 billion, while dividend payments amounted to $910 million.
NSC's 2026 Outlook
Norfolk Southern raised its 2026 adjusted operating expense forecast to approximately $9 billion from its original guidance of $8.2-$8.4 billion, reflecting approximately $700 million in incremental fuel costs and higher volumes.
Capital expenditures are now expected to be approximately $2.1 billion, remaining below the 2025 level. Management continues to prioritize safety, reliable service and disciplined cost control.
Currently, NSC carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Q3 Performance of Other Transportation Companies
Alaska Air Group, Inc. ALK reported third-quarter 2026 adjusted earnings of 36 cents per share, excluding certain tax impacts, beating the Zacks Consensus Estimate of 35 cents by 2.9%. The company had reported adjusted earnings of $1.05 per share a year earlier. Higher fuel expenses weighed on profitability despite strong revenue momentum.
Operating revenues increased 14.4% year over year to $4.30 billion but missed the consensus mark of $4.31 billion marginally by 0.1%.
Wabtec Corporation WAB reported mixed third-quarter 2026 results, wherein earnings surpassed the Zacks Consensus Estimate, but revenues missed the same.
Quarterly earnings (excluding 41 cents from non-recurring items) of $2.83 per share beat the Zacks Consensus Estimate of $2.72 by 4.04% and increased 22% year over year. Revenues climbed 8.1% year over year to $3.12 billion but missed the consensus mark of $3.18 billion by 2%. The 12-month backlog increased 8.8% to $8.99 billion.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Norfolk Southern Corporation (NSC): Free Stock Analysis Report
Alaska Air Group, Inc. (ALK): Free Stock Analysis Report
Wabtec (WAB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).