

The Chefs' Warehouse, Inc. CHEF is likely to witness top-and bottom-line growth when it reports third-quarter 2026 earnings on Oct. 28. The Zacks Consensus Estimate for revenues is pegged at $1.1 billion, indicating a 10.4% increase from the year-ago reported number.
The consensus mark for earnings has declined by 2 cents over the past 30 days to 59 cents a share, which, however, suggests an 18% jump from the year-ago period’s figure. CHEF has a trailing four-quarter surprise of 30.4%, on average.
The Chefs' Warehouse, Inc. Price, Consensus and EPS Surprise
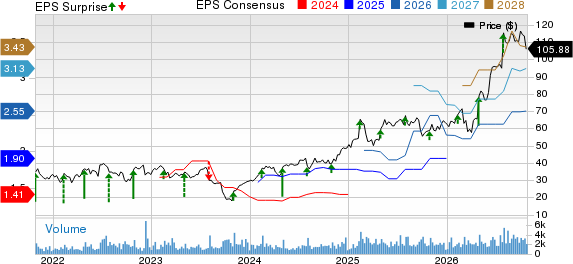
The Chefs' Warehouse, Inc. price-consensus-eps-surprise-chart | The Chefs' Warehouse, Inc. Quote
Factors Likely to Influence CHEF’s Upcoming Results
The Chefs’ Warehouse is likely to have benefited from sustained demand across its specialty food and center-of-the-plate categories. Management highlighted continued business momentum into July and anticipated double-digit top-line growth at the beginning of the quarter. Consistent demand from its upscale dining customer base and continued strength across product categories may have supported sales growth.
Continued market share gains, driven by increasing product penetration, higher case volumes and customer additions, are likely to have aided organic sales. Cross-selling opportunities, expanding product offerings and improving productivity among its maturing sales force may have further supported growth. The company's differentiated specialty distribution model and emphasis on customer relationships are expected to have strengthened its competitive positioning.
CHEF's investments in distribution capacity, sales capabilities and operational infrastructure are likely to have supported higher volumes and improved operating leverage. Growing businesses in markets such as Texas and Florida, alongside better utilization of existing facilities, may have aided performance. Route consolidation, improved logistics and greater distribution efficiencies are expected to have supported productivity and profitability.
Investments in pricing, procurement and technology-driven analytics may have boosted gross margins. Improved sourcing capabilities, inventory management and collaboration across sales and procurement teams are likely to have aided profitability. Management indicated that third-quarter EBITDA margins generally follow a seasonal pattern similar to the second quarter, although the latter is typically somewhat stronger.
However, geopolitical disruptions and seasonally subdued tourism in the Middle East could have weighed on regional demand. Elevated diesel prices, higher logistics costs and product-mix fluctuations may also have pressured margins during the quarter.
Earnings Whispers for CHEF
Our proven model doesn’t conclusively predict an earnings beat for The Chefs' Warehouse this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
The Chefs' Warehouse currently carries a Zacks Rank #2 and has an Earnings ESP of -1.70%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With the Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Altria Group, Inc. MO currently has an Earnings ESP of +0.26% and a Zacks Rank #2. The consensus estimate for quarterly revenues is pegged at $5.3 billion, which indicates an improvement of about 1% from the figure reported in the prior-year quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Altria’s upcoming quarter’s EPS is pegged at $1.51, which calls for 4.1% growth from the figure reported in the prior-year quarter. MO delivered a trailing four-quarter earnings surprise of 1.3%, on average.
Sysco Corporation SYY currently has an Earnings ESP of +2.46% and a Zacks Rank of 3. The consensus estimate for the quarterly revenues is pinned at $22.2 billion, which suggests 4.9% growth from the figure reported in the prior-year quarter.
The Zacks Consensus Estimate for Sysco’s upcoming quarter’s EPS is pegged at $1.17, which calls for a 1.7% increase from the year-ago period’s figure. SYY delivered a trailing four-quarter earnings surprise of nearly 1%, on average.
Archer-Daniels-Midland Company ADM currently has an Earnings ESP of +18.48% and a Zacks Rank of 3. The Zacks Consensus Estimate for its upcoming quarter’s revenues is pegged at $22.7 billion, suggesting 11.3% growth from the figure reported in the prior-year quarter.
The consensus estimate for Archer-Daniels’ earnings is pegged at $1.44 per share, implying an increase of 56.5% from the year-ago quarter. ADM delivered a trailing four-quarter earnings surprise of 11.3%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Chefs' Warehouse, Inc. (CHEF): Free Stock Analysis Report
Altria Group, Inc. (MO): Free Stock Analysis Report
Archer Daniels Midland Company (ADM): Free Stock Analysis Report
Sysco Corporation (SYY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).