

Rambus Inc. RMBS outlined strengthening demand for its memory interface chips and silicon IP solutions during its third-quarter 2026 earnings call, supported by expanding AI infrastructure deployments and next-generation server platforms.
The company reported third-quarter adjusted earnings of $0.84 per share, beating the Zacks Consensus Estimate of $0.78. Revenues of $218.29 million also surpassed the $213 million consensus.
Rambus, Inc. Price, Consensus and EPS Surprise
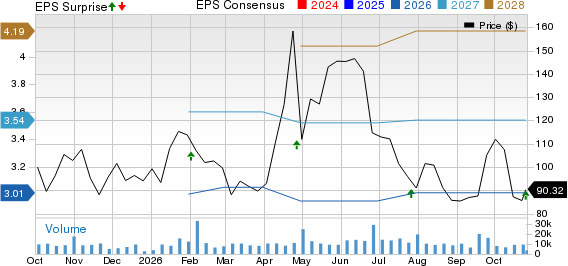
Rambus, Inc. price-consensus-eps-surprise-chart | Rambus, Inc. Quote
Management emphasized accelerating product revenues, improving backlog visibility and continued investment in advanced memory technologies. However, tightening semiconductor supply conditions and input cost pressures remain important considerations heading into 2027.
RMBS Projects Stronger Q4 Growth
Chief financial officer Sumeet Gagneja projected fourth-quarter revenues between $227 million and $233 million, with product revenues ranging from $127 million to $133 million.
At the midpoint, product revenue guidance represents 34% year-over-year growth and 14% sequential growth. Non-GAAP earnings per share are expected between $0.84 and $0.92.
Gagneja indicated that midpoint guidance implies approximately 18% revenue growth and 24% non-GAAP earnings growth for 2026.
Rambus Sees Broader Demand for Memory Chips
CEO Luc Seraphin attributed accelerating product demand primarily to newer generations of DDR5 registering clock driver (RCD) chips and growing adoption of companion chips.
During the Jefferies Q&A, Seraphin clarified that companion chip revenues continue increasing sequentially, while MRDIMM shipments remain modest and largely associated with qualification and preproduction.
Management maintained its $600 million estimate for the overall MRDIMM opportunity but expects a slower adoption curve than traditional RCD products. Seraphin also highlighted growing memory module volumes despite customers selecting lower-capacity modules to manage memory costs.
RMBS Faces Tightening Semiconductor Supply
Supply chain constraints emerged as an important discussion point during the analyst Q&A, particularly regarding manufacturing lead times and the company's ability to support accelerating demand.
Responding to Evercore ISI, Seraphin acknowledged increasing supplier lead times but emphasized that mitigation measures prevented disruptions to third-quarter performance and expected fourth-quarter deliveries.
He added that customer lead times have remained stable despite tightening industry conditions. During the Baird exchange, management acknowledged that supply will remain tight in 2027, requiring continued coordination with manufacturing partners and inventory investments.
Rambus Expands Its AI Infrastructure Portfolio
Seraphin highlighted growing opportunities across high-bandwidth memory, PCIe connectivity and hardware security IP as hyperscalers develop increasingly customized AI processors.
The company reported new Tier 1 design wins involving next-generation HBM technology and introduced security IP supporting the Caliptra specification. It also expanded its memory portfolio with an LPDDR6 power management chip for SOCAMM2 modules.
During the William Blair Q&A, Seraphin explained that newer SOCAMM2 designs should increase Rambus' dollar content per module, although broader commercialization is expected around 2028. Gagneja separately indicated that silicon IP growth is trending toward the upper end of its previously communicated 10%-15% annual range.
RMBS Balances Margin Pressures and Investment
Product gross margins attracted scrutiny during the William Blair Q&A after non-GAAP margins approached the lower end of management's historical 60%-63% range.
Gagneja attributed the pressure primarily to rising supply chain input costs, partially offset by internal efficiency improvements. He expects margins to remain within the near-term range during the fourth quarter, with only modest potential improvement.
Management also highlighted a strategic investment and collaboration with ChipAgents to accelerate chip and IP development using agentic AI design tools. The initiative targets engineering productivity, design quality and faster product development.
Rambus Maintains Focus on Profitable Expansion
Management's broader message centered on sustaining product innovation while maintaining financial flexibility and dependable customer supply.
Gagneja highlighted record quarterly operating cash flow of $102.5 million and completion of a $100 million accelerated share repurchase. The company intends to return 40%-50% of free cash flow to shareholders over time.
Seraphin expressed confidence in strengthening demand and improved backlog visibility entering 2027, while acknowledging that supply availability will require continued attention.
What RMBS' Zacks Rank and Style Scores Indicate
Rambus currently carries a Zacks Rank #3 (Hold), reflecting a neutral near-term earnings estimate revision outlook. Its Value Score of F, Growth Score of C and Momentum Score of D indicate relatively unfavorable valuation characteristics, moderate growth attractiveness and weaker momentum characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its VGM Score of D reflects an unfavorable combined assessment across value, growth and momentum factors. These scores offer limited support for near-term outperformance based on the Zacks framework. However, the Zacks Rank can change as analysts revise their earnings estimates following the latest quarterly results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Rambus, Inc. (RMBS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).