

The Williams Companies, Inc. WMB is set to release third-quarter 2026 results on Nov. 2. The Zacks Consensus Estimate for the to-be-reported quarter is pegged at a profit of 56 cents per share on revenues of $3.2 billion.
Let’s delve into the factors that might have influenced the oil and gas pipeline operator’s performance in the to-be-reported quarter. But it’s worth taking a look at Williams’ previous-quarter results first.
Highlights of Q2 Earnings & Surprise History
Last quarter, the energy infrastructure provider reported adjusted earnings per share of 50 cents, missing the Zacks Consensus Estimate of 52 cents. Revenues of $3 billion also fell short of the consensus mark by $2 million.
WMB missed the Zacks Consensus Estimate for earnings in three of the last four quarters and beat in one, resulting in an earnings surprise of negative 0.2%, on average. This is depicted in the graph below:
Williams Companies, Inc. (The) Price and EPS Surprise
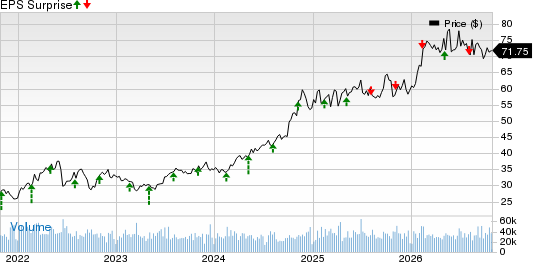
Williams Companies, Inc. (The) price-eps-surprise | Williams Companies, Inc. (The) Quote
Trend in Estimate Revision
The Zacks Consensus Estimate for the third-quarter bottom line has remained unchanged in the past 30 days. The estimated figure indicates a 14.3% rise year over year. The Zacks Consensus Estimate for revenues, however, suggests a 9% increase from the year-ago period.
Factors to Consider Ahead of WMB’s Q3 Release
In the to-be-reported quarter, Williams is expected to benefit from the start-up of Socrates Phase 1, which began delivering 200 megawatts of power in early August, with output expected to ramp during the month. Management also reported healthy demand across its Transco network and stronger gathering volumes in the Northeast’s rich-gas areas, supporting its core operations. The $5.5 billion Momentum Midstream acquisition, which closed on Sept. 3, will add Haynesville gathering and contracted pipeline assets to the company’s portfolio, potentially contributing incremental earnings during the quarter. Momentum’s more than 4 Bcf/d of take-or-pay transportation capacity provides contracted revenue support. Management raised its 2026 adjusted EBITDA outlook to $8.3-$8.5 billion, underscoring confidence in business momentum.
But on a bearish note, higher costs might play spoilsport. Investors should know that WMB’s second-quarter total costs and expenses of $1.9 billion increased almost 2% from the year-ago quarter’s figure. This trend is likely to continue in the to-be-reported quarter due to project-related costs and inflationary pressure. An earnings miss remains possible as management flagged weak summer natural gas prices, rig activity and hurricane-season exposure. Moreover, early in-service payments are recognized over contract lives rather than immediately boosting earnings.
What Does Our Model Say About WMB Stock?
Our proven model predicts an earnings beat for Williams this time. A stock needs to have a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) to beat earnings. This is exactly the case here.
WMB’s Earnings ESP: Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, for this company is +1.65%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
WMB’s Zacks Rank: Williams currently carries a Zacks Rank #3.
Other Stocks With the Favorable Combination
Here are some other firms from the energy space that you may want to consider, as these too have the right combination of elements to post an earnings beat this reporting cycle.
Energy Transfer LP ET has an Earnings ESP of +8.46% and a Zacks Rank #3 at present. The firm is scheduled to release earnings on Nov. 3.You can see the complete list of today’s Zacks #1 Rank stocks here.
Notably, the Zacks Consensus Estimate for Energy Transfer’s2026 earnings indicates 43% year-over-year growth. Valued at around $70.4 billion, Energy Transfer’sshares have gained 21.9% in a year.
Ovintiv Inc. OVV presentlyhas an Earnings ESP of +12.78% and a Zacks Rank #2. The firm is scheduled to release earnings on Nov. 3.
Notably, the Zacks Consensus Estimate for Ovintiv’s 2026 earnings per share indicates 63% year-over-year growth. Valued at around $19.9 billion, Ovintiv’s shares have jumped 94.2% in a year.
APA Corporation APA has an Earnings ESP of +1.15% and a Zacks Rank #2 at present. The firm is scheduled to release earnings on Nov. 4.
Notably, the Zacks Consensus Estimate for APA’s 2026 earnings indicates 65.5% year-over-year growth. Valued at around $18.2 billion, APA’s shares have surged 121.3% in a year.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Williams Companies, Inc. (The) (WMB): Free Stock Analysis Report
APA Corporation (APA): Free Stock Analysis Report
Energy Transfer LP (ET): Free Stock Analysis Report
Ovintiv Inc. (OVV): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).