

CoStar Group CSGP reported adjusted earnings of 38 cents per share for the third quarter of 2026, up 65.2% year over year. The figure surpassed the Zacks Consensus Estimate by 11.77%.
Revenues increased 14.1% year over year to $952 million, beating the consensus estimate by 0.11%. The company recorded its 62nd consecutive quarter of double-digit revenue growth.
Disciplined cost management boosted profitability, while net new bookings totaled $37 million amid economic headwinds and slower sales-force expansion.
CSGP’s Commercial Business Maintains Steady Growth
Commercial Real Estate revenues increased 6.7% year over year to $492 million, which accounted for 51.7% of total revenues. Commercial adjusted EBITDA declined 1.6% to $180 million, reflecting investments in upcoming product launches and international expansion.
CoStar Group, Inc. Price, Consensus and EPS Surprise
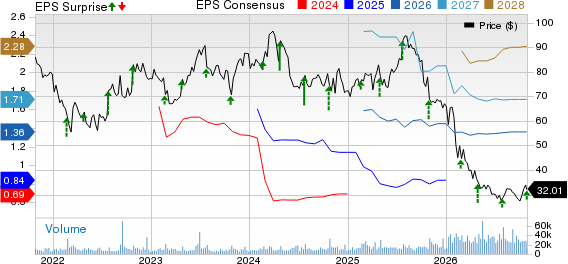
CoStar Group, Inc. price-consensus-eps-surprise-chart | CoStar Group, Inc. Quote
Within the commercial portfolio, CoStar revenues rose 8.2% year over year to $344 million, supported by 17% subscriber growth and a 92% renewal rate. LoopNet revenues rose 12.7% year over year to $89 million, driven by sales-force expansion and stronger bookings. Other Commercial Real Estate revenues declined 7.8% year over year to $59 million, primarily due to weakness at Ten-X.
CoStar’s Residential Segment Extends Profitability Gains
Residential Real Estate revenues climbed 23.3% year over year to $460 million, supported by organic growth and acquisition contributions. Residential adjusted EBITDA reached $49 million against a loss of $69 million in the year-ago quarter, improving from $12 million sequentially.
Apartments.com revenues increased 6% year over year to $320 million. Paid properties reached 91,155, up 5% year over year but down 2% sequentially. Monthly renewal rates declined to 98.4%, reflecting sales-capacity constraints and challenging multifamily conditions. Average revenue per property remained unchanged year over year.
CSGP Expands Digital Platforms and AI Capabilities
Homes.com revenues jumped 50% year over year to approximately $31 million. Membership exceeded 36,000, increasing 47% year over year. The introduction of Platinum premium advertising in September helped lift average sales pricing to $429 in October, up 58% from September.
CoStar continued expanding its AI capabilities, including AI-powered tenant research and Apartments.com AI. Matterport subscription revenues increased 11%, while enterprise customer additions grew 46% year over year. The company also announced an agreement to acquire Vexcel for approximately $730 million to strengthen its proprietary real estate data capabilities.
CoStar Expands Margins Through Expense Discipline
Operating expenses declined 7.9% year over year to $657 million. Selling and marketing expenses decreased 12.4% year over year to $366 million, while general and administrative expenses fell 12.1% to $138 million.
Software development expenses increased 2.8% year over year to $109 million, and customer-base amortization rose 37.5% to $44 million.
Adjusted EBITDA doubled to $229 million from $114 million. The adjusted EBITDA margin expanded approximately 1,000 basis points to 24%.
Operating income improved to $84 million from an operating loss of $51 million a year earlier.
CSGP Focuses on Sales Expansion and Efficiency
Net new bookings fell to $84 million from $135 million in the year-ago quarter, reflecting weaker residential demand and insufficient sales capacity. Management expects bookings to improve sequentially in the fourth quarter as recruitment initiatives gain traction.
The company now anticipates approximately $150 million in expense savings against its original 2026 guidance. Management identified another $200 million in efficiency opportunities over the next 12-18 months, spanning organizational restructuring, procurement, marketing and acquisition integration.
CoStar's Cash Position and Capital Allocation
Cash and cash equivalents totaled $500 million as of Sept. 30, 2026, compared with $1.27 billion as of June 30, 2026. Long-term debt remained broadly stable at $994 million.
Operating cash flow totaled $188 million during the quarter and $455 million in the first nine months of 2026.
CSGP repurchased $81 million of shares during the quarter, bringing year-to-date repurchases to $668 million. Management expects to complete its $700 million repurchase program in the fourth quarter.
CSGP Raises Profit Outlook, Updates Revenue Guidance
For the fourth quarter of 2026, CoStar expects revenues of $976-$996 million, adjusted EBITDA of $275-$295 million and adjusted earnings of 46-50 cents per share. Commercial revenues are projected to be $490-$500 million, while Residential revenues are expected to be between $486 million and $496 million.
For 2026, CoStar updated its revenue outlook to $3.75-$3.77 billion, including approximately $60 million from Zonda. The company raised adjusted EBITDA guidance to $820-$840 million and adjusted EPS guidance to $1.38-$1.41.
The revised outlook reflects softer bookings and lower Domain transaction volumes, partially offset by acquisition contributions and stronger expense discipline. Management reaffirmed its target of $1.25 billion in adjusted EBITDA by 2028.
CSGP’s Zacks Rank & Other Stocks to Consider
CoStar Group currently carries a Zacks Rank #2 (Buy).
Some other top-ranked stocks in the broader Zacks Computer and Technology sector include ACI Worldwide ACIW, Affirm AFRM and AMETEK AME. While AFRM and AME sport a Zacks Rank #1 (Strong Buy), ACI Worldwide carries a Zacks Rank #2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
ACI Worldwide shares have gained 14.3% in the year-to-date period. ACI Worldwide is set to report third-quarter 2026 results on Nov. 5.
Shares of Affirm have plunged 2.3% year to date. Affirm is set to report first-quarter fiscal 2027 results on Nov. 5.
Shares of AMETEK have rallied 19.9% year to date. AMETEK is slated to report third-quarter 2026 results on Nov. 3.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CoStar Group, Inc. (CSGP): Free Stock Analysis Report
AMETEK, Inc. (AME): Free Stock Analysis Report
ACI Worldwide, Inc. (ACIW): Free Stock Analysis Report
Affirm Holdings, Inc. (AFRM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).