

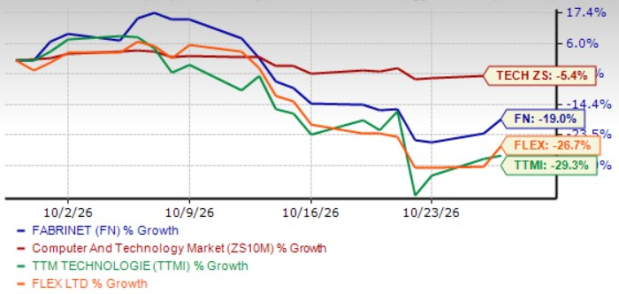
Fabrinet FN shares have dropped 19% in the past month, underperforming the Zacks Computer and Technology sector’s decline of 5.3%. However, FN shares have outperformed peers, including TTM Technologies TTMI and Flex FLEX, over the same time frame. Shares of TTM Technologies and Flex have plunged 29.3% and 26.7%, respectively.
The decline in FN price performance can be attributed to concerns over customer concentration, slowing NVIDIA NVDA-related transceiver revenues, margin pressure and elevated capital spending. A stretched valuation is also a concern. However, Fabrinet’s exposure to AI infrastructure, data-center interconnect (DCI), high-performance computing (HPC), and next-generation optical technologies provides meaningful growth opportunities. So, what should investors do with FN stock? Let’s dig deep to find out.
FN Stock’s Price Performance
Image Source: Zacks Investment Research
Fabrinet Shares are Overvalued
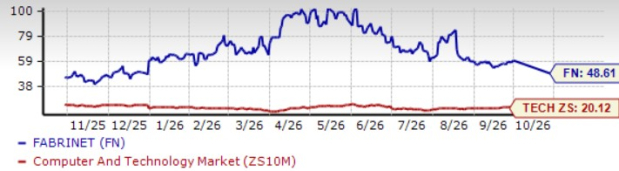
Fabrinet shares are overvalued, as suggested by a Value Score of C. The FN stock is trading at price/cash flow (P/CF) multiple of 48.61 compared with the broader sector’s 20.12.
FN shares are trading at a premium compared with peers, including TTM Technologies and Flex. Shares of TTM Technologies and Flex are trading at a P/CF multiple of 28.94 and 19.96, respectively.
FN Stock’s Valuation
Image Source: Zacks Investment Research
FN to Suffer From Slowing NVDA Revenues
Fabrinet’s relationship with NVIDIA has become an important concern for investors. The company was initially the sole manufacturer of NVIDIA’s 400G and subsequently 800G optical transceivers. However, NVIDIA has diversified its sourcing arrangements, introducing multiple suppliers for 800G products. Fabrinet acknowledged that the exceptional growth generated by its early NVIDIA relationship was unlikely to continue indefinitely. NVIDIA accounted for 16% of Fabrinet's fiscal 2026 revenues. This transition has increased concerns over customer concentration and the need to secure additional hyperscale and merchant transceiver customers for Fabrinet.
Meanwhile, Fabrinet’s non-GAAP gross margin contracted 30 basis points year over year to 12.2% in the fourth quarter of fiscal 2026 compared with 12.5% in the year-ago period. Although operating leverage supported profitability, the gross margin contraction highlights challenges associated with product mix, manufacturing costs and scaling complex optical products. The company's expectation of seasonal margin pressure in the first quarter of fiscal 2027 has added to investor caution.
Fabrinet’s aggressive manufacturing capacity expansion has pressured near-term cash generation. Capital expenditures increased to $92 million in the fourth quarter of fiscal 2026, while operating cash flow totaled $55 million, resulting in negative free cash flow of approximately $37 million. For fiscal 2026, operating cash flow reached $257 million, but free cash flow was only approximately $4 million. Investors are expected to remain cautious until FN’s capacity investments translate into stronger free cash flow.
Can Strong AI Data-Center Demand Aid FN’s Recovery?
Fabrinet is benefiting from accelerating investments in AI infrastructure, hyperscale computing and high-speed optical networking. Growing demand for advanced transceivers, DCI solutions and HPC products is expected to support sustained revenue growth. For the first quarter of fiscal 2027, Fabrinet projected revenues of $1.375-$1.425 billion, implying approximately 43% year-over-year growth at the midpoint. The company expects broad-based demand across its data center and communications businesses to sustain momentum through fiscal 2027.
Fabrinet's DCI business represents a major long-term growth opportunity, supported by increasing adoption of 400ZR, 800ZR and ZR+ optical technologies. DCI’s annualized revenue run rate exceeded $1 billion in fiscal 2026, reflecting strong demand from leading networking equipment manufacturers. Growing power constraints in hyperscale data centers are encouraging operators to distribute computing infrastructure across locations, increasing demand for high-speed, power-efficient interconnect technologies.
Fabrinet is expanding its customer base beyond NVIDIA through new hyperscale-direct and merchant transceiver manufacturing programs. The company indicated that its hyperscale-direct program would begin ramping in the first quarter of fiscal 2027, while another merchant customer program is expected to begin production in the December 2026 quarter. Additional programs are scheduled to commence in early calendar 2027. FN’s expertise in precision optical manufacturing positions it to capitalize on emerging near-package optics (NPO), co-packaged optics (CPO) and optical circuit switching technologies. Increasing optical integration in AI computing systems is creating demand for advanced photonic packaging and testing capabilities.
FN’s Earnings Estimate Revision Shows Steady Trend
The Zacks Consensus Estimate for first-quarter fiscal 2027 earnings is pegged at $4.19 per share, unchanged over the past 30 days, suggesting 43.5% growth from the figure reported in the year-ago quarter.
Fabrinet Price and Consensus
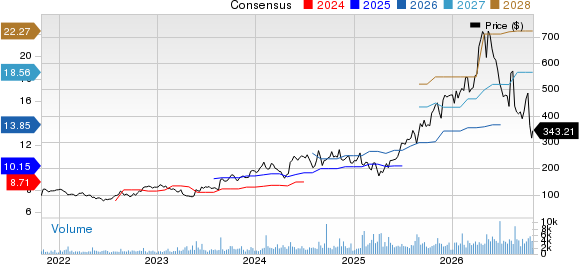
Fabrinet price-consensus-chart | Fabrinet Quote
The consensus mark for fiscal 2026 earnings is pegged at $18.56 per share, unchanged over the past 30 days, suggesting 31.7% growth from fiscal 2026’s reported figure.
Here’s Why FN Stock is a Hold Now
Fabrinet’s recent share-price weakness reflects concerns over customer concentration, normalization of NVIDIA-related growth, margin pressure and subdued free cash flow. However, robust DCI demand, expanding HPC programs, new hyperscale and merchant transceiver wins, and emerging NPO and CPO opportunities provide multiple long-term growth drivers. Sustained growth across a more diversified customer base could strengthen investor confidence, while continued cash flow pressure and dependence on major customers remain considerable risks.
Fabrinet currently has a Zacks Rank #3 (Hold), which implies that investors should wait for a more favorable point to accumulate the stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Fabrinet (FN): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Flex Ltd. (FLEX): Free Stock Analysis Report
TTM Technologies, Inc. (TTMI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).