

J.B. Hunt Transport Services, Inc. JBHT is entering 2027 with improving freight demand, stronger pricing and a profitable brokerage business. Third-quarter 2026 revenues rose 20.4% year over year to $3.68 billion, while earnings increased 3.4% to $1.82 per share.
The recovery is not clean. Higher driver, insurance, fuel and purchased transportation costs continue to pressure margins, and the stock trades above its historical forward earnings valuation. That makes earnings execution increasingly important.
JBHT Growth Outlook Points to a Stronger 2027
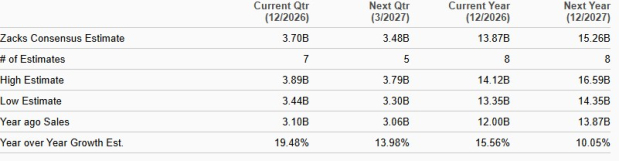
The Zacks Consensus Estimate calls for 2027 revenues of $15.26 billion, up from $13.87 billion projected for 2026. That implies sales growth of 10.1% as freight activity, pricing and customer demand improve.
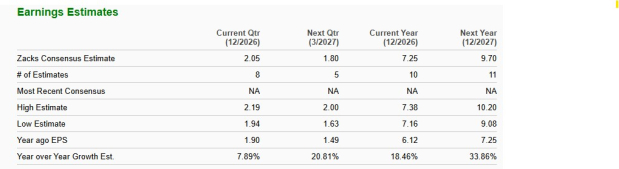
The earnings outlook is stronger. The consensus estimate for 2027 earnings is $9.70 per share compared with $7.25 for 2026, indicating projected growth of 33.8%. The estimates assume that stronger pricing and improving freight conditions translate into better profitability as cost pressures normalize.
J.B. Hunt Intermodal Strengthens the Bull Case
Intermodal remains J.B. Hunt's largest business, generating 50% of 2025 revenues. In the third quarter of 2026, Intermodal revenues rose 20% year over year to $1.83 billion, while volumes increased 8%. Eastern network loads climbed 18%, supported by road-to-rail conversion demand.
The segment's scale, railroad relationships and network efficiency support its competitive position as customers seek reliable capacity. Schneider National, Inc. SNDR is another large North American intermodal provider, while Hub Group, Inc. HUBG offers intermodal, truck brokerage, asset trucking and dedicated transportation services. Their presence underscores the competitive importance of multimodal capacity and service reliability.
JBHT Margin Risks Complicate the Recovery
Revenue growth has not yet translated into consistent margin expansion. Companywide operating margin narrowed to 6.7% in the third quarter from 7.9% a year earlier as purchased transportation, fuel and insurance-related costs increased.
Dedicated Contract Services operating income fell 22% year over year to $81.7 million as driver expenses, medical claims, insurance premiums, equipment costs and new-business onboarding weighed on results. Final Mile Services operating income dropped 76% to $1.6 million, while driver availability also limited Intermodal's ability to capture additional demand.
J.B. Hunt Shares Carry a Premium Valuation
JBHT trades at 25.0X forward 12-month earnings, above the Zacks Transportation - Truck sub-industry multiple of 24.3X and the stock's five-year median of 23.0X. The premium is not extreme, but it leaves less room for disappointment if margin recovery takes longer than expected.
The valuation therefore places more weight on earnings delivery. Stronger pricing, intermodal demand and brokerage profitability can support the case for upside, but investors are already paying above the stock's historical median for that improvement.
JBHT Ratings Point to Growth but Not a Clear Bargain
JBHT's improving 2027 earnings outlook and Intermodal momentum support a constructive fundamental view, but valuation and cost pressure argue against treating the shares as an obvious bargain. The risk-reward profile looks more balanced than compelling at current levels.
The stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It has a Growth Score of B, Value Score of C, Momentum Score of F and VGM Score of C. The Growth Score supports the improving earnings outlook, while the weaker Value and Momentum readings temper the near-term case. Taken together, the ratings favor patience rather than an aggressive buy stance.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
J.B. Hunt Transport Services, Inc. (JBHT): Free Stock Analysis Report
Hub Group, Inc. (HUBG): Free Stock Analysis Report
Schneider National, Inc. (SNDR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).