

Sysco Corporation SYY reported mixed results for the first quarter of fiscal 2027, with earnings surpassing the Zacks Consensus Estimate but revenues falling short. Adjusted earnings were $1.19 per share, which rose 3.5% year over year and beat the Zacks Consensus Estimate of $1.17. Sales increased 2.8% to $21,744 million but missed the consensus mark of $22,192 million.
The company's performance benefited from positive volume growth, gross margin expansion, strategic sourcing efficiencies and improved Sysco Brand penetration. U.S. Foodservice total case volume increased 2.6%, while local case volume advanced 2.7%.
Sysco Corporation Price, Consensus and EPS Surprise
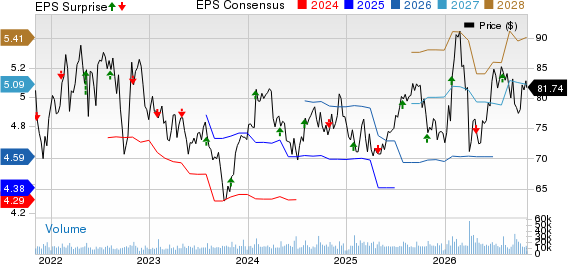
Sysco Corporation price-consensus-eps-surprise-chart | Sysco Corporation Quote
SYY's Sales Growth Reflects Volume Gains
Sysco's top line benefited from positive local volume growth and continued expansion across its U.S. and international operations. Comparable sales on a constant-currency basis increased 3% year over year to $21,779 million.
Foreign currency fluctuations reduced reported sales by $35 million. Product cost inflation was 0.3% at the enterprise level, primarily reflecting higher meat costs. Management cited lower-than-expected U.S. food cost inflation and continued softness in restaurant foot traffic as challenges during the quarter.
Sysco Brand penetration also improved. Sysco Brand sales represented 35.8% of U.S. Broadline cases, up 8 basis points year over year. Among local customers, penetration increased 44 basis points to 46.6%.
Sysco's Cost Profile Supports Margin Expansion
Gross profit increased 3.8% year over year to $4,051 million, while gross margin expanded 18 basis points to 18.63%. Growth reflected higher local volumes, tariff-related benefits, strategic sourcing efficiencies and increased Sysco Brand penetration.
Adjusted operating expenses rose 4% to $3,124 million, reflecting higher volumes and investments in growth areas. The company continued focusing on operating efficiency amid higher-than-expected fuel costs.
Adjusted operating income grew 3.2% to $927 million, while adjusted operating margin expanded 1 basis point to 4.26%. Reported operating income declined 10.4% to $717 million, reflecting higher expenses, including acquisition-related costs associated with the planned Jetro Restaurant Depot transaction.
Adjusted EBITDA increased 5.4% to $1,128 million. Adjusted net earnings advanced 4.2% to $574 million, reflecting improved underlying profitability.
SYY's Segments Show Broad-Based Sales Growth
U.S. Foodservice Operations sales increased 2.4% year over year to $15,142 million. Gross profit grew 3.2% to $2,913 million, while gross margin expanded 14 basis points to 19.24%. Adjusted operating expenses rose 3.4% to $1,972 million, while adjusted operating income increased 2.7% to $941 million.
International Foodservice Operations sales climbed 5.1% to $4,168 million. On a constant-currency basis, sales improved 6% to $4,202 million. Gross profit rose 7.4% to $887 million, while gross margin expanded 45 basis points to 21.28%. Adjusted operating income jumped 12.2% to $165 million. Constant-currency adjusted operating income increased 12.9% to $166 million.
SYGMA sales advanced 1.1% to $2,152 million. However, gross profit declined 1.8% to $167 million, while gross margin contracted 22 basis points to 7.76%. Operating income decreased 16% to $21 million.
The Other segment generated sales of $282 million, up 3.3%. Gross profit increased 10.3% to $75 million, while gross margin expanded 169 basis points to 26.60%. Operating income increased to $9 million from $4 million in the prior-year quarter.
Sysco's Cash Flow and Liquidity Position Improve
During the first 13 weeks of fiscal 2027, cash flow from operations increased to $278 million from $86 million in the prior-year period. Free cash flow improved to $230 million from negative $50 million.
Capital expenditures, net of proceeds from sales of plant and equipment, totaled $48 million. Sysco returned $264 million to shareholders through dividends during the quarter.
The company ended the quarter with cash and cash equivalents of $3,171 million and total liquidity of $5,800 million. Its net debt-to-adjusted EBITDA ratio stood at approximately 2.4 times.
SYY Reaffirms Fiscal 2027 Earnings Guidance
Management reiterated its fiscal 2027 adjusted earnings growth guidance of 9-11%, supported by continued volume growth, operating efficiencies and business transformation initiatives.
The company maintained its expectation for approximately 2.5% local volume growth. However, full-year sales growth is now anticipated at the lower end of its previously announced 6-7% range, reflecting a lower industry inflation environment.
Sysco continues to target $100 million in cost savings from AI-enabled business transformation initiatives included in its fiscal 2027 guidance. Management expects these benefits to accelerate during the second half of the fiscal year.
The company is also preparing for the anticipated closure of its Jetro Restaurant Depot transaction while maintaining its focus on customer service, operating-margin improvement and disciplined expense management.
This Zacks Rank #3 (Hold) stock has risen 12.1% over the past year against the industry’s almost equal decline.
Stocks to Consider
Lamb Weston Holdings, Inc. LW, a leading global manufacturer, marketer and distributor of value-added frozen potato products, currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Lamb Weston’s current fiscal-year EPS implies growth of 7.6% from the year-ago figure. LW delivered a trailing four-quarter earnings surprise of 22.1%, on average.
Mama's Creations, Inc. MAMA, a prepared-foods company focused on fresh, ready-to-eat and deli products, currently carries a Zacks Rank of 2 (Buy). MAMA delivered a trailing four-quarter earnings surprise of 121.7%, on average.
The Zacks Consensus Estimate for Mama's Creations’ current fiscal-year sales and EPS indicates an increase of 30.3% and 66.7%, respectively, from the year-ago period.
The J.M. Smucker Company SJM, a leading manufacturer and marketer of branded food, beverage, pet food and pet snack products, currently carries a Zacks Rank #2. SJM delivered a trailing four-quarter earnings surprise of 13.8%, on average.
The Zacks Consensus Estimate for The J.M. Smucker’s current fiscal-year EPS implies growth of 17.1% from the year-ago figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sysco Corporation (SYY): Free Stock Analysis Report
The J. M. Smucker Company (SJM): Free Stock Analysis Report
Lamb Weston (LW): Free Stock Analysis Report
Mama's Creations, Inc. (MAMA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).