

Gartner IT has reported better-than-expected third-quarter 2026 results, with earnings and revenues surpassing the Zacks Consensus Estimate.
Adjusted earnings of $3.59 per share beat the consensus estimate of $2.86 by 25.5% and increased 30.1% from the year-ago quarter's $2.76.
Revenues of $1.51 billion surpassed the consensus mark of $1.48 billion by 2%. Reported revenues declined 1.3% year over year, while adjusted revenues increased 2.4%.
Higher operating profitability and a lower share count supported earnings growth. Global contract value rose 2.5% year over year on a foreign-currency-neutral basis.
Gartner, Inc. Price, Consensus and EPS Surprise
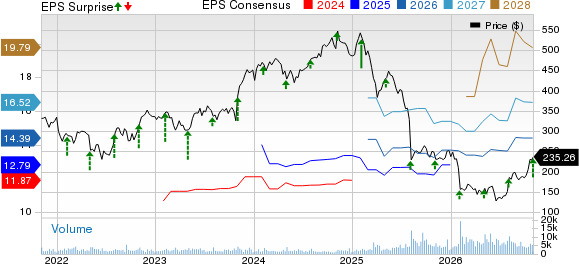
Gartner, Inc. price-consensus-eps-surprise-chart | Gartner, Inc. Quote
IT's Contract Value Growth Accelerates
Global contract value reached $5.3 billion, increasing 2.5% year over year and 1.1% sequentially on a foreign-currency-neutral basis. The sequential increase indicates continued expansion in Gartner's contracted business.
Global Technology Sales contract value reached $4 billion, rising 2.1% year over year and 0.8% sequentially. Global Business Sales contract value increased 3.7% year over year and 1.8% sequentially to $1.3 billion.
Global Business Sales recorded faster contract value growth than Global Technology Sales on both measures. Management highlighted the acceleration in overall contract value growth, underscoring the importance of this metric to Gartner's operating performance.
Gartner's Insights Business Records Revenue Growth
Insights revenues increased 1.7% year over year, or 1.8% on a foreign-currency-neutral basis, to $1.29 billion. The segment remained Gartner's largest revenue contributor, accounting for the majority of consolidated revenues.
Gross contribution increased 2.9% year over year to $1 billion. The contribution margin was 77.6%, reflecting the segment's substantial contribution to Gartner's profitability.
The segment's contribution grew faster than revenues, indicating an improvement in operating efficiency. Insights remained central to the company's adjusted revenue growth following the divestiture of its Digital Markets operation.
IT's Conferences & Consulting Businesses Expand
Conferences revenues advanced 15.4% year over year to $86 million, representing 15.3% growth on a foreign-currency-neutral basis. The segment delivered the strongest revenue growth among Gartner's three businesses.
Conferences gross contribution increased 9.8% to $30 million, while its contribution margin was 34.9%. Contribution growth lagged revenue expansion, indicating pressure on segment profitability despite higher sales.
Consulting revenues increased 2.3% year over year, or 3% on a foreign-currency-neutral basis, to $126 million. Gross contribution climbed 21.3% to $43 million, with a contribution margin of 33.8%.
Consulting's contribution growth significantly exceeded its revenue increase, reflecting improved profitability. Together, Conferences and Consulting provided additional revenue growth beyond the larger Insights business.
Gartner's Operating Profitability Improves
Adjusted EBITDA, excluding the divested operation, increased 7.5% year over year to $364 million. On a foreign-currency-neutral basis, growth was 7.4%. The corresponding adjusted EBITDA margin was 24.2% compared with 23.1% a year earlier.
GAAP operating income increased to $281.1 million from $86.4 million in the prior-year quarter. Total costs and expenses declined to $1.22 billion from $1.44 billion.
The year-ago quarter included a $150-million goodwill impairment charge, which contributed to the substantial increase in reported operating income. Cost of services and product development declined to $433.2 million from $474.2 million, while selling, general and administrative expenses decreased to $746.8 million from $762.6 million.
Net income rose to $214.4 million from $35.4 million. GAAP earnings increased to $3.35 per share from 47 cents. Shares outstanding declined to 63.9 million from 75 million, supporting per-share earnings growth.
IT's Cash Generation & Share Repurchases
The operating cash flow declined 1.4% year over year to $294 million. Capital expenditure decreased to $19 million from $29 million, helping the free cash flow increase 2.2% to $275 million.
Gartner repurchased 0.9 million common shares for $138 million during the quarter. Management also highlighted $1.7 billion in share repurchases over the preceding four quarters, reflecting continued capital returns to shareholders.
The combination of a positive free cash flow and share repurchases supported Gartner's capital allocation strategy. The reduced share count also benefited adjusted earnings per share.
Gartner Raises Its 2026 Financial Outlook
Management raised revenue expectations to be at or above $6.41 billion compared with the preceding quarter’s $6.38 billion. The Zacks Consensus Estimate for revenue is pinned at $6.4 billion, standing close to the guidance.
Adjusted EPS is anticipated to be at or above $14.65 compared with the preceding quarter’s view of $14. The consensus estimate for the bottom line is pegged at $14.39, lower than the outlook. The free cash flow is expected to be at or above $1.24 billion, whereas it reported $1.19 billion in the preceding quarter.
Gartner carries a Zacks Rank #4 (Sell) at present.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Earnings Snapshot
ADP ADP reported impressive first-quarter fiscal 2027 results with earnings and revenues beating the Zacks Consensus Estimate.
ADP’s adjusted earnings of $2.83 per share beat the Zacks Consensus Estimate of $2.78 by 1.8%. The figure increased 14% from the year-ago quarter’s actual.
Revenues of $5.49 billion surpassed the consensus mark of $5.47 billion by 0.4% and rose 6% year over year.
Waste Management WM reported mixed third-quarter 2026 results, wherein adjusted earnings missed the Zacks Consensus Estimate, while revenues beat the same.
Adjusted earnings of $2.15 per share lagged the Zacks Consensus Estimate of $2.18 by 1.4%. The reported figure increased 8.6% from the year-ago quarter's $1.98.
Revenues rose 6.3% year over year to $6.85 billion, surpassing the consensus estimate of $6.8 billion by 0.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Gartner, Inc. (IT): Free Stock Analysis Report
Automatic Data Processing, Inc. (ADP): Free Stock Analysis Report
Waste Management, Inc. (WM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).