

Appian APPN is set to report its third-quarter 2026 results on Nov. 5.
For the third quarter of 2026, Appian’s total revenues are expected to be between $214.0 million and $218.0 million, representing a year-over-year increase of 14% to 17%. Non-GAAP earnings per share are expected to be between 31 and 35 cents.
The Zacks Consensus Estimate for third-quarter 2026 revenues is pegged at $215.75 billion, suggesting an increase of 15.37% from the year-ago quarter’s reported figure.
The consensus mark for third-quarter 2026 earnings is pegged at 32 cents per share, which has been unchanged over the past 30 days, implying earnings are expected to remain at prior-year levels.
Appian Corporation Price and EPS Surprise
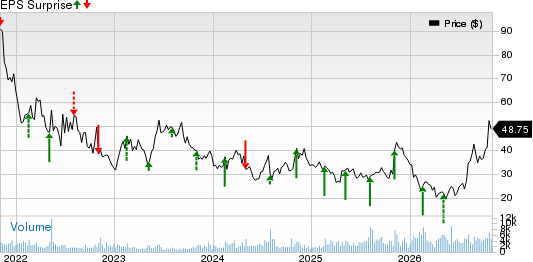
Appian Corporation price-eps-surprise | Appian Corporation Quote
Let’s see how things have shaped up prior to this announcement.
Factors Likely to Have Impacted APPN Q3 Performance
Appian’s third quarter 2026 performance is expected to have benefited from strong demand for its AI-powered process automation solutions, accelerating cloud subscription adoption and growing enterprise investments in digital transformation. Increasing adoption of AI orchestration, Data Fabric and process automation capabilities is likely to have supported cloud subscription revenue growth. Appian’s AI usage surged 20-fold year over year in the second quarter, while 85% of new customers purchased AI-enabled offerings. This momentum is expected to have continued in the to-be-reported quarter as well, supporting new customer acquisitions and expansion opportunities.
Appian’s cloud subscription business is expected to have benefited from strong customer retention and increased spending by existing customers. Cloud subscription revenues grew 23% year over year to $131.7 million in the second quarter, while cloud net ARR expansion reached 115%. Continued adoption of advanced AI subscription tiers and the Enterprise Growth Plan is likely to have supported recurring revenue growth. For the third quarter of 2026, Cloud subscriptions revenue is expected to be between $133.0 million and $135.0 million, representing year-over-year growth of 17% to 19%.
Appian is also expected to have benefited from increasing demand for legacy application modernization, particularly among large enterprises in highly regulated industries such as financial services, healthcare and insurance. Growing adoption of its DocCenter solution, AI-assisted application development capabilities and Enterprise Growth pricing plan is likely to have supported subscription revenue growth and customer expansion.
Strength in the U.S. public sector is expected to have been another positive. Increasing government investments in technology modernization and automation, alongside Appian’s strong federal customer relationships, are likely to have supported professional services revenues. The company expects professional services revenues to grow in the mid-teens in the third quarter of 2026.
However, Appian’s third-quarter 2026 performance is likely to have been hurt by unfavorable foreign exchange movements. This is expected to have weighed on reported revenue growth. Higher operating expenses stemming from accelerated sales hiring and continued growth investments are also likely to have pressured margins.
What Our Model Says
Per the Zacks model, the combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. But that’s not the exact case here.
Appian currently has an Earnings ESP of 0.00% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With Favorable Combination
Here are some stocks worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Analog Devices ADI has an Earnings ESP of +2.23% and a Zacks Rank #2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Analog Devices is slated to report fourth-quarter fiscal 2026 results on Nov. 24. Analog Devices shares have gained 52.3% year to date.
NVIDIA NVDA has an Earnings ESP of +3.46% and carries a Zacks Rank #2 at present.
NVIDIA is set to report third-quarter fiscal 2027 results on Nov. 17. NVIDIA shares have gained 8.4%in the year-to-date period.
Telos TLS has an Earnings ESP of +5.26% and carries a Zacks Rank #1 at present.
Telos is set to report third-quarter 2026 results on Nov. 9. Telos shares have risen 2.2% year-to-date.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Appian Corporation (APPN): Free Stock Analysis Report
Analog Devices, Inc. (ADI): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Telos Corporation (TLS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).