

Sally Beauty Holdings, Inc. SBH is likely to witness bottom-line growth when it reports fourth-quarter fiscal 2026 earnings on Nov. 10.
The consensus mark for earnings has remained unchanged over the past 30 days at 60 cents a share, though it suggests an increase of 9.1% from the year-ago period’s figure. SBH has a trailing four-quarter surprise of 6.4%, on average.
The Zacks Consensus Estimate for revenues is pegged at $948.3 million, indicating slight growth from the year-ago reported figure of $947.1 million.
Sally Beauty Holdings, Inc. Price, Consensus and EPS Surprise
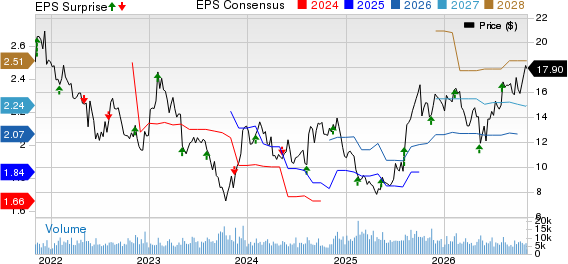
Sally Beauty Holdings, Inc. price-consensus-eps-surprise-chart | Sally Beauty Holdings, Inc. Quote
Factors Likely to Influence SBH’s Upcoming Results
Sally Beauty Holdings’ fourth-quarter performance is likely to have benefited from sustained demand for professional hair color, particularly in the United States and Canada. Customer acquisition initiatives, supported by targeted marketing and the revamped “Your Beauty Journey, No Salon Required” campaign, may have aided traffic. Growing fragrance demand and continued strength in hair color could have supported customer spending.
The company’s digital initiatives are likely to have provided support. Continued e-commerce momentum, enhanced mobile applications and improved customer engagement may have aided conversions and sales. The hair care assortment reset, expansion of men’s offerings and new brand introductions at Beauty Systems Group could have strengthened product appeal and customer engagement.
Sally Beauty’s ongoing Ignited store refreshes and planned Happy Beauty mall openings may have supported sales through broader assortments and enhanced shopping experiences. Continued benefits from the Fuel for Growth program, which management expects to deliver approximately $45 million in fiscal 2026 savings, are likely to have supported product margins and operating efficiency.
However, persistent hair care softness, cautious discretionary spending among salon professionals and increased promotional activity could have weighed on sales and margins. Softer consumer spending in Mexico may also have constrained growth.
Earnings Whispers for SBH
Our proven model doesn’t conclusively predict an earnings beat for Sally Beauty this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Sally Beauty currently carries a Zacks Rank #4 (Sell) and has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With the Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Dollar General Corporation DG currently has an Earnings ESP of +8.66% and a Zacks Rank of 2. The consensus estimate for quarterly revenues stands at $11.1 billion, which suggests 4.5% growth from the figure reported in the prior-year quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Dollar General’s upcoming quarter’s EPS is pegged at $1.40, which calls for a 9.4% increase from the year-ago period’s figure. DG delivered a trailing four-quarter earnings surprise of 19.1%, on average.
Ulta Beauty, Inc. ULTA currently has an Earnings ESP of +1.84% and a Zacks Rank #3. The consensus estimate for quarterly revenues is pegged at nearly $3 billion, which indicates 4.5% growth from the figure reported in the prior-year quarter.
The Zacks Consensus Estimate for Ulta Beauty’s upcoming quarter’s EPS is pegged at $5.60, which calls for almost 9% growth from the figure reported in the prior-year quarter. ULTA delivered a trailing four-quarter earnings surprise of 7.6%, on average.
The Kroger Co. KR currently has an Earnings ESP of +3.43% and a Zacks Rank of 3. The Zacks Consensus Estimate for KR’s upcoming quarter’s revenues is pegged at $34.6 billion, suggesting a 2.1% jump from the figure reported in the prior-year quarter.
The consensus estimate for Kroger’s upcoming quarter’s EPS is pegged at $1.16 per share, implying 10.5% growth from the year-ago quarter’s earnings of 36 cents. KR delivered a trailing four-quarter earnings surprise of 2.7%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sally Beauty Holdings, Inc. (SBH): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
The Kroger Co. (KR): Free Stock Analysis Report
Ulta Beauty Inc. (ULTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).