

Levi Strauss & Co.’s LEVI international business gained across Asia, Europe and Latin America in fiscal third-quarter 2026. Strong European wholesale performance, consumer engagement initiatives in Asia and gains across Latin American markets supported results. Management highlighted international expansion as part of its more diversified business, while improving Asian profitability and recovering European retail trends reinforced its confidence in the business.
International revenues increased 8% organically, led by Asia. The region generated $292.8 million in revenues, up 5% reported and 10% organically on the company’s rounded presentation. Management described this as Asia’s third consecutive quarter of double-digit organic growth. China advanced 13% organically, while Japan, India and Australia also contributed to regional strength.
Asia’s operating margin expanded 220 basis points to 14.2%, driven by improved gross margin. Direct-to-consumer (DTC) revenues increased 11% organically, supported by store performance, expansion and higher e-commerce demand. Management also highlighted the ROSE partnership and pop-up experiences as supporting regional momentum. Meanwhile, Latin America delivered 10% organic revenue growth, with strength across channels and gains in every market.
Europe’s revenues reached $442.1 million, rising 4% on a reported basis and 5% organically. Management reported double-digit organic wholesale growth, while the filing identified higher wholesale volumes as a sales driver. This helped offset weaker retail traffic during unusually warm weather. Regional operating margin improved 150 basis points to 22.8%, supported by stronger gross margin.
Management reported improving European retail trends and high-single-digit growth in spring/summer 2027 wholesale pre-bookings. Many of the company’s nearly 60 planned fourth-quarter net new system stores are earmarked for Asia. At the companywide level, management expects mid-single-digit DTC revenue growth in the fourth quarter and high-single-digit growth for fiscal 2026, supported by improving trends in both the United States and Europe.
LEVI’s Price Performance, Valuation & Estimates
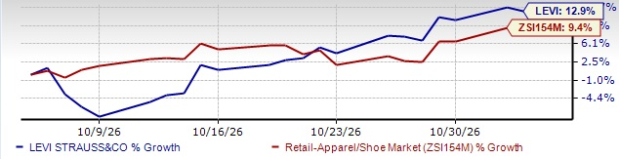
Shares of Levi Strauss have gained 12.9% over the past month compared with the industry’s 9.4% growth.
Image Source: Zacks Investment Research
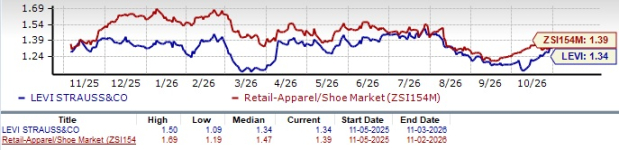
From a valuation standpoint, LEVI trades at a trailing price-to-sales ratio of 1.34, below the industry’s average of 1.39. It has a Value Score of A.
Image Source: Zacks Investment Research
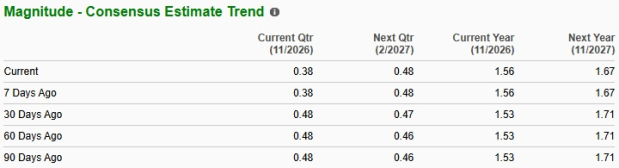
The Zacks Consensus Estimate for Levi Strauss’ fiscal 2026 earnings implies year-over-year growth of 16.4%, while the same for fiscal 2027 indicates an uptick of 6.9%. Estimates for fiscal 2026 and 2027 have been revised upward by 3 cents and downward by 4 cents, respectively, over the past 30 days.
Image Source: Zacks Investment Research
Levi Strauss currently carries a Zacks Rank #3 (Hold).
Key Picks
Abercrombie & Fitch Co. ANF operates as a specialty retailer of premium, high-quality casual apparel for men, women, and kids. The company carries a Zacks Rank #2 (Buy) at present. You can see the complete list of today’s Zacks #1 (Strong Buy) Rank stocks here.
The Zacks Consensus Estimate for Abercrombie & Fitch’s current fiscal-year earnings and sales suggests growth of 15.8% and 6.5%, respectively, from the year-ago actuals. ANF delivered a trailing four-quarter average earnings surprise of 13.6%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 12.6%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Levi Strauss & Co. (LEVI): Free Stock Analysis Report
Abercrombie & Fitch Company (ANF): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).