

McKesson Corporation MCK raised its fiscal 2027 earnings outlook following strong second-quarter performance, emphasizing sustained specialty pharmaceutical demand, operating efficiency and strategic expansion into higher-margin healthcare services.
Management's earnings call highlighted accelerating investments in oncology, biopharma services and community-based care. Executives also addressed acquisition economics, distribution growth sustainability and regulatory uncertainty during analyst discussions.
MCK Raises Full-Year Outlook on Operating Strength
McKesson raised its fiscal 2027 adjusted earnings per share guidance to $45.60-$46.40 from $44.20-$45.00, representing projected growth of 17%-19%.
Chief financial officer Kenny Cheung attributed the increase to broad-based operating strength and continued productivity gains. The outlook includes revenue growth of 6%-10% and operating profit growth of 12%-16%.
Second-quarter adjusted earnings of $11.68 per share exceeded the Zacks Consensus Estimate of $10.69. Revenues of $110.96 billion surpassed the consensus mark of $110.11 billion. Adjusted earnings increased 18% year over year, while revenues rose 8%.
McKesson Corporation Price, Consensus and EPS Surprise
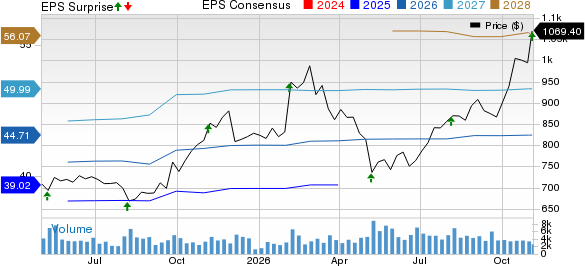
McKesson Corporation price-consensus-eps-surprise-chart | McKesson Corporation Quote
McKesson Sees Durable Pharmaceutical Demand
North American Pharmaceutical revenues increased 6% to $91.4 billion, supported by prescription volumes, specialty products and GLP-1 medications.
GLP-1 distribution revenues reached $16 billion, increasing 26% year over year and 8% sequentially. Adjusted operating profit rose 22% to $1 billion, reflecting specialty distribution strength and operating leverage.
During questioning from Evercore ISI, Cheung emphasized stable prescription trends, customer renewals and productivity improvements. He confirmed that the renewed CVS Health distribution agreement runs through June 2032. Management expects additional technology investments during the second half.
MCK Expands Higher-Margin Services Through Acquisition
McKesson completed its approximately $2.25 billion acquisition of Precision Medicine Group, strengthening oncology clinical research and biopharma commercialization capabilities.
Chief executive officer Brian Tyler explained that the acquisition complements existing clinical trial infrastructure and expands services across drug development and commercialization.
Cheung projected adjusted earnings accretion of $0.10-$0.20 per share in fiscal 2027, increasing to approximately $1.60-$1.80 by the end of year three.
During Barclays' questioning, Tyler characterized Precision Medicine Group's services as higher-margin offerings relative to traditional distribution activities.
McKesson Targets Home-Based Specialty Care
McKesson's proposed $1.4 billion investment for a 49% minority interest in Option Care Health extends its strategy into home and alternate-site infusion services.
Tyler emphasized growing opportunities to administer complex specialty therapies closer to patients. The partnership would combine McKesson's specialty expertise with Clayton, Dubilier & Rice's operating capabilities.
Management clarified during Jefferies' questioning that Option Care would remain independently operated under majority ownership by CD&R. The investment will use equity-method accounting, with no contribution incorporated into current guidance.
MCK Highlights Technology Growth and MedSurg Pressure
Prescription Technology Solutions revenues increased 10% to $1.5 billion, while adjusted operating profit advanced 18% to $307 million.
Cheung cited expanding access and affordability services, including prior authorization solutions. Management added 67 programs across 58 brands during the quarter.
However, Medical-Surgical Solutions adjusted operating profit declined 10% to $225 million despite 5% revenue growth. Unfavorable ambulatory product mix weighed on profitability.
Management expects fiscal 2027 MedSurg operating profit to range from a 4% decline to flat, reflecting continued operational challenges.
McKesson Addresses Regulatory Risks and Capital Deployment
During JPMorgan's questioning about potential 340B reimbursement changes, Tyler acknowledged uncertainty surrounding customer behavior and implementation.
Cheung maintained that McKesson's distribution services retain their value and said management does not currently anticipate a material financial impact.
The company generated $2.9 billion in second-quarter free cash flow. Cheung reaffirmed approximately $5 billion in planned fiscal 2027 share repurchases, alongside projected annual free cash flow of $4.5 billion-$4.9 billion.
MCK Maintains Focus on Long-Term Execution
Management's commentary emphasized specialty distribution, clinical research expansion and technology-enabled services as central growth priorities.
Tyler highlighted disciplined execution and complementary acquisitions, while Cheung reinforced confidence in operating leverage and capital allocation. Regulatory developments and MedSurg profitability remain areas requiring attention.
What Zacks Rank and Style Scores Indicate for MCK
McKesson currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term earnings-estimate revision outlook. Its Growth Score of A and Value Score of B reflect favorable growth and valuation characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
However, its Momentum Score of D indicates weaker price-momentum characteristics. The VGM Score of A reflects attractive combined value, growth and momentum characteristics despite that weakness.
These scores provide complementary investment signals rather than guaranteed performance outcomes. The Zacks Rank can change as analysts revise earnings estimates following the latest quarterly results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
McKesson Corporation (MCK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).