

ConocoPhillips COP reported adjusted earnings of $3.27 per share for the third quarter of 2026, up 103.1% from $1.61 a year earlier. The bottom line beat the Zacks Consensus Estimate of $3.06 per share by 6.9%.
Total revenues and other income of $20.06 billion increased 29.2% from $15.52 billion a year ago. The top line surpassed the Zacks Consensus Estimate of $18.38 billion by 9.1%.
Stronger quarterly results were driven by higher commodity prices. The positives were slightly offset by lower production volumes.
Total production was 2,302 thousand barrels of oil equivalent per day (Mboe/d), down 4% year over year.
ConocoPhillips Price, Consensus and EPS Surprise
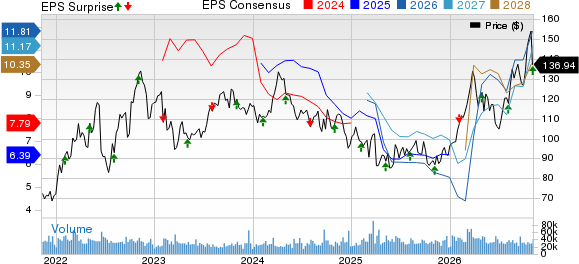
ConocoPhillips price-consensus-eps-surprise-chart | ConocoPhillips Quote
COP's Revenue Growth Reflects Higher Realized Prices
Sales and other operating revenues increased to $19.44 billion from $15.03 billion in the prior-year quarter. Equity in earnings of affiliates totaled $448 million, while other income contributed $120 million. Gains on dispositions amounted to $54 million.
ConocoPhillips' average realized price reached $61.40 per barrel of oil equivalent (Boe), 32% above the year-ago level of $46.44 per Boe. Higher commodity realizations more than offset the impact of lower production and supported stronger quarterly profitability.
ConocoPhillips Reports Higher Adjusted Earnings
The company reported net income of $4 billion compared with $1.73 billion a year earlier. Excluding special items, adjusted earnings totaled $3.92 billion, up from $2.01 billion.
Third-quarter special items increased reported earnings by $83 million after tax. These primarily included the reversal of a tax reserve, partially offset by pending claims and settlements, transaction-related expenses and an interest-rate hedge adjustment.
COP's Lower 48 Operations Lead Segment Growth
Adjusted earnings from the Lower 48 segment increased to $2.49 billion from $1.31 billion in the prior-year quarter. The segment remained the largest contributor to consolidated adjusted earnings, benefiting from higher commodity prices and continued operational efficiencies.
Alaska adjusted earnings increased to $423 million from $156 million. Canada generated $187 million compared with $206 million a year ago. Europe, the Middle East and North Africa contributed $362 million, up from $328 million, while Asia Pacific adjusted earnings rose to $528 million from $309 million.
ConocoPhillips Details Production Performance
Total company production declined 97 MBoe/d year over year. Adjusting for closed acquisitions and dispositions, production decreased 40 MBoe/d, or 2%. Organic growth in the Lower 48 was more than offset by the impact of the Middle East conflict on Qatar and higher Surmont royalties.
Lower 48 production reached 1,517 MBoe/d. The Delaware Basin contributed 757 MBoe/d, followed by Eagle Ford at 369 MBoe/d, the Midland Basin at 197 MBoe/d and the Bakken at 191 MBoe/d. Management highlighted record Permian completion efficiency, with pumping hours increasing 15% from the 2025 average.
COP Faces Higher Costs Despite Operating Efficiencies
Total costs and expenses increased 11.8% to $14.08 billion from $12.59 billion in the prior-year quarter. Purchased commodity costs rose to $7.42 billion from $5.86 billion, reflecting the stronger commodity-price environment.
Production and operating expenses declined 7.3% to $2.44 billion, while selling, general and administrative expenses decreased 19.2% to $219 million. However, depreciation, depletion and amortization increased to $3.01 billion, and taxes other than income taxes rose to $648 million.
ConocoPhillips Strengthens Cash Flow & Shareholder Returns
Cash provided by operating activities totaled $7.20 billion. Excluding working-capital changes, cash from operations reached $7.17 billion. The company funded $3.13 billion of capital expenditures and investments, generating approximately $4.04 billion in free cash flow.
As of Sept. 30, ConocoPhillips held $7.77 billion in cash and cash equivalents and $2.16 billion in short-term investments. Shareholder distributions totaled $3.4 billion, comprising $2.4 billion in share repurchases and $1 billion in ordinary dividends.
The company increased its quarterly ordinary dividend by 11% to 93 cents per share, payable Dec. 1, 2026.
COP Maintains 2026 Guidance & Outlines 2027 Priorities
ConocoPhillips expects fourth-quarter 2026 production between 2.32 and 2.36 million barrels of oil equivalent per day. Full-year capital expenditure and adjusted operating cost guidance remain unchanged.
Management expects 2027 capital spending to decline modestly year over year while underlying production grows at a low-single-digit rate. Lower unit operating costs and continued efficiency improvements remain priorities.
The company remains on track to return 45% of cash from operations to shareholders in 2026. Its Willow project is progressing toward first oil in early 2029, supporting management's targeted $7 billion free cash flow improvement by that year.
COP’s Zacks Rank & Other Key Picks
ConocoPhillips currently sports a Zacks Rank #1 (Strong Buy).
Some other top-ranked stocks from the energy sector are Range Resources Corporation RRC, Equinor ASA EQNR and Eni S.p.A. E. RRC, EQNR and E currently carry a Zacks Rank #2 (Buy) each. You can see the complete list of today’s Zacks Rank #1 stocks here.
Range Resources reported third-quarter 2026 adjusted earnings of 81 cents per share, surpassing the Zacks Consensus Estimate of 70 cents per share.
As of Sept. 30, 2026, RRC had total debt of $780.92 million and cash and cash equivalents of $12,000.
Equinor reported third-quarter 2026 adjusted earnings of $1.20 per share, missing the Zacks Consensus Estimate of $1.38 per share.
As of Sept. 30, 2026, EQNR had $6.30 billion of cash and cash equivalents.
Eni reported third-quarter 2026 adjusted earnings of $2.13 per share, surpassing the Zacks Consensus Estimate of $1.92 per share.
As of Sept. 30, 2026, E had total debt of €34.39 billion and cash and cash equivalents of €11.77 billion.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ConocoPhillips (COP): Free Stock Analysis Report
Eni SpA (E): Free Stock Analysis Report
Range Resources Corporation (RRC): Free Stock Analysis Report
Equinor ASA (EQNR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).