

Accelerant Holdings ARX is set to report its third-quarter 2026 results on Nov. 12, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at 20 cents per shareon revenues of $270.94 million.
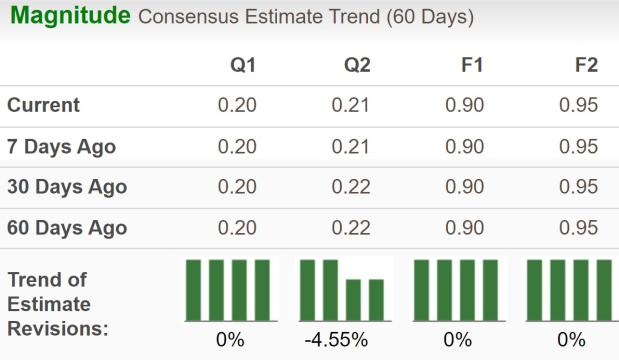
The third-quarter earnings estimate witnessed no movement over the past 60 days. The bottom-line projection indicates a year-over-year decline of 47.4%. Also, the Zacks Consensus Estimate for quarterly revenues suggests a year-over-year increase of 1.3%.
The company’s pending take-private deal with Thoma Bravo is on track to close in the first half of next year. The 40-day "go-shop" period expired on Sept. 22, 2026.
For 2026, the Zacks Consensus Estimate for Accelerant Holdings’ revenues is pegged at $1.16 billion, implying a rise of 26.7% year over year. However, the consensus mark for 2026 EPS is pegged at 90 cents, implying a 4.3% year-over-year decline.
Accelerant Holdings beat earnings estimates in each of the past four quarters, with the average surprise being 55.7%. This is depicted in the figure below.
Accelerant Holdings Price and EPS Surprise
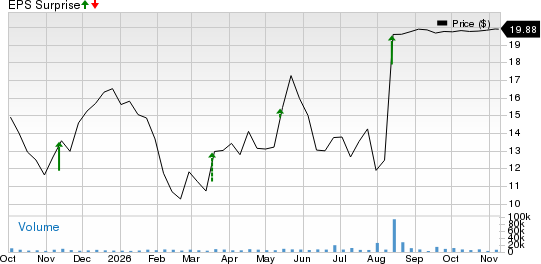
Accelerant Holdings price-eps-surprise | Accelerant Holdings Quote
Q3 Earnings Whispers for ARX
However, our proven model does not conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That’s not the case here.
ARX has an Earnings ESP of 0.00% and a Zacks Rank #4 (Sell). You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
You can see the complete list of today’s Zacks #1 Rank stocks here.
What’s Shaping ARX’s Q3 Results?
The Zacks Consensus Estimate for third-quarter net earned premiums indicates 32.2% year-over-year growth. Also, the consensus mark for net investment income suggests a 23.5% surge from the year-ago period, while direct commission income is likely to have increased 84.3%. These are likely to have supported top-line growth in the to-be-reported quarter.
However, net revenue retention is expected to have declined to 116.3% in the third quarter, from 135% a year ago.
The consensus estimate for adjusted EBITDA from Exchange Services indicates around a 27% increase from the year-ago quarter. But the same from the MGA Operations and Underwriting segments indicates 52% and 79.9% declines in the third quarter of 2026.
The Zacks Consensus Estimate for the total number of members in the third quarter is pegged at more than 325 million, indicating an increase of 22.8% year over year, backed by growth in independent, mission and owned members.
How Did Other Stock Fare This Quarter?
Several insurance companies, including Marsh & McLennan Companies, Inc. MRSH, The Hartford Insurance Group, Inc. HIG and RenaissanceRe Holdings Ltd. RNR, have already reported their financial results for the September quarter of 2026. Here’s how they performed:
Marsh reported third-quarter 2026 adjusted earnings per share of $2.03, which surpassed the Zacks Consensus Estimate by 3.6% and advanced 9.7% year over year. The results benefited from solid revenue growth across Risk and Insurance Services and Consulting. However, Marsh’s higher operating expenses partially offset the positives.
Hartford Insurance delivered third-quarter 2026 core earnings per share of $3.50, beating the Zacks Consensus Estimate by 11.1%. However, the bottom line declined 2.5% year over year. The results benefited from HIG’s higher investment income and premium growth in Business Insurance. However, higher catastrophe losses and weaker Employee Benefits profitability partly offset the upside.
RenaissanceRe reported third-quarter 2026 operating income of $12.71 per share, which surpassed the Zacks Consensus Estimate by 12.9%. Yet, the bottom line fell from $15.62 per share a year ago. The quarterly earnings benefited from lower operational expenses and higher net investment income. However, the upside was partly offset by lower net premiums earned, weaker underwriting results in RNR’s Casualty & Specialty segment and lower fee income.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Accelerant Holdings (ARX): Free Stock Analysis Report
The Hartford Insurance Group, Inc. (HIG): Free Stock Analysis Report
RenaissanceRe Holdings Ltd. (RNR): Free Stock Analysis Report
Marsh (MRSH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).