

Post Holdings, Inc.’s POST Foodservice business could benefit from improving industry supply-demand dynamics and normalization in egg pricing, potentially supporting earnings growth in fiscal 2027. In the third quarter of fiscal 2026, management highlighted stronger-than-anticipated Foodservice performance, with profits remaining strong despite negative price realization and the continued lapping of highly pathogenic avian influenza (HPAI)-related pricing benefits. Management estimated the business's normalized earnings run rate at approximately $500 million, reflecting its underlying earning power under balanced operating conditions.
This figure represents management's estimate of Foodservice's underlying earning power under normalized circumstances rather than its current quarterly earnings level. Management identified three factors underlying normalization: balanced supply and demand, normalized inventories and the relationship between open-market egg prices and grain-based egg pricing.
Management indicated that internal supply-demand balance and inventories had returned to desired levels, leaving the mismatch between market and grain-based egg pricing as the remaining normalization factor. The imbalance reflects industry oversupply following HPAI-related disruptions last year. Management expects the oversupply to correct over time, noting that producers are unlikely to sustain operations when chicken feed costs exceed realizations in the open market. Against this backdrop, management believes Foodservice can fully grow its earnings from the estimated $500 million normalized run rate in fiscal 2027.
Overall, Foodservice's normalized earnings base provides a useful benchmark for assessing its underlying performance as industry conditions adjust. Management's confidence in growing earnings from this base in fiscal 2027 reinforces the potential for improved earnings performance as the remaining pricing imbalance resolves.
The Zacks Rundown for POST
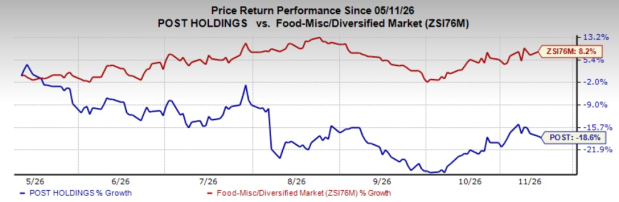
The company’s shares have lost 18.6% in the past six months against the industry’s 8.2% growth.
Image Source: Zacks Investment Research
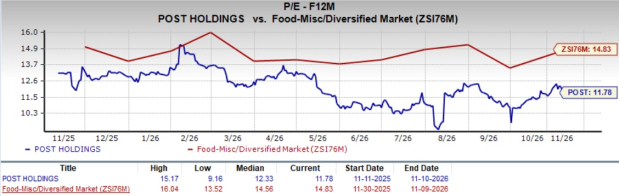
From a valuation standpoint, POST trades at a forward price-to-earnings ratio of 11.78, lower than the industry’s average of 14.83. POST currently carries a Zacks Rank #3 (Hold).
Image Source: Zacks Investment Research
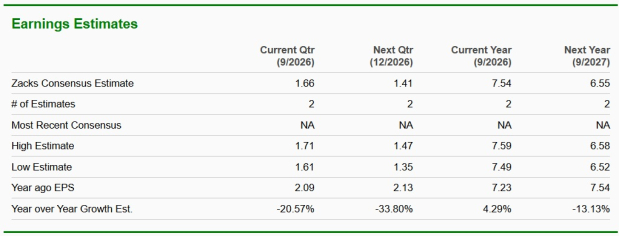
The Zacks Consensus Estimate for POST’s current fiscal year earnings implies a year-over-year increase of 4.3%, and the same for next fiscal year earnings implies a decline of 13.1%.
Image Source: Zacks Investment Research
Stocks to Consider
Some better-ranked stocks have been discussed below:
Lamb Weston Holdings, Inc. LW engages in the production, distribution and marketing of frozen potato products in the United States, Canada, Mexico and internationally. LW currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Lamb Weston's current fiscal-year sales indicates a decline of 0.5%, and the same for earnings indicates growth of 7.6% from the prior-year levels. Lamb Weston delivered a trailing four-quarter earnings surprise of 22.1%, on average.
Ryohin Keikaku Co., Ltd. RYKKY engages in the retail of household goods and food items in Japan and internationally. RYKKY currently carries a Zacks Rank #2 (Buy).
The Zacks Consensus Estimate for RYKKY's current fiscal-year sales implies growth of 3.9%, and the same for earnings implies a decline of 2.1% from the year-ago actuals.
The J. M. Smucker Company SJM operates as a health and wellness company that provides habit-based and coach-guided lifestyle solutions to address obesity and support a healthy life in the United States. SJM currently carries a Zacks Rank of 2.
The Zacks Consensus Estimate for SJM's current fiscal-year sales indicates a decline of 1.4%, and the same for earnings indicates growth of 17.1% from the prior-year levels. SJM delivered a trailing four-quarter earnings surprise of 13.8% on average.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Post Holdings, Inc. (POST): Free Stock Analysis Report
The J. M. Smucker Company (SJM): Free Stock Analysis Report
Lamb Weston (LW): Free Stock Analysis Report
Ryohin Keikaku Co. Ltd. (RYKKY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).