

Shares of United Bancorp, Inc. UBCP have declined 2% since the company reported its earnings for the quarter ended Sept. 30, 2026. This compares with the S&P 500 index’s 1.7% decline over the same period. Over the past month, the stock has lost 1.8% compared with the S&P 500’s 4.1% decline.
United Bancorp reported third-quarter 2026 earnings per share of 25 cents, which decreased 26.5% from 34 cents recorded in the prior-year quarter.
Total revenues, comprising net interest income and noninterest income, were $9.3 million, up 15.2% from $8.1 million in the year-ago quarter.
Net income declined 27.4% to $1.4 million from $1.9 million. The earnings deterioration primarily resulted from a substantial provision for credit losses associated with a single commercial borrowing relationship.
United Bancorp, Inc. Price, Consensus and EPS Surprise
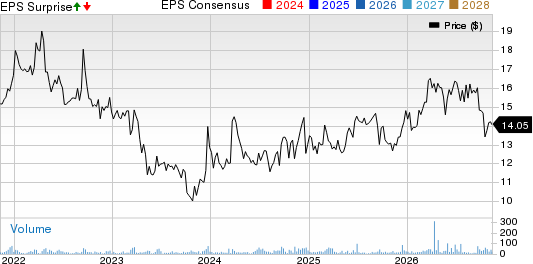
United Bancorp, Inc. price-consensus-eps-surprise-chart | United Bancorp, Inc. Quote
UBCP's Net Interest Income and Other Key Metrics
Net interest income increased 4% year over year to $7 million from $6.7 million. Total interest income edged up 0.4% to $10.7 million, while interest expense declined 5.8% to $3.7 million.
Noninterest income surged 70.9% to $2.3 million from $1.4 million. This included a $0.6 million gain from the sale of available-for-sale securities. Gains on loan sales more than doubled to $0.2 million, while service charges on deposit accounts increased 3.5%.
Noninterest expenses declined 2.8% to $5.8 million. Pre-provision net revenue (PPNR), a non-GAAP measure, increased 66.5% to $3.5 million from $2.1 million, reflecting stronger underlying operating performance, including securities gains.
UBCP's Balance Sheet and Credit Quality
As of Sept. 30, 2026, total assets reached $899.3 million compared with $866.8 million a year earlier. Gross loans increased 1.5% to $503.9 million.
Total deposits grew 12% year over year to $722.5 million. Lower-cost deposits, comprising noninterest-bearing demand, interest-bearing demand and savings accounts, increased 12.2% to $511.9 million, representing 70.9% of total deposits.
Cash and balances due from the Federal Reserve Bank increased to $70.3 million from $45.6 million. Shareholders' equity declined to $52.1 million from $66.5 million, reflecting a substantial increase in accumulated other comprehensive losses.
Nonaccrual loans and loans past due at least 30 days totaled $2.9 million, down $0.3 million year over year. The allowance for credit losses decreased to $3.8 million from $4.3 million.
The company paid a quarterly cash dividend of 19.75 cents per share, up 5.3% year over year.
Factors Influencing UBCP's Quarterly Performance
The principal earnings headwind was a $3 million charge-off involving a single commercial borrower. Consequently, the provision for credit losses surged to $2.4 million from $0.2 million in the prior-year quarter.
Despite this setback, improved deposit funding costs supported profitability. The company benefited from lower-cost deposit growth, downward repricing of existing deposits and the maturity of a $20 million Federal Home Loan Bank advance earlier in 2026.
UBCP's Management Commentary and Outlook
CFO Randall M. Greenwood attributed the earnings decline primarily to the isolated commercial credit event, emphasizing the improvement in underlying profitability.
CEO Scott A. Everson highlighted the company's infrastructure investments, including Unified Mortgage, Treasury Management and digital banking capabilities. Management also noted that the Wheeling, WV, banking center exceeded initial performance expectations and contributed to deposit growth.
Looking ahead, management expects net interest income and net interest margin to continue improving through the remainder of 2026, supported by stronger loan demand and the redeployment of overnight funds into higher-yielding loans.
The company anticipates beginning the rollout of its Unified Care Center and related digital banking technologies by the end of the first quarter of 2027.
Management expects infrastructure investments to generate stronger returns over the next 12-24 months, although associated expenditures could continue weighing on near-term earnings.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
United Bancorp, Inc. (UBCP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).