

MP Materials MP reported a 176% year-over-year surge in third-quarter 2026 revenues to $147.7 million, taking total revenues for the first nine months of 2026 to $346.8 million. Compared with the prior-year period, this represents a 102% increase.
The Materials segment was the primary growth driver. Segment revenues soared 322% year over year to $133.5 million in the third quarter. For the first nine months of 2026, revenues increased 141% to $301.3 million.
The segment benefited from stronger market prices and higher NdPr sales volumes as MP Materials continued to ramp up production of separated rare earth products. Revenues from the sales of NdPr oxide and metal totaled $100.96 million in the third quarter (up 227% year over year) and $266.5 million in the nine months ended Sept. 30, 2026 (up 232% year over year).
In September 2026, the company had entered into a one-time sale agreement with a U.S. aerospace and defense customer, under which it sold $31.6 million of a mixed heavy rare earth product containing samarium, europium, gadolinium and other heavy rare earths (SEG+) during the third quarter of 2026. This also contributed to the Materials segment’s revenues in the third quarter.
The company reported no rare earth oxide (REO) concentrate sales this year, following its decision to discontinue sales to China in July 2025. Instead, MP Materials is processing the concentrate into separated rare earth products or stockpiling it for future use. The Materials segment’s revenues for the nine-month period ended Sept. 30, 2025 included $41.99 million in rare earth concentrate sales. Despite the absence of this revenue stream, the Materials segment delivered 141% growth during the first nine months of 2026, highlighting the contribution from higher-value separated products and increased NdPr sales volumes.
The Magnetics segment’s revenues declined 15% year over year to $18.6 million in the third quarter, reflecting slightly lower magnetic precursor product sales as the company advanced the start-up of magnet production at its Independence Facility. However, the segment’s revenues increased 20% year over year to $56.2 million in the first nine months of 2026 reflecting higher production levels of magnetic precursor products at the Independence Facility year over year.
MP Materials also benefited from $8.1 million in income related to a price protection agreement (PPA) with the Department of War (DoW) in the third quarter. PPA-related income totaled approximately $68 million during the first nine months of 2026.
Looking ahead, several initiatives could support MP Material’s future revenue growth. The company is advancing key growth initiatives, such as expanding operations at Independence and breaking ground on the 10X magnetics facility, its second domestic rare earth magnet manufacturing facility. Meanwhile, scaled heavy rare earth separation commissioning activities are set to begin soon at Mountain Pass.
Among industry peers, Lynas Rare Earths LYSDY also delivered strong revenue growth. First-quarter fiscal 2027 revenues, for the quarter ended Sept. 30, 2026, jumped 55% year over year to AUD 310.1 million ($210.6 million), marking the company’s highest quarterly revenues since the fourth quarter of fiscal 2022. Growth was driven by higher NdPr prices and increased sales volumes of total REO products.
MP’s Price Performance, Valuation & Estimates
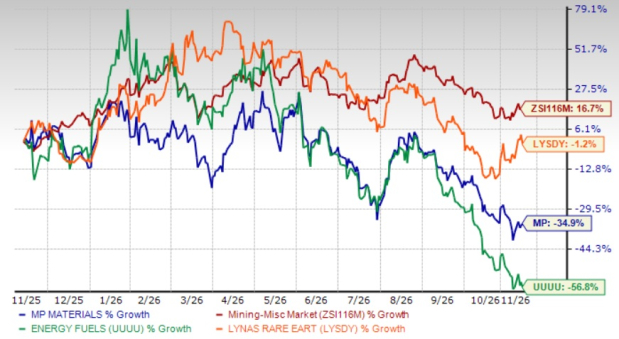
MP Materials’ shares have declined 34.9% in a year against the industry’s 16.7% growth. Peers Energy Fuels UUUU and Lynas Rare Earths have declined 56.8% and 1.2%, respectively.
Image Source: Zacks Investment Research
MP is trading at a forward 12-month price/sales multiple of 9.50X, a significant premium to the industry’s 1.46X.
Image Source: Zacks Investment Research
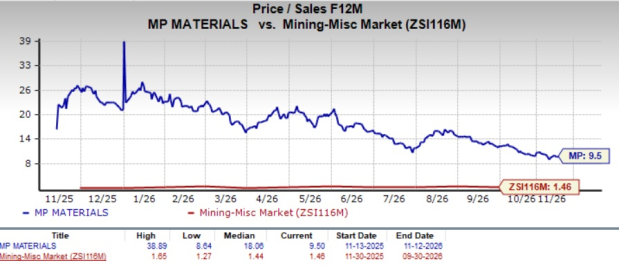
Energy Fuels trades at an even steeper multiple of 11.73X, while Lynas Rare Earths appears comparatively cheaper at 7.76X.
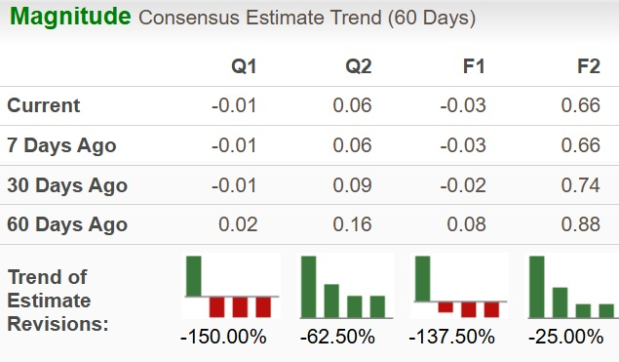
The Zacks Consensus Estimate for MP Materials’ 2026 earnings is currently pegged at a loss of 3 cents per share, narrower than the loss of 24 cents reported in 2025. For 2026, earnings expected to reach 66 cents per share.
Image Source: Zacks Investment Research
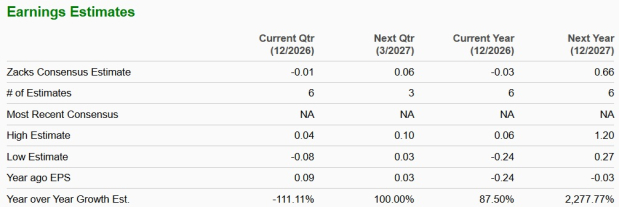
The estimate for both 2026 and 2027 has, however, moved down in the past 60 days, as shown in the chart below.
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MP Materials Corp. (MP): Free Stock Analysis Report
Energy Fuels Inc (UUUU): Free Stock Analysis Report
Lynas Rare Earths Limited - Sponsored ADR (LYSDY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).