

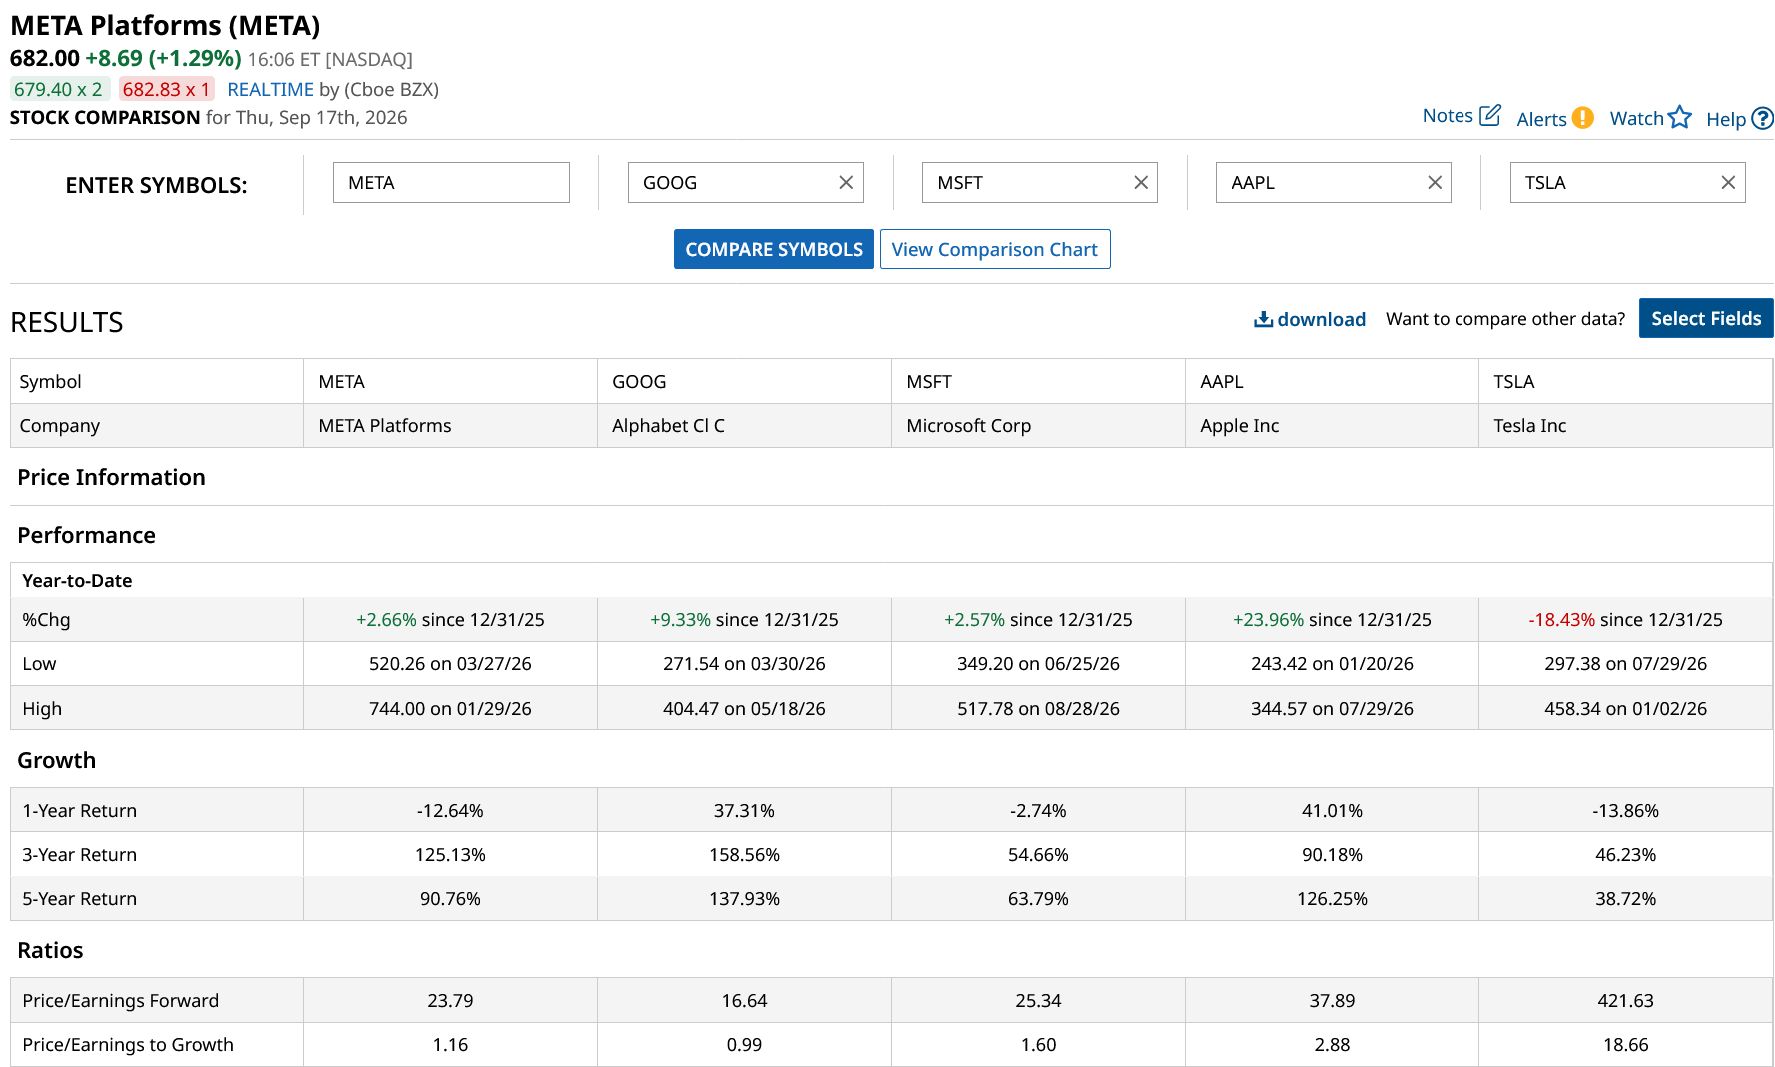
The Magnificent 7 stocks are having a tough ride in 2026, and only Apple (AAPL) is outperforming the Nasdaq 100 Index ($IUXX). Digging deeper, Nvidia (NVDA) is the only other constituent that is up in double digits. Despite its recent rally, Tesla (TSLA) is still down over 18% year-to-date (YTD) and is the worst-performing Mag 7 stock.
The price action is not difficult to explain. Investors are now getting increasingly wary of tech companies’ ever-rising capex to build artificial intelligence (AI) infrastructure. Apple was an outlier in the AI buildout race and is now sitting pretty as investors realize that waiting it out wasn’t exactly a bad move on the iPhone maker’s part.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Magnificent 7 Stocks Are Underperforming Nasdaq 100 in 2026
Nvidia’s price action can be puzzling, though. The company is the ultimate beneficiary of AI capex, as much of the spending is landing in its coffers given how central its chips are to the AI ecosystem. It continues to grow at a breathtaking pace despite the ever-rising base, and guidance for the current quarter calls for revenues above $100 billion, a first for the company. The Jensen Huang-led company has been trying to allay fears of an imminent slowdown and guided for a 70% increase in the next fiscal year’s revenues, with the management noting that sales would double if not for supply constraints. In an era where companies struggle to even guide for the next quarter, Nvidia went out of its way and provided guidance for the next fiscal year, which was a first in its history.
Nvidia Stock Has Been Subdued Despite Stellar Financial Performance
However, as I noted in my previous article, rising competition from other chip companies, hyperscalers aggressively building custom silicon, and Nvidia’s financing deal spree (circular deals, I would say, a categorization Huang has been dismissive of) have put a lid on NVDA stock this year. Otherwise, a stock trading at a forward price-to-earnings (P/E) multiple of under 24x and delivering such stellar topline and bottomline growth would have been a screaming buy.
Meta Platforms Has Turned Positive For 2026
Meta is an outlier among hyperscalers that have sprawling cloud businesses. Thanks to AI, Amazon (AMZN), Microsoft (MSFT), and Alphabet (GOOG) (GOOGL), the top three U.S. cloud companies, in that order, are reporting strong growth in cloud revenues. While Meta’s core digital advertising business is doing remarkably well, markets have given more weight to cloud revenue growth to gauge the efficiency of the AI capex.
Meanwhile, Meta has quietly turned positive for the year. While the YTD gain is in the low single digits, it is up over 25% from its August lows. AI monetization and teen safety concerns were the two main factors weighing on META stock in recent months, and there has been some progress on both of late.
Last month, Meta reached a settlement with almost every U.S. state over teen safety issues, agreeing to pay up to $18 billion and add stronger safety measures on its platforms. It was the largest settlement in U.S. history, excluding the tobacco settlements of the 1990s.
On the AI monetization front, Meta debuted its Muse AI agent earlier this month. Along with the free tier, Meta also announced a subscription for Muse costing up to $100 per month. Reports of Meta deploying its MTIA 450 custom AI chip in data centers in the first half of 2027 also lifted sentiment.
META Stock Forecast
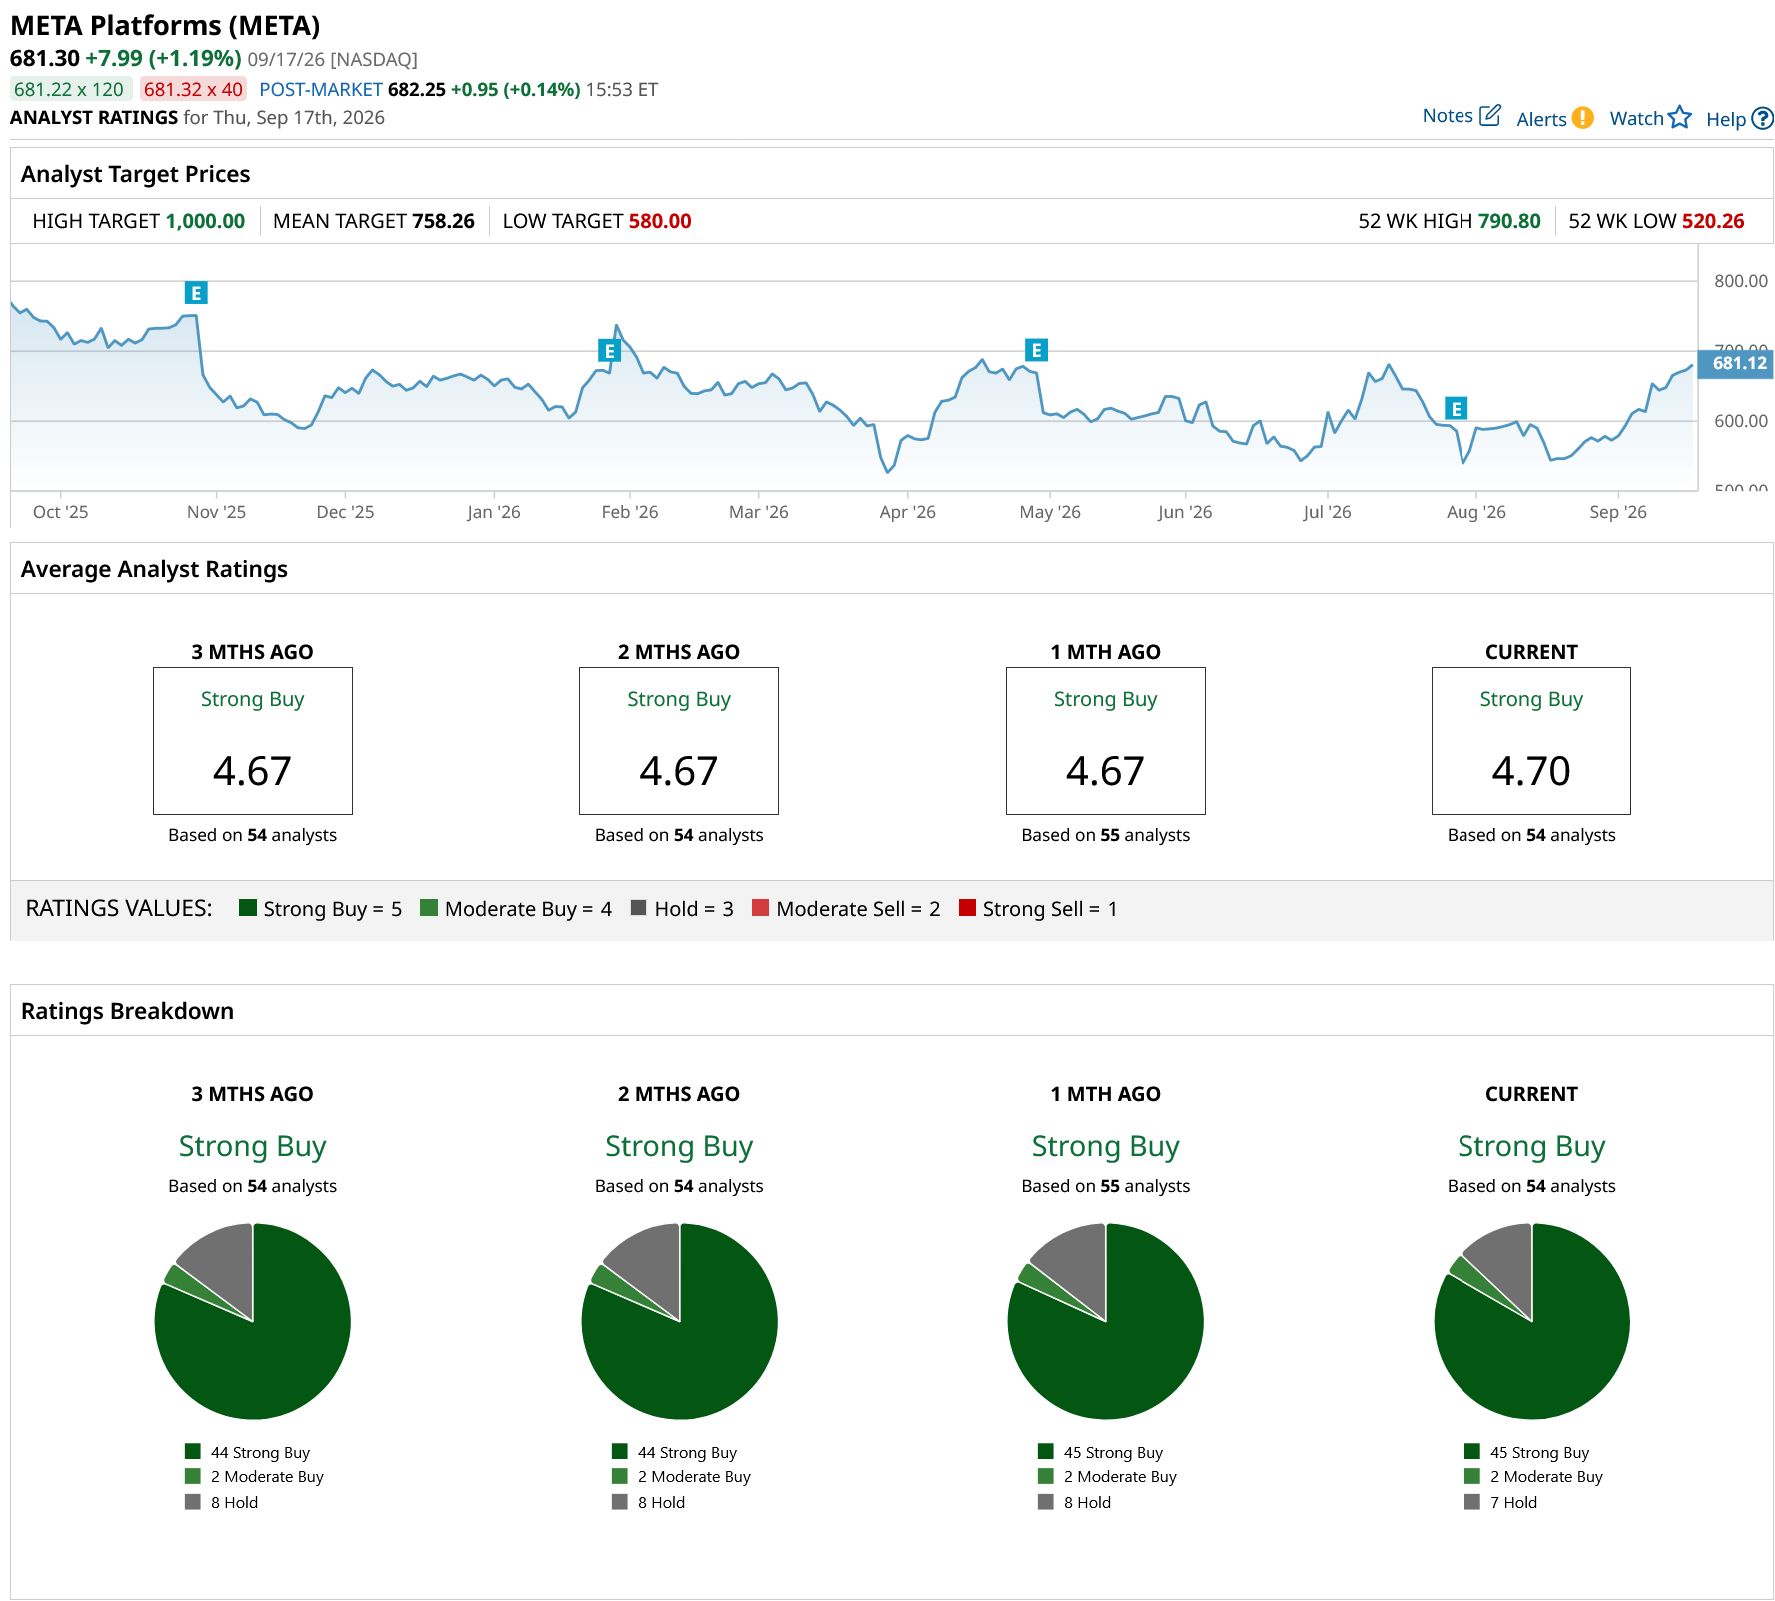
Analyst sentiment towards META stock is also turning around. Earlier this month, JPMorgan upgraded Meta from a “Neutral” to “Overweight” and raised its target price from $640 to $820 as analyst Doug Anmuth sees upside from AI monetization. Wedbush also raised Meta’s target price from $595 to $650 after Muse’s release. Goldman Sachs maintained its $725 target, and the brokerage sees “a clearer catalyst path for the shares going forward” following Muse's launch and settlement with states.
META stock has a consensus rating of “Strong Buy” from the 55 analysts polled by Barchart, and its mean target price of $758.26 is nearly 13% higher than current levels.
 www.barchart.com
Can META Rise Any Further in 2026?
While a flurry of positive developments has helped trigger a rally in Meta over the last month, I am circumspect about the sustainability of the rally in the near term. I would like to see the AI monetization efforts flow into Meta’s earnings, as getting users to pay for subscriptions might not be a cakewalk. Overall, while I expect Meta to rise from these levels by the end of the year, for now I believe the current rally has run its course.
On the date of publication, Mohit Oberoi had a position in: META , AMZN , MSFT , GOOG , TSLA . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
SpaceX CFO’s Confidence in Its $100 Billion Goal Grows. Investors Need to Pay Attention Before September 21. Michael Burry Says OpenAI and Anthropic’s AI Slowdown Push Is ‘Self-Serving.’ Who’s Right? Mag 7 Laggard Meta Has Quietly Turned Positive for 2026. What Comes Next. Robinhood’s CEO Says Prediction Markets Are Starting a ‘Supercycle That Could Drive Trillions In Annual Volume’ After 12 Billion Contracts Traded in 2025