

Philip Morris International (PM) just gave income investors another reason to pay attention. The tobacco company announced last week that it raised its quarterly dividend by 8.8%, from $1.47 to $1.60 per share. That brings the annual payout to $6.40 per share. Shareholders on record by Oct. 2 will receive the payment on Oct. 26, 2026.
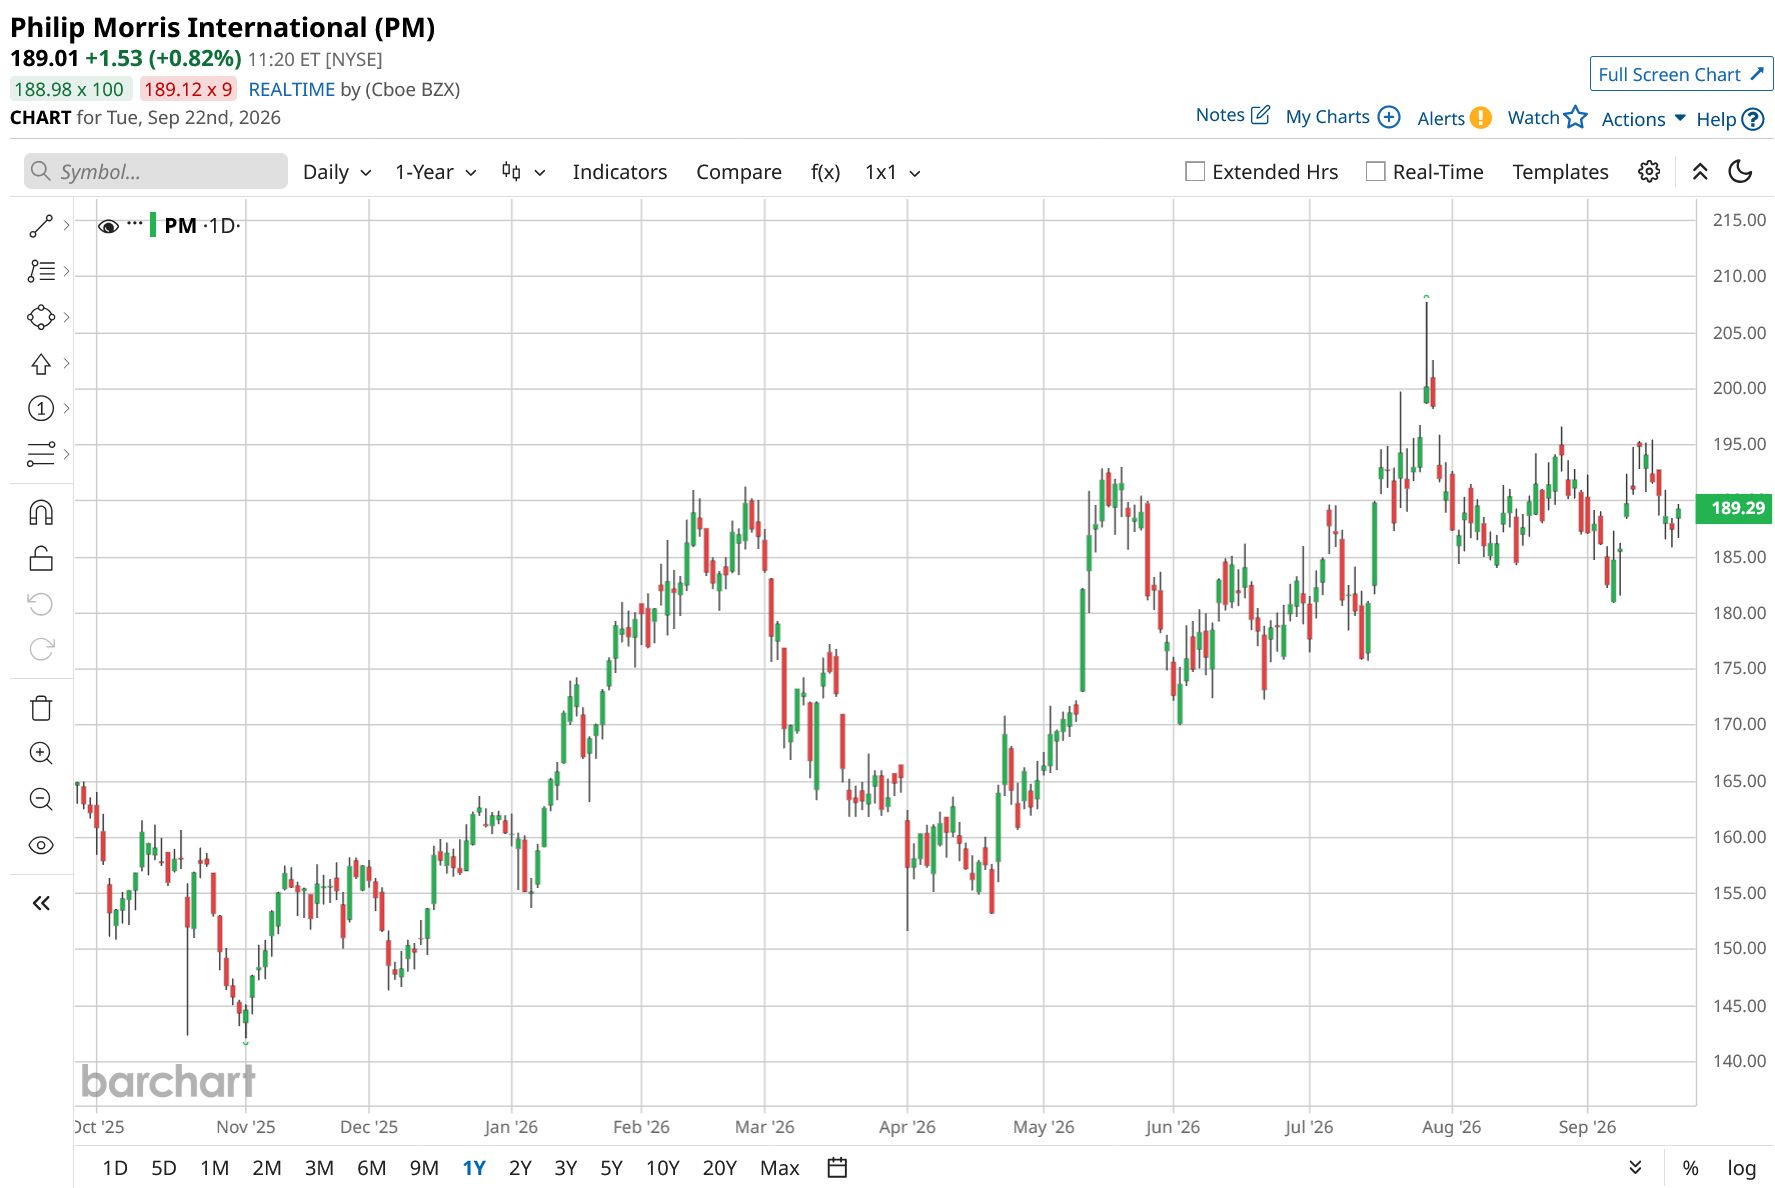
The stock has also been doing well. PM stock is up 17% year-to-date (YTD), a little over twice the 8% gain in the Consumer Staples Select Sector SPDR Fund (XLP). It also reached a 52-week high of $207.76 in late July.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
This dividend increase is not only about cigarette sales. Philip Morris International is building its smoke-free business, and the regulatory wins are adding support. The FDA authorized 11 ZYN ULTRA nicotine pouch products in August. Weeks earlier, it gave 20 flagship ZYN products the first modified-risk orders issued for nicotine pouches, allowing Philip Morris International to market them as lower-risk alternatives to cigarettes.
With the dividend nearly 9% higher and smoke-free products gaining ground, can Philip Morris International's stock keep moving higher? Let's find out.
The Numbers Behind Its Dividend Strength
Philip Morris International sells cigarettes, but its business is increasingly tied to smoke-free products such as IQOS heated-tobacco devices and ZYN nicotine pouches. The company operates mainly outside the U.S. cigarette market, where Altria Group (MO) is the bigger name.
PM stock has gained 16% over the past 52 weeks and 17% so far in 2026.
 www.barchart.com
It now trades at 22.2x forward earnings, above the consumer staples sector average of 14.6x, so investors are paying more for its growth and dividend record.
Philip Morris International raised its quarterly dividend by 8.8%, from $1.47 to $1.60 per share. That brings the annual payout to $6.40 per share. The payment is due on Oct. 26 for shareholders on record as of Oct. 2, which is also the ex-dividend date.
Before the raise, the stock yielded 3.12%, compared with the consumer staples average of 1.89%, and its forward payout ratio was 72.4%. The company has raised its dividend for 19 straight years since becoming a public company in 2008. Since then, the payout has increased 248%, for a 7.2% compound annual growth rate.
The latest quarterly results help explain the larger payout. Total shipments rose 2.5% in the second quarter, led by 7.5% growth in smoke-free products. Revenue increased 10.4% to $11.2 billion, or 7.6% on an organic basis.
Smoke-free revenue grew 11.7% and accounted for about 42% of total sales, while cigarette revenue rose 9.5%. Gross profit increased 11.5%, operating income rose 22%, and adjusted diluted EPS climbed 15.2% to $2.20. Reported EPS fell 7.7% to $1.80 because of a non-cash impairment tied to the RBH investment. For 2026, Philip Morris International expects organic revenue growth of 5% to 7%, organic operating income growth of 7% to 9%, and about $13.5 billion in operating cash flow.
Building Beyond Traditional Cigarettes
Philip Morris USA, an Altria Group unit, has reached a contract manufacturing agreement with non-U.S. affiliates of Philip Morris International. The arrangement is meant to make Philip Morris USA’s traditional tobacco operations more efficient.
Altria Group said the deal supports its 2028 goals by improving operations and creating economic benefits that can support investment in its broader business plans. It could also strengthen capabilities that may be useful in international nicotine markets. Altria Group does not expect the agreement to have a material effect on its 2026 results, and the two companies will continue to run their own sales, distribution, and regulatory operations.
Meanwhile, Philip Morris International is adding U.S. production capacity. The company opened a roughly 780,000-square-foot plant in Aurora, Colorado, on a 148-acre site. Philip Morris International plans to invest $1.2 billion in the campus between 2024 and 2028. The facility started commercial production of ZYN nicotine pouches in July 2026, about 19 months after construction began. It joins the company’s U.S. operations in Owensboro, Kentucky, and Wilson, North Carolina, and will also support exports.
The Food and Drug Administration has also authorized 11 ZYN ULTRA moist oral nicotine pouch products sold by Swedish Match USA, a Philip Morris International affiliate. The approvals cover all 9 mg products and one 11 mg option, while other 11 mg variants remain under review. ZYN ULTRA pouches are tobacco-leaf-free and have a higher moisture level than standard ZYN products. The authorizations add to earlier FDA approvals for ZYN products in 3 mg and 6 mg strengths across several flavors.
Analysts Remain Focused on Growth
Philip Morris International is set to report third-quarter 2026 results on Oct. 20. Analysts expect the company to earn $2.34 per share for the September quarter, up 4.46% from $2.24 a year earlier. For the full year, the consensus calls for earnings of $8.44 per share, an 11.94% increase from $7.54 in 2025.
Needham analyst Gerald Pascarelli remains upbeat after Philip Morris International beat expectations in the second quarter. He kept his “Buy” rating and raised his price target to $215 from $200. The main reason was continued growth in the company’s smoke-free business, where shipments rose 7.5%, led by IQOS. BTIG Research also began coverage of Philip Morris International on July 21 with a $216 price target.
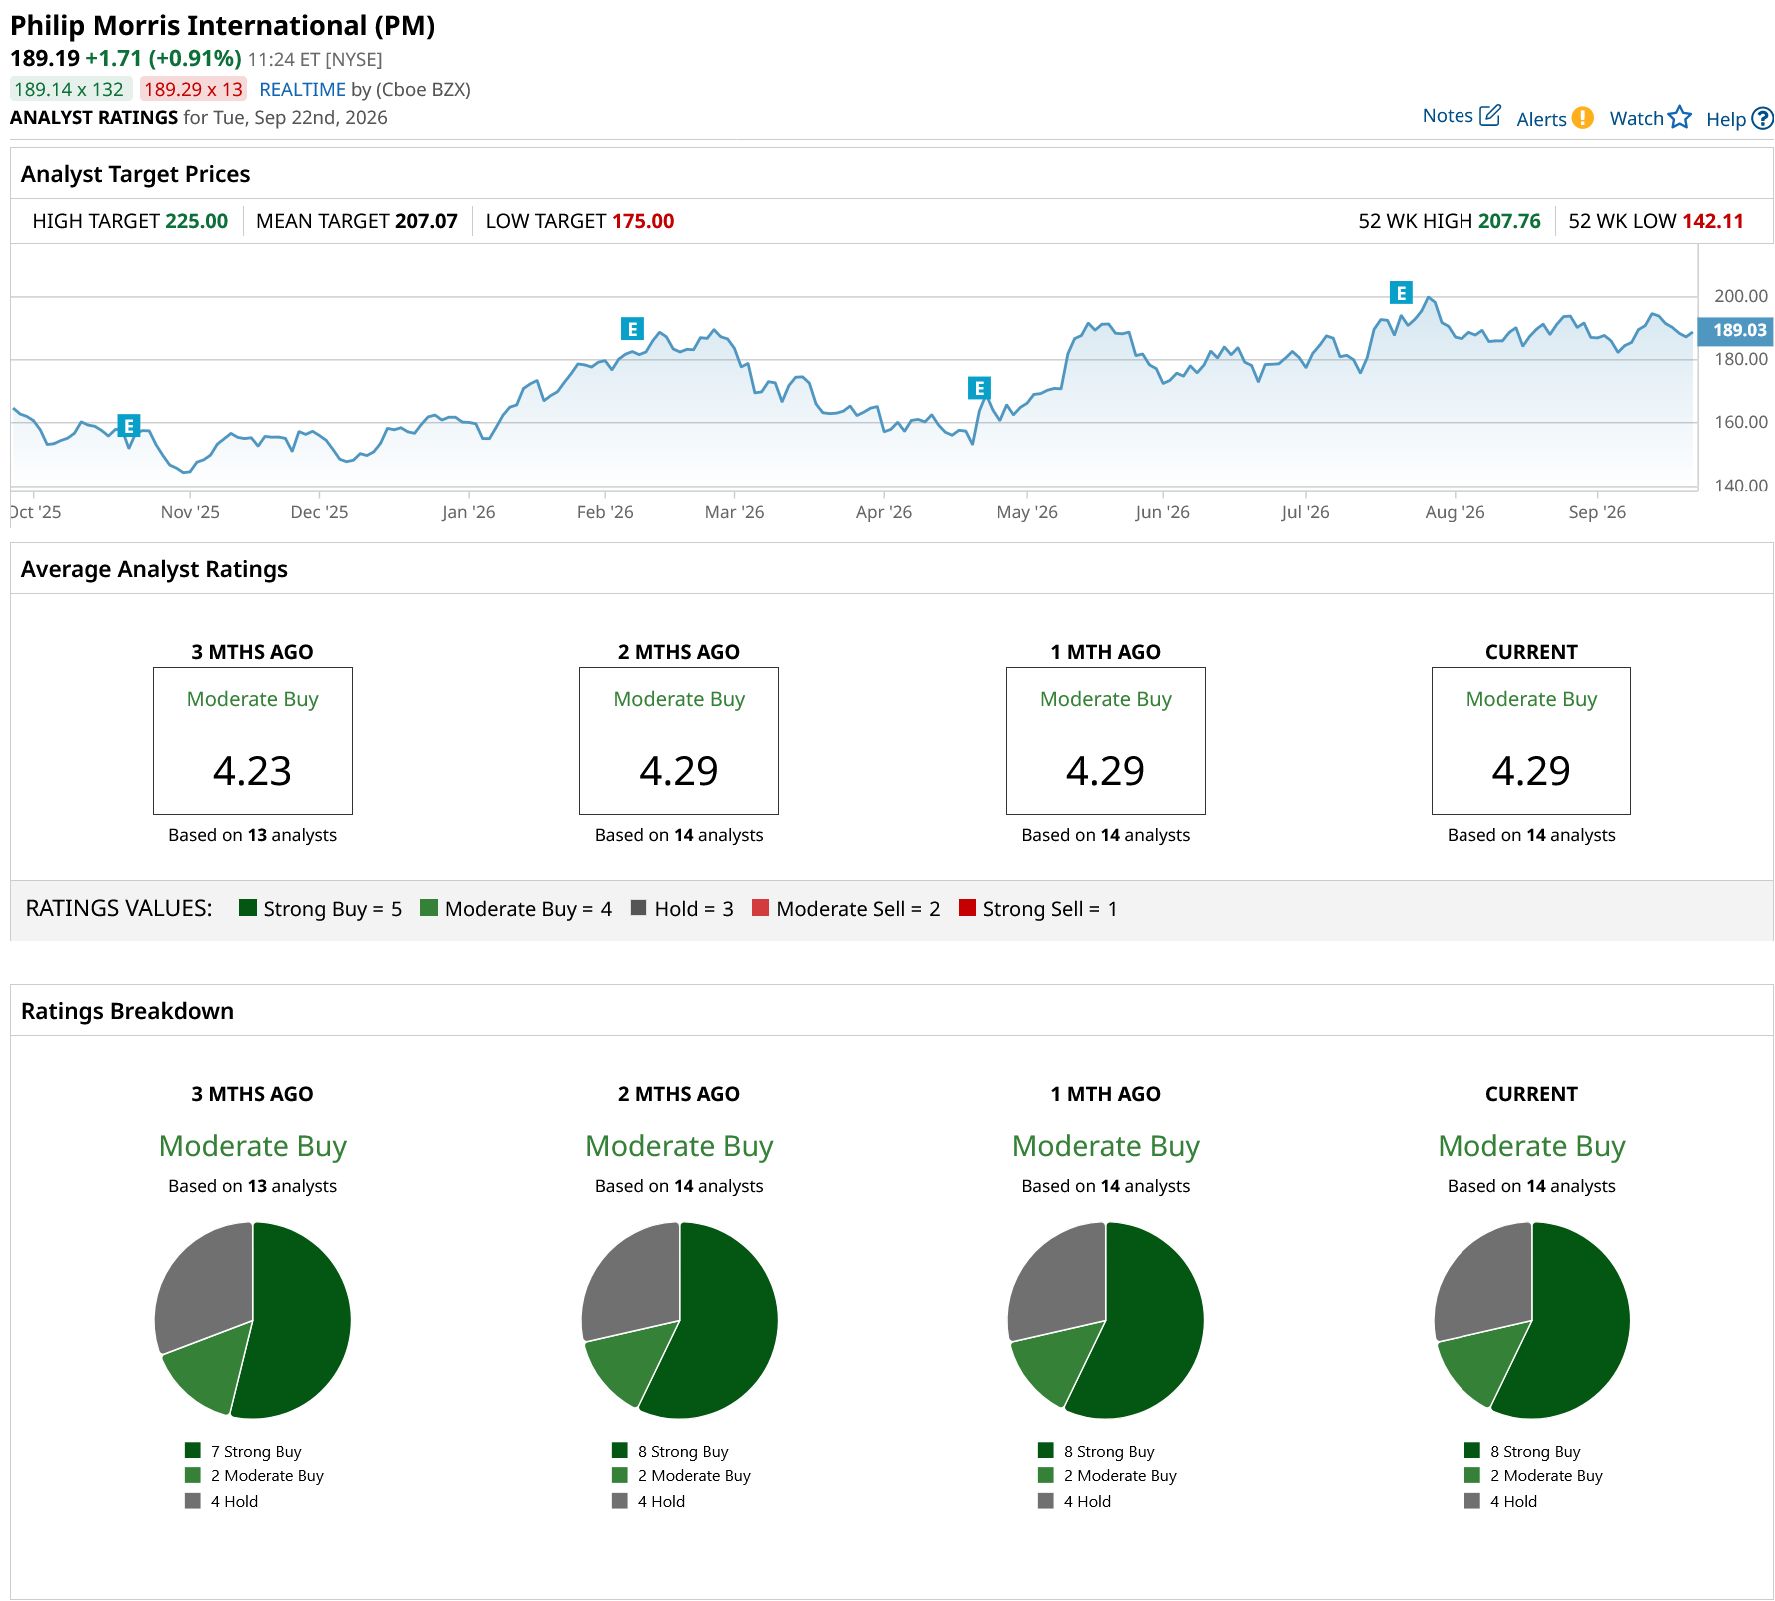
Overall, all 14 analysts covering PM stock rate it a consensus “Moderate Buy.” Their average price target of $207.07 suggests about 9% upside from recent levels.
 www.barchart.com
Conclusion
Philip Morris still looks well-positioned to keep rewarding income investors. The dividend raise is backed by solid earnings growth, rising smoke-free sales, and cash-flow guidance that supports both investment in ZYN and IQOS and a larger payout. The stock is not cheap at more than 22 times forward earnings, so investors should not expect a bargain entry point. Still, with analysts forecasting further EPS growth and a $207.07 average target, PM shares appear more likely to trend higher than lower if smoke-free volumes and pricing remain on track. The 8.8% raise makes that growth case more compelling for dividend investors.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This High-Yield Tobacco Stock Just Raised Its Dividend by 8.8% Microsoft Just Hiked Its Dividend by 8%. How to Play the Stock Here. IBM Once Held Nvidia's Spot as Tech's Biggest Name. The Stock Just Crashed 25%. Here's the Comeback Case. Ford Hasn’t Raised Its Dividend in Years. Don’t Count on a Hike in 2026.