

Cleveland, Ohio-based KeyCorp (KEY), with a market capitalization of approximately $22.6 billion, is one of the nation’s largest bank-based financial services companies. Operating through KeyBank, the company provides consumer and commercial banking, lending, wealth management, capital markets and investment banking services to individuals, businesses and institutions across the United States.
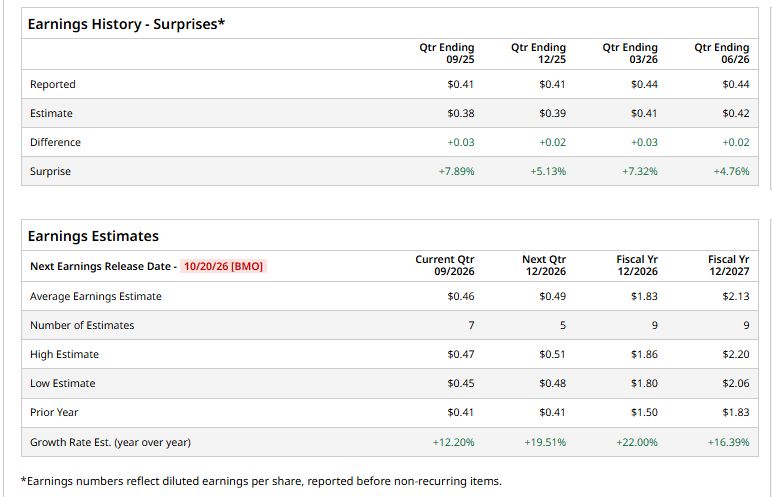
KeyCorp is set to report its Q3 earnings on Tuesday, October 20, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of 46 cents, up 12.2% from 41 cents in the year-ago quarter. KeyCorp has also exceeded Wall Street’s EPS estimates in each of the past four quarters, underscoring its consistent earnings execution.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect the company to report EPS of $1.83, representing a 22% increase from $1.50 in fiscal 2025. EPS is projected to grow another 16.4% year over year to $2.13 in fiscal 2027.
 www.barchart.com
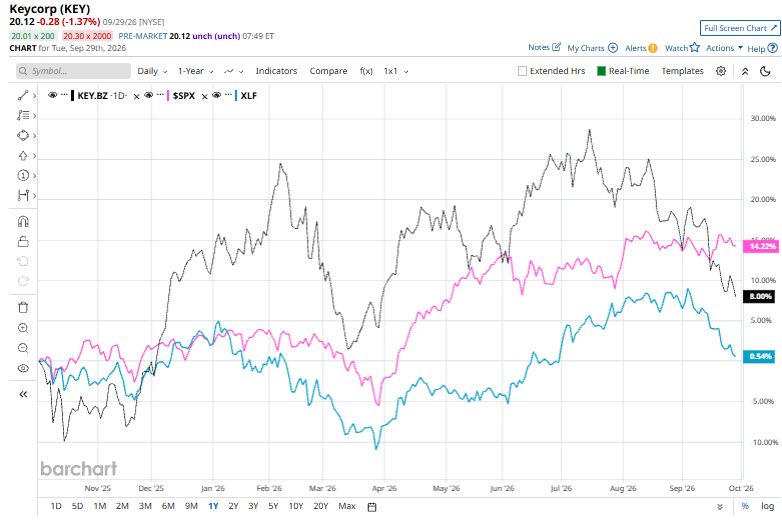
KEY stock has climbed 6.6% over the past 52 weeks, trailing the S&P 500 Index ($SPX), which gained 15.2%. However, KEY has significantly outperformed the State Street Financial Select Sector SPDR ETF (XLF), which posted only a marginal decline over the same period.
 www.barchart.com
KeyCorp’s underperformance against its peers has been driven by muted net interest income growth, declining earnings and stagnant tangible book value. Over the past five years, net interest income grew just 3.8% annually, while EPS declined 5.9% annually, pointing to weaker profitability. Meanwhile, stagnant tangible book value per share has limited the bank’s ability to leverage its balance sheet for additional investments.
On the bright side, KeyCorp completed its acquisition of Clearwater Corporate Finance LLP on August 4, 2026, a U.K.-based middle-market investment banking advisory firm. The acquisition expands Key’s global advisory platform and adds expertise in M&A, private equity and debt advisory across multiple sectors.
Analysts remain moderately bullish on KEY, with the stock carrying a consensus “Moderate Buy” rating. Among the 20 analysts covering the stock, nine recommend a “Strong Buy,” two rate it a “Moderate Buy,” and nine suggest a “Hold.” Meanwhile, the average price target of $24.79 implies potential upside of 23.2% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play QCOM Stock as Apple Renews Licensing Agreement With Qualcomm Dear Corteva Stock Fans, Mark Your Calendars for Oct. 1 Nvidia Just Spent Nearly $13 Billion on Something Other Than GPUs. Here’s How It Helps NVDA. Dear Nike Stock Fans, Mark Your Calendars for Oct. 1