

Accenture (ACN) investors have a key date to watch as the company prepares to report its fourth-quarter and full-year fiscal 2026 results on Oct. 1, with investors closely watching demand trends, fiscal 2027 guidance, and the impact of artificial intelligence on its business.
With AI creating both new opportunities and potential disruption for traditional consulting services, the upcoming report could provide important clues about Accenture’s growth trajectory heading into fiscal 2027. Let’s dig deeper.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Accenture Stock
Accenture is a global professional services company that provides consulting, technology, and operations services, helping organizations build digital capabilities and adopt AI. Headquartered in Dublin, Ireland, Accenture serves clients across industries through capabilities spanning AI and data, cybersecurity, cloud, digital transformation, finance, supply chain, engineering, and technology. Accenture has a market cap of about $108.4 billion.
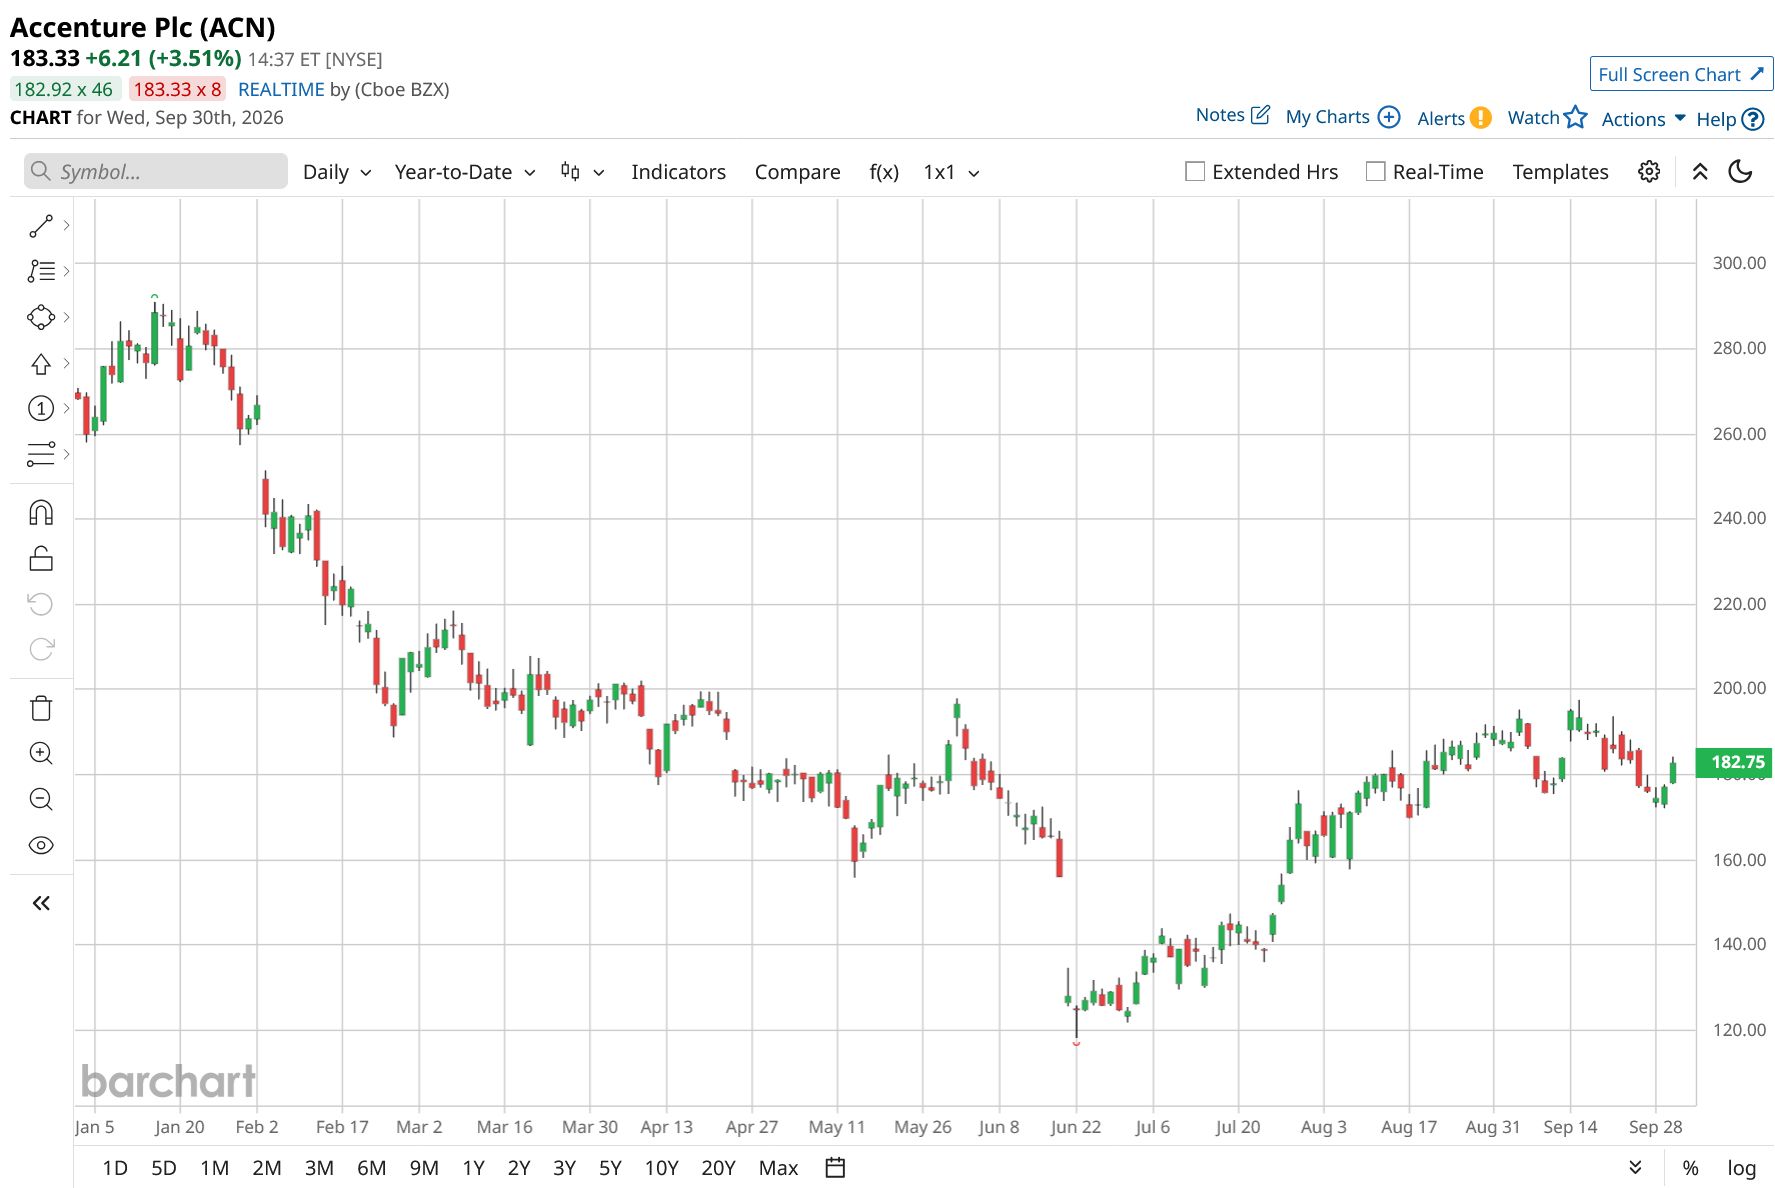
Accenture stock has remained under significant pressure in 2026, reflecting investor concerns about its spending trajectory and the potential for artificial intelligence to disrupt parts of the company’s traditional consulting and IT services business. Shares are down about 32% year-to-date (YTD) and roughly 37% below their 52-week high of $291.09, reached on Jan. 14, and are down 26% over the past year. ACN stock has also declined 0.44% over the past five trading sessions.
The YTD decline has been driven in part by Accenture’s weaker growth outlook and concerns over demand. Following its fiscal third-quarter results, the company lowered its fiscal 2026 revenue-growth outlook to 3%-4% in local currency. Investors have also worried that generative AI could reduce demand for some labor-intensive consulting and managed-services work, even as Accenture positions itself to benefit from AI-related transformation, data, cloud, and modernization projects.
More recently, ACN shares have remained volatile ahead of the company’s Oct. 1 fiscal fourth-quarter earnings report. With investors focused on fiscal 2027 guidance, bookings, and the pace at which AI-related demand is translating into revenue, the upcoming earnings report could be an important catalyst for the stock.
In terms of forward price-to-earnings (P/E) ratio, ACN stands at 12.02, below the industry average. Furthermore, the stock is at 1.51 times sales, which is also a discount compared to its peers.
 www.barchart.com
Mixed Q3 Performance and Outlook
Accenture reported its third-quarter fiscal 2026 results on Jun. 18, for the quarter ended May 31. Revenue increased 6% year-over-year (YoY) to $18.7 billion, while growth was 3% in local currency; Consulting revenue rose 4% and 1% in local currency to $9.3 billion, while Managed Services revenue increased 8% in U.S. dollars and 5% in local currency to $9.4 billion.
Profitability also improved. Operating income rose 6% to $3.2 billion, while the operating margin expanded to 17% from 16.8%. Net income increased to $2.4 billion from $2.2 billion, while net income attributable to Accenture rose to $2.3 billion from $2.2 billion. Its EPS increased 9% to $3.80 from $3.49, ahead of expectations.
New bookings, however, were softer. Accenture generated $19.3 billion of bookings, down 2%. Consulting bookings were $10.3 billion, while Managed Services bookings totaled $9.1 billion. Despite the quarterly decline, management highlighted strong demand for large-scale transformation projects, noting that the company had secured 104 client bookings of at least $100 million YTD, up 13%.
Geographically, growth was strongest in the Asia Pacific region, where revenue rose 7% to $2.7 billion. EMEA revenue increased 10% to $6.9 billion, while Americas revenue grew 2% to $9.1 billion. Among industry groups, Communications, Media & Technology was the fastest-growing business, with revenue up 10% to $3.2 billion.
Cash generation remained stable. Operating cash flow increased to $3.8 billion from $3.7 billion, while free cash flow rose to $3.6 billion from $3.5 billion.
On the other hand, Accenture lowered its full-year fiscal 2026 revenue-growth outlook to 3%-4% in local currency, compared with its previous 3%-5% range.
However, Accenture raised the full-year EPS outlook. It now expects adjusted EPS at 13.78-13.90, up 7%-8%, versus the previous 13.65-13.90 range. The company maintained its 10.8 billion-11.5 billion free cash flow outlook.
For the fourth quarter, Accenture guided for revenue of 17.75 billion-18.4 billion, implying 1%-5% growth in local currency.
In addition, analysts expect EPS of $13.87 for fiscal 2026, representing about 7.3% YoY growth, while fiscal 2027 earnings are expected to grow 5.5% to $14.63. For the fourth quarter, the consensus estimate calls for EPS of $3.19, up about 5.3% from the prior-year period.
What Do Analysts Expect for ACN Stock?
Susquehanna maintained its “Neutral” rating on ACN stock on Sept. 28 while raising its price target to $153 from $140 ahead of Accenture’s Oct. 1 fiscal fourth-quarter earnings.
On the flip side, JPMorgan maintained its “Overweight” rating on Accenture on Sept. 25 while raising its price target to $200 from $179, reflecting confidence.
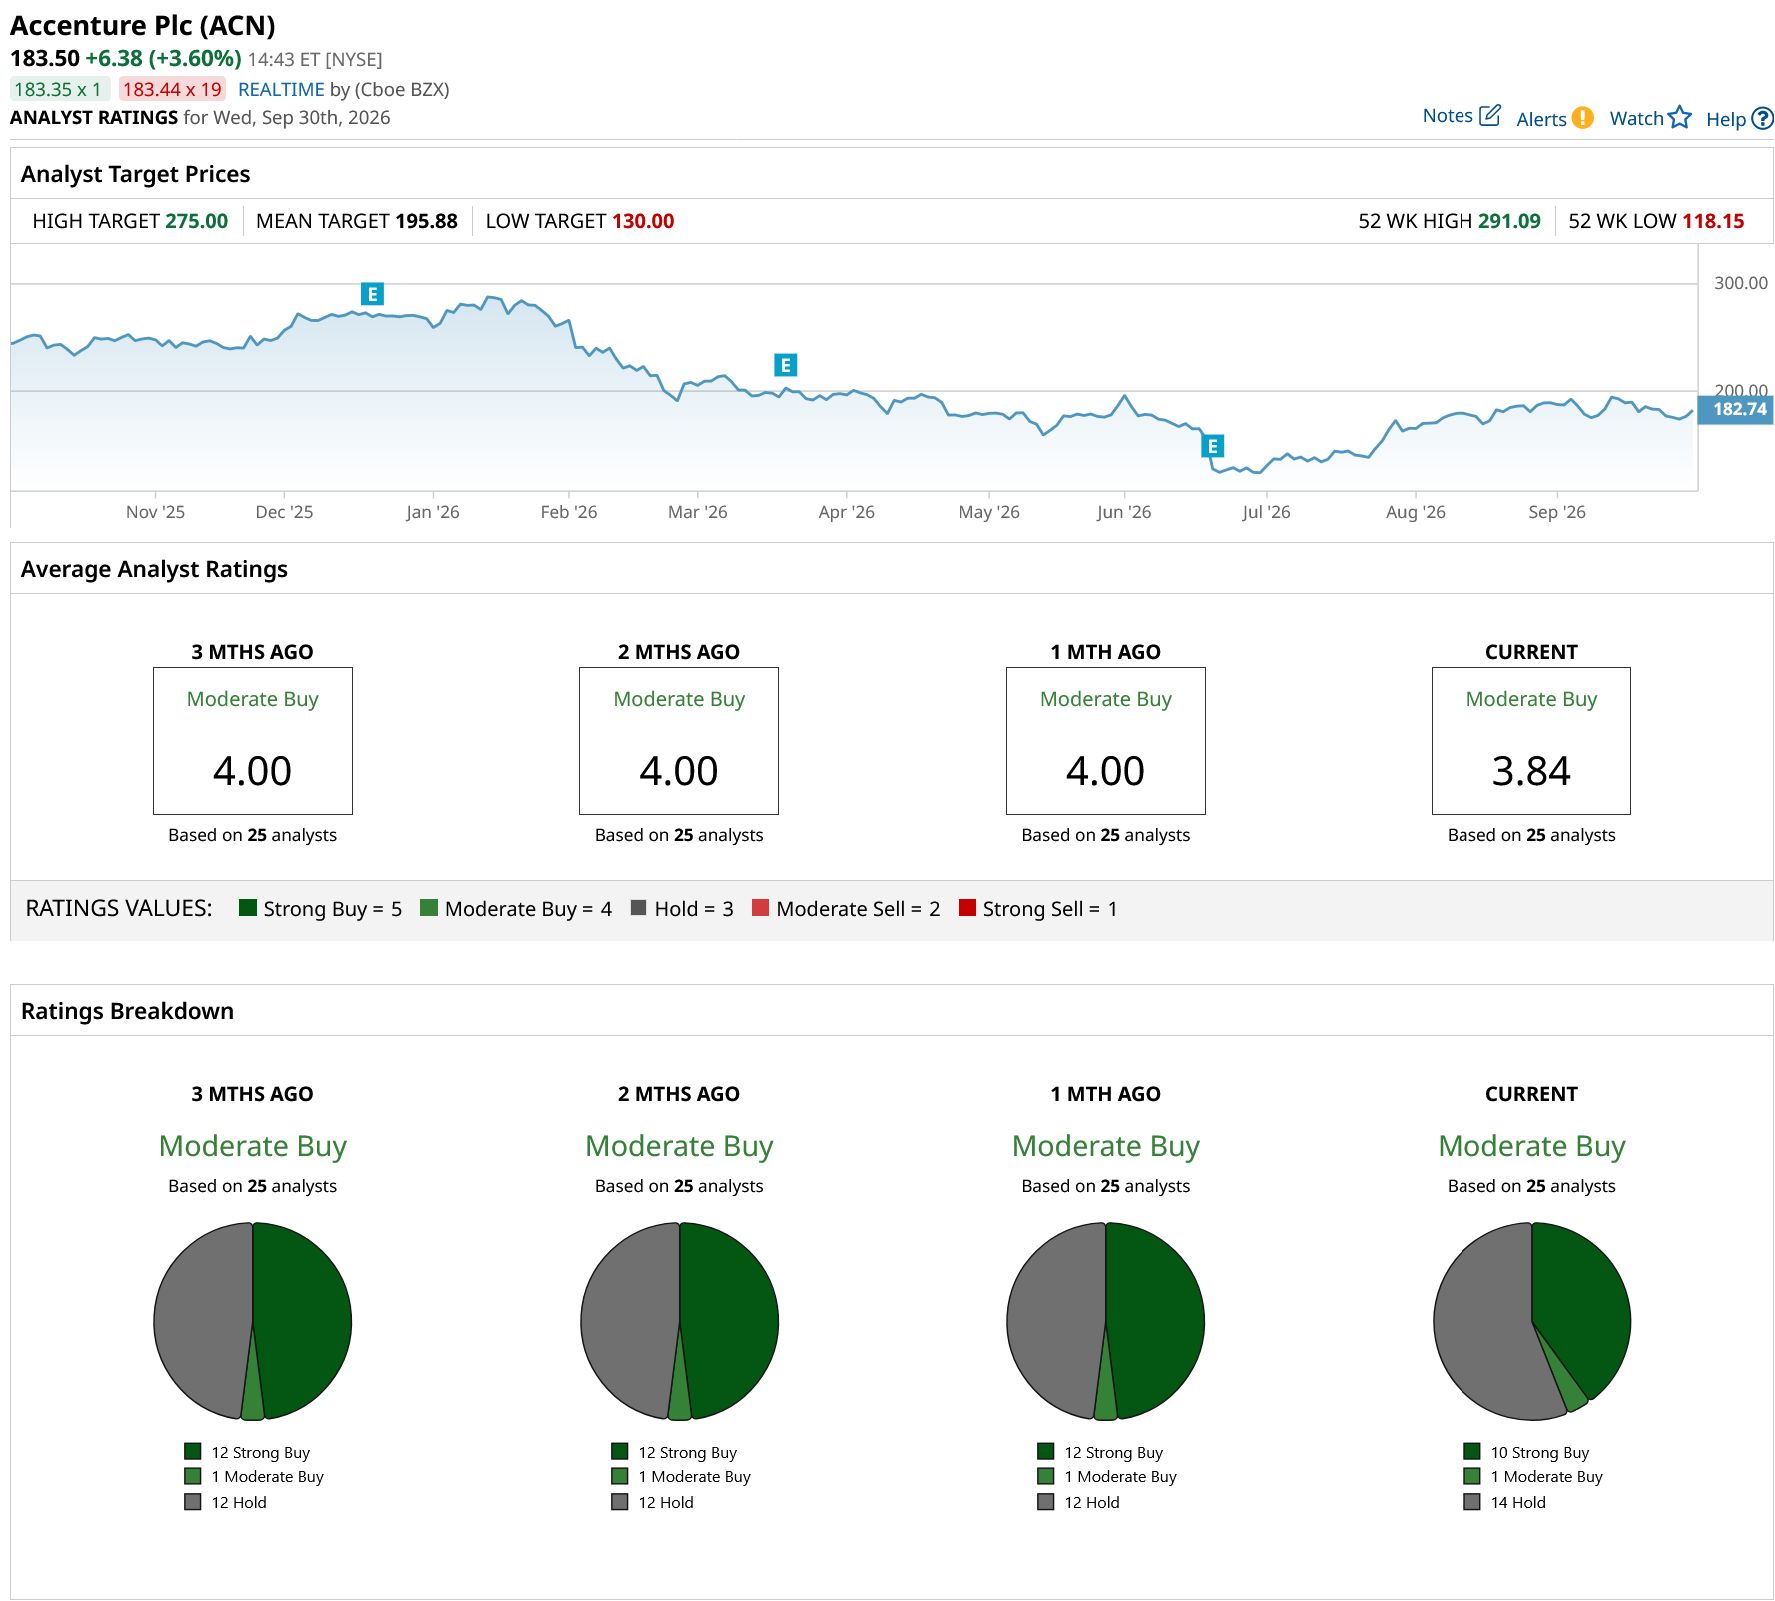
Overall, ACN stock has a consensus “Moderate Buy” rating. Out of 25 analysts covering it, 10 recommend a “Strong Buy,” one suggests a “Moderate Buy,” and 14 analysts stay cautious with a “Hold” rating.
ACN’s average analyst price target of $195.88 reflects an upside of 7%, while the Street-high target price of $275 suggests 50% upside ahead.
 www.barchart.com
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Hewlett Packard Stock Just Got a Big Boost Powered by AMD Dear Accenture Stock Fans, Mark Your Calendars for October 1 How a UPS Transport Gone Wrong Apparently Left Lockheed Martin’s Secrets in China’s Hands Target Stock Just Scored a New 'Buy' Rating. Here's Why.