

Artificial Intelligence continues to progress, as does the playing field for small businesses, offering powerful tools to streamline operations, automate marketing, and drive growth with limited resources. As these technological advancements become necessary for daily management, major tech companies have begun expanding these capabilities, starting with Meta’s (META) latest updates for its Muse AI.
Meta Platforms
Meta Platforms is a global tech and social media giant with its headquarters in Menlo Park, California. The social media juggernaut began with Facebook and now operates a host of social media apps under its umbrella, including Instagram, WhatsApp, Threads, and more. Recently, Meta has pivoted aggressively towards AI investment and expansion, such as its recent rollout of its personal AI agent, Muse AI, earlier this month.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
META Stock Making a Comeback
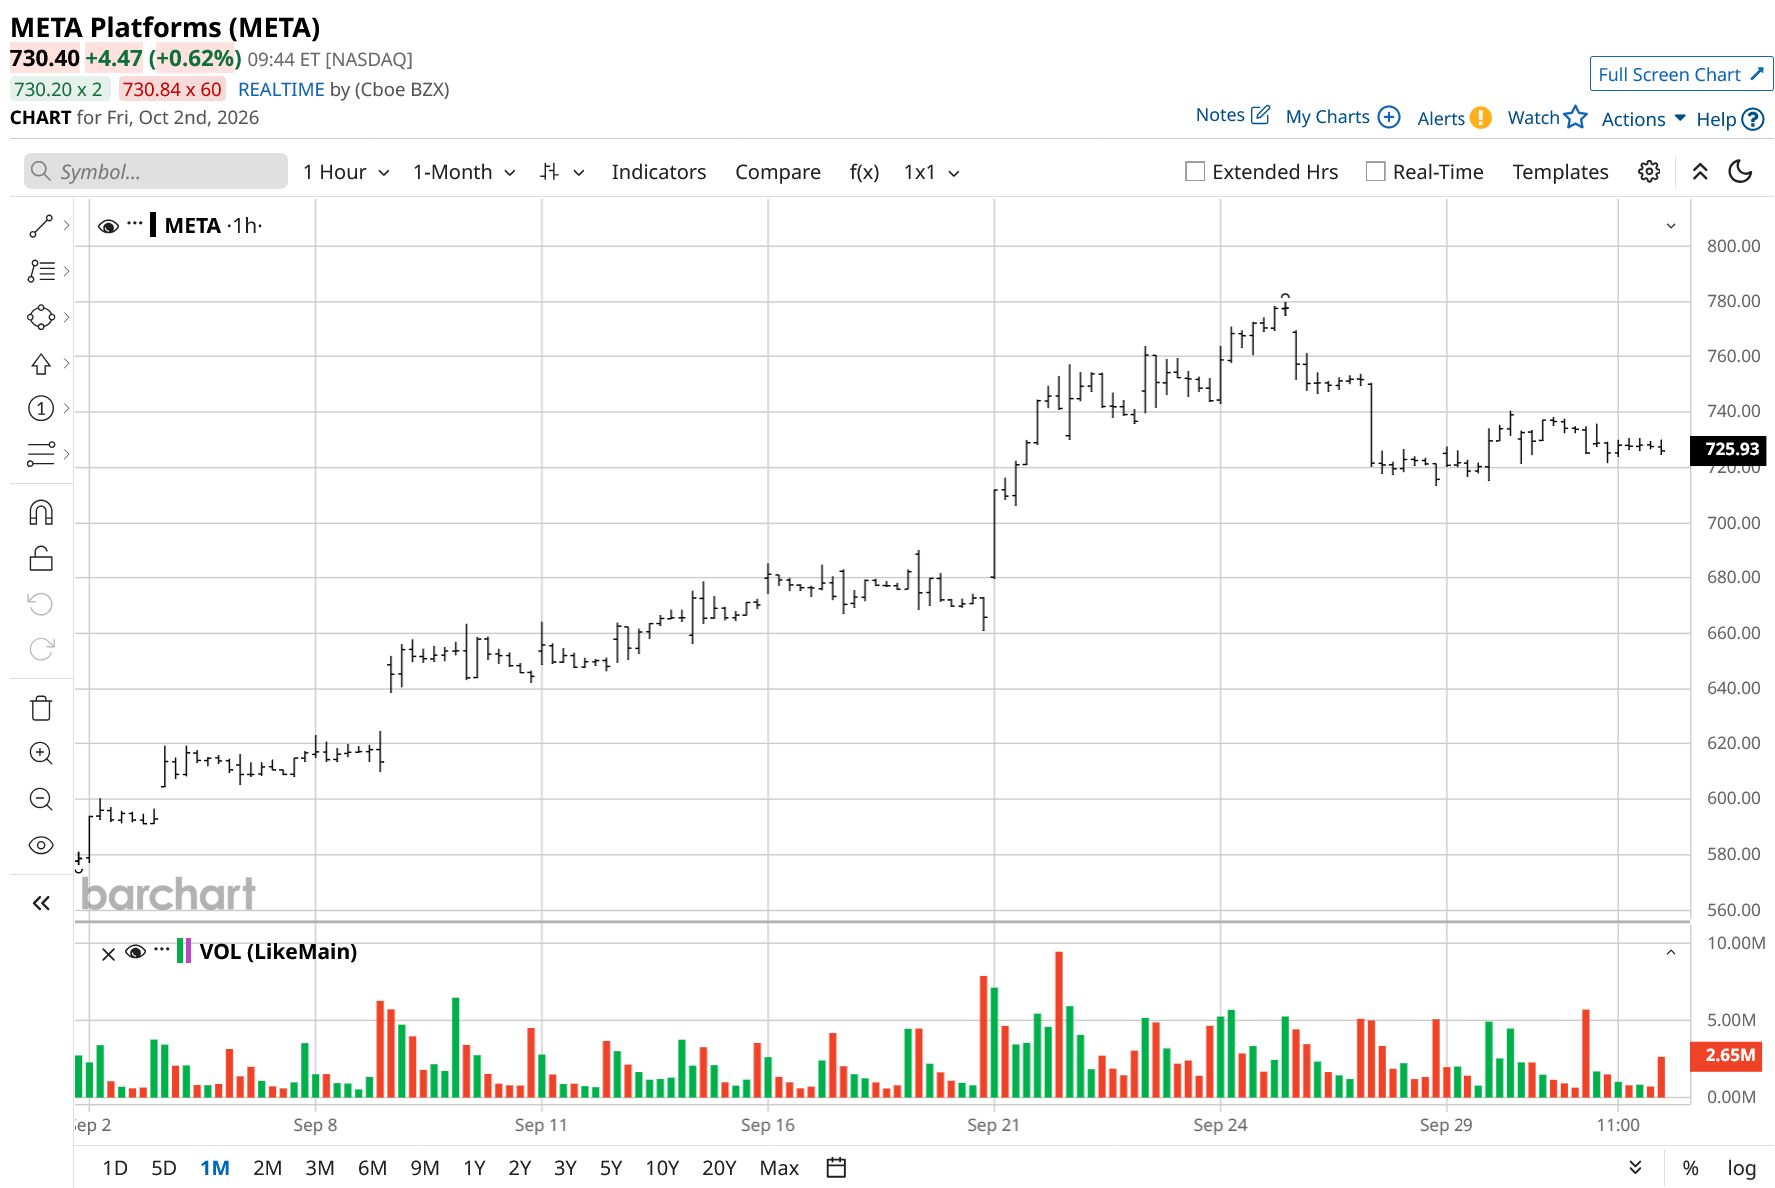
META stock closed at $725.18 on Oct. 1, essentially flat on the day, and valuing the company near $1.85 trillion. It's up roughly 11% this year and about 6% below its 52-week high of $779.82. Trading has been choppy lately, with an 11% jump on Sept. 21 followed by numerous 3-5% swings.
Verses the S&P 500 Communication Services Index ($SRTS), which is up 11% over 52 weeks and roughly 3.5% year-to-date (YTD). META stock's 11% YTD gain clearly outpaces that, but its 52-week increase of 1% does not. Meta itself heavily influences the sector's performance.
 www.barchart.com
Mixed Q2 Results
Meta's second-quarter 2026 results showed revenue of $60.80 billion, up 28% year-over-year (YoY) and edging past the $60.29 billion analyst consensus. However, diluted EPS came in at $6.18, missing the $7.22 estimate by more than 14%, snapping a six-quarter streak of earnings beats as surging AI-related costs overwhelmed strong top-line growth.
Total costs and expenses surged 55% YoY to $42.03 billion, including $2.40 billion in legal charges and $1.18 billion in severance tied to an 8,000-employee headcount reduction, compressing GAAP operating margin to 31% from 43% a year earlier. Advertising revenue climbed 27% to $59.36 billion, with ad impressions up 14% and average price per ad up 12%, while free cash flow plunged 91% to just $784 million as capital expenditures hit $31.1 billion for the quarter.
Management guided third-quarter revenue to $61-$64 billion, below the Street's $63.15 billion estimate, and narrowed full-year 2026 capital expenditure guidance to $130-$145 billion. CEO Mark Zuckerberg said AI is “accelerating our core business today... and opening the door to entirely new enterprise opportunities,” while executives highlighted early traction from the newly launched Meta Enterprise Platform and viral consumer adoption of Muse as key emerging monetization pathways.
Meta Upgrades Muse AI
Meta has upgraded its latest launch, Muse AI, even further, introducing Muse for small businesses, offering a whole range of goals suited for small businesses, such as running operations or finding new customers. The tool connects with your business apps such as Shopify (SHOP), Asana (ASAN), Canva, Box (BOX), Dropbox (DBX), Figma (FIG), Intuit (INTU), QuickBooks, Notion, Slack, Stripe, and Zoom (ZM), alongside users’ Facebook and Instagram business accounts.
The move follows its Monday announcement, in which it disclosed it is launching a wider enterprise platform led by MongoDB (MDB) CEO CJ Desai that will bundle a Muse AI agent, a business agent, and a coding agent for enterprise customers.
Should You Bet on META Stock?
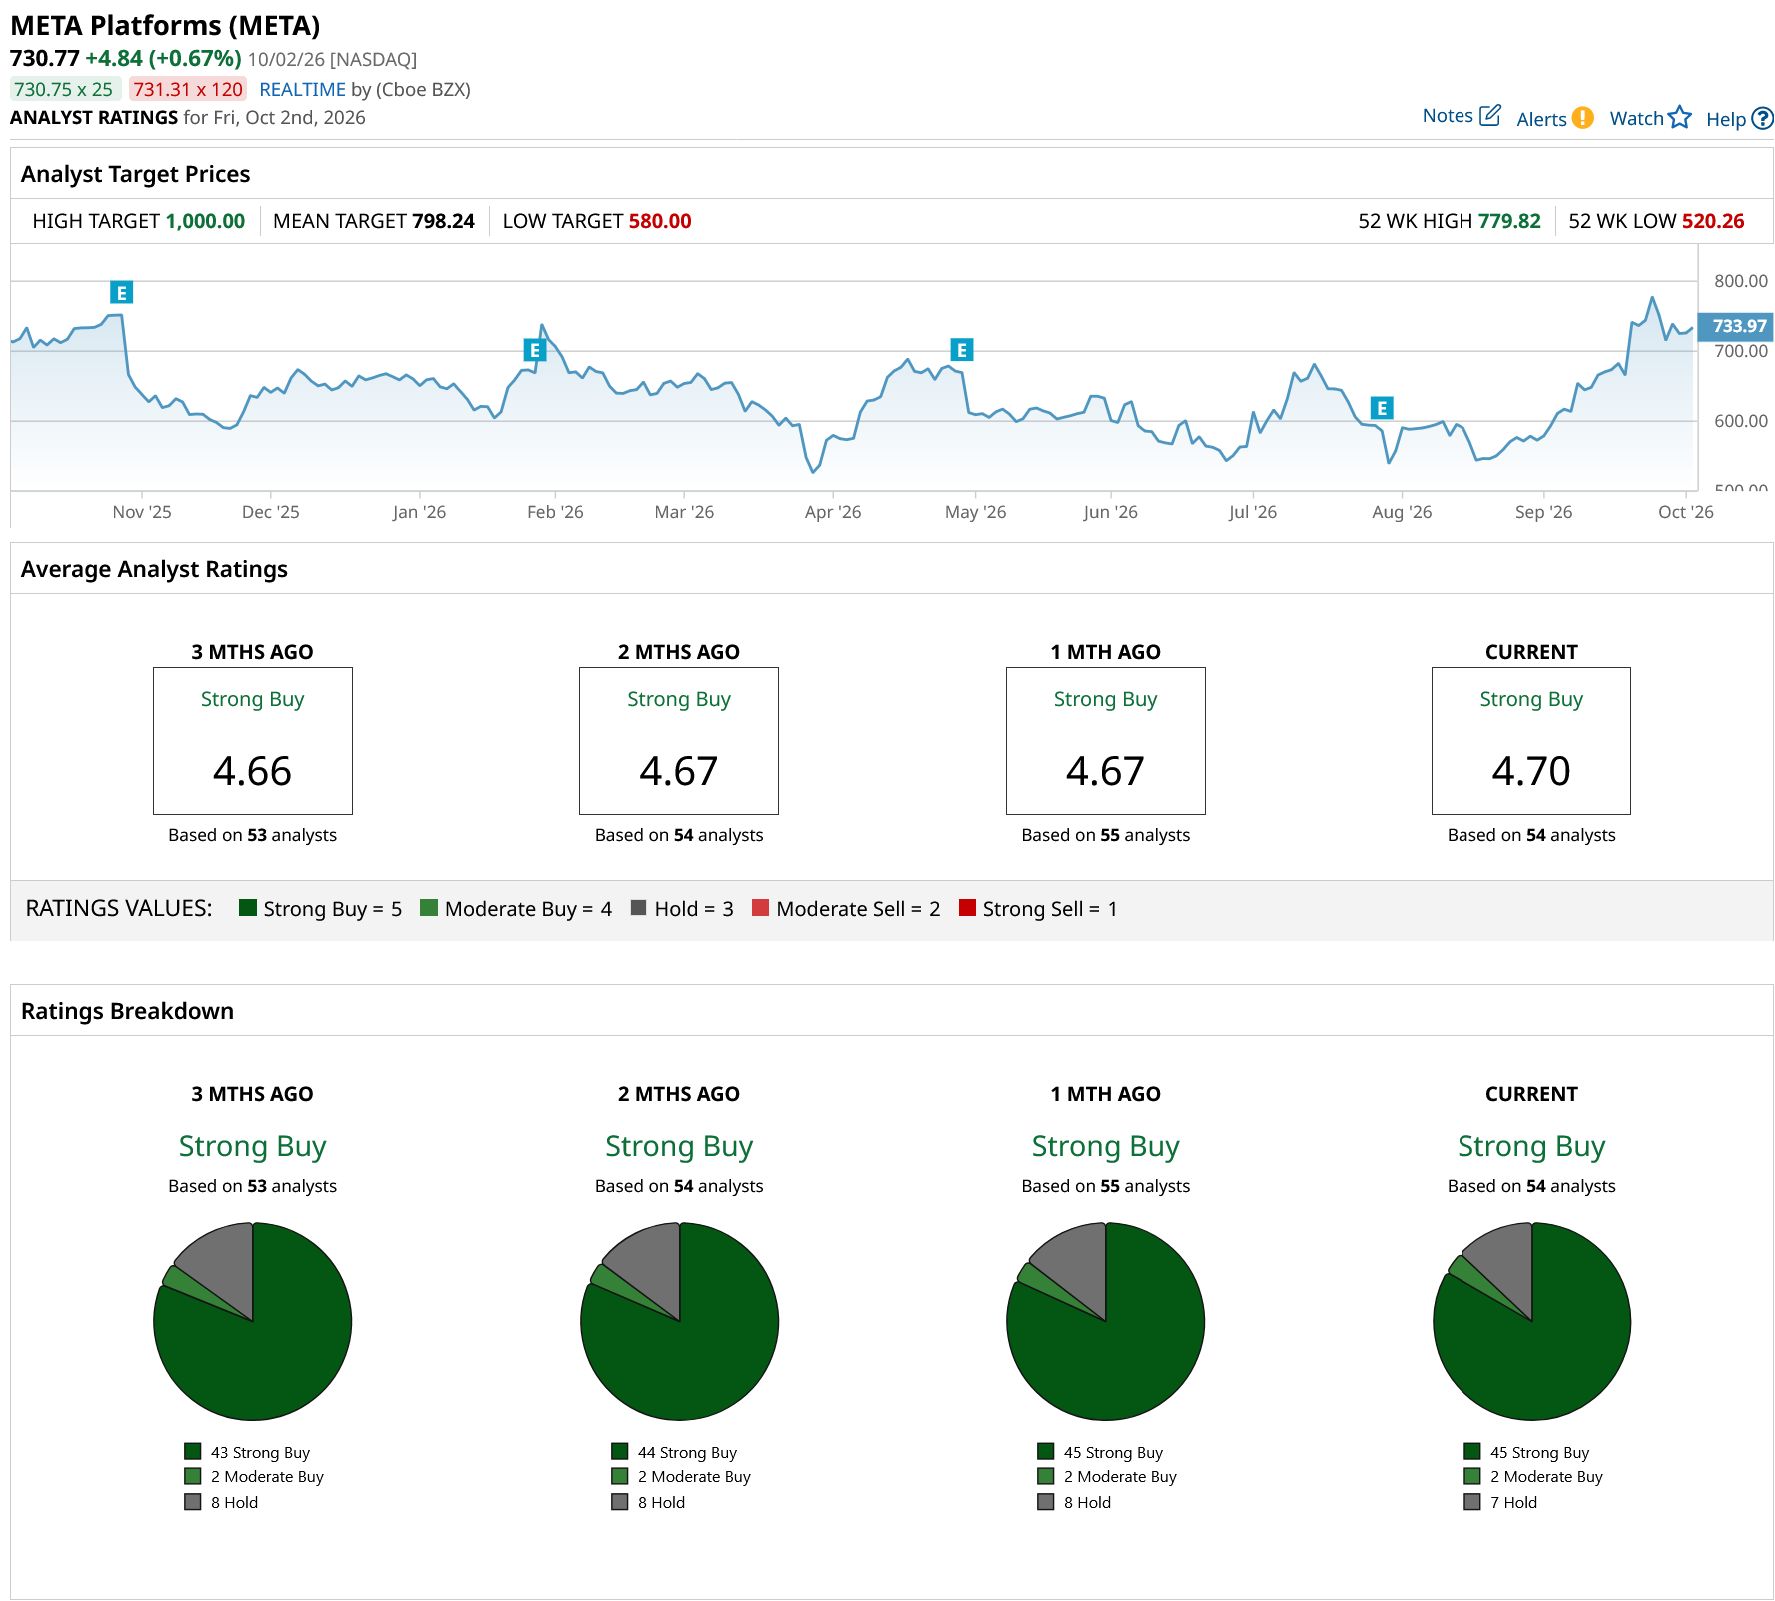
Amid the ongoing Muse AI upgrade for small businesses, it allows Meta to operate and transform generative AI into practical, solution-oriented tools for enterprise growth. Wall Street remains bullish on META stock, with Meta holding a consensus “Strong Buy” rating and a mean price target of $798.24, reflecting a 9% upside from the current market price. The stock has been backed by 54 analysts consisting of 45 “Strong Buy” ratings, two “Moderate Buy” ratings, and seven “Hold” ratings, presenting a compelling opportunity for growth-focused investors.
 www.barchart.com
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.