

VeriSign, Inc. (VRSN), headquartered in Reston, Virginia, provides domain name registry services and internet infrastructure that enables internet navigation for various recognized domain names. Valued at $26 billion by market cap, the company enables the security, stability, and resiliency of key internet infrastructure and services, as well as provides root zone maintainer services. The global provider of critical internet infrastructure and domain name registry services is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Thursday, Oct. 22.
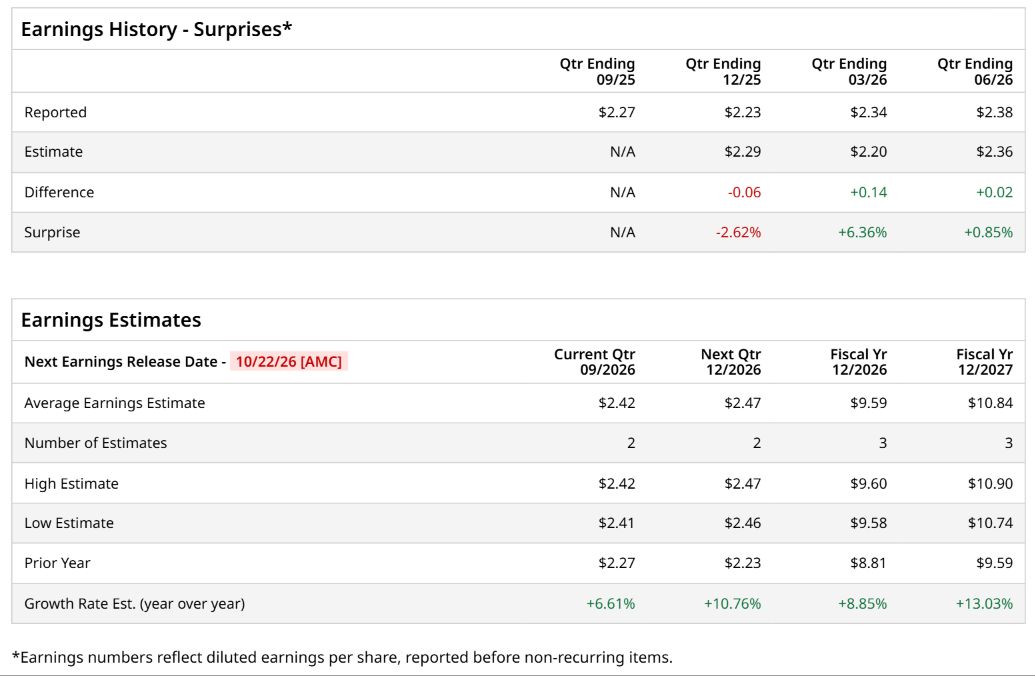
Ahead of the event, analysts expect VeriSign to report a profit of $2.42 per share on a diluted basis, up 6.6% from $2.27 per share in the year-ago quarter. The company beat the consensus estimates in two of the last three quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect VeriSign to report EPS of $9.59, up 8.9% from $8.81 in fiscal 2025. Its EPS is expected to rise 13% year over year to $10.84 in fiscal 2027.
 www.barchart.com
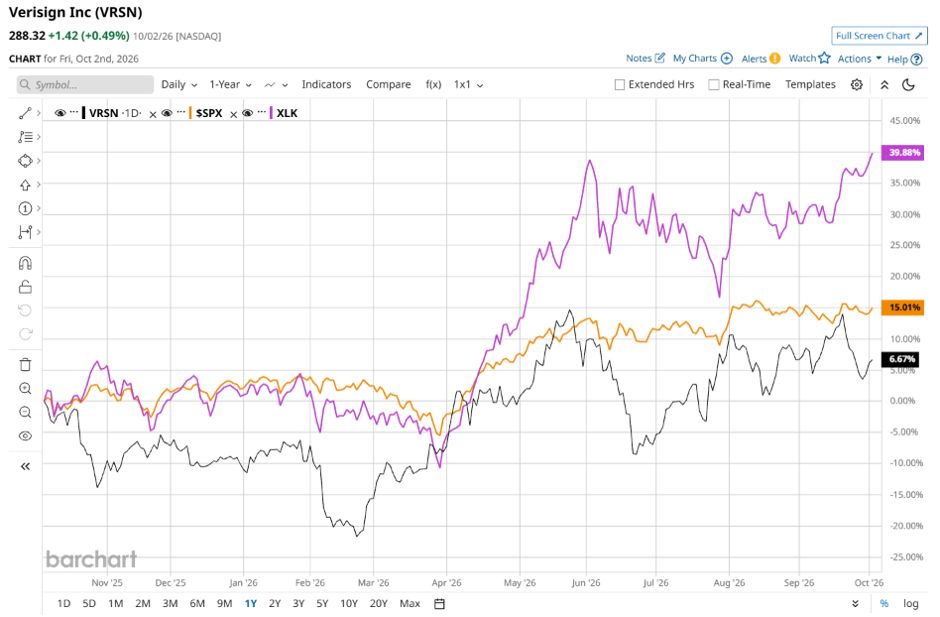
VRSN stock has underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares up 4.7% during this period. Similarly, it notably underperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 40.2% gains over the same time frame.
 www.barchart.com
VRSN’s underperformance stems primarily from growth moderation in its core .com and .net domain registries, where new website creation slowed following post-pandemic highs. This volume deceleration sparked analyst downgrades and valuation multiple compression, as small businesses increasingly rely on third-party digital platforms, like social commerce and direct storefronts over traditional web domains. Additionally, higher spending on IT infrastructure and security initiatives slightly squeezed operating margins. Although VRSN maintains net profit margins above 50% and aggressive share buybacks, investor caution remains tied to its single-service dependency and a lack of immediate catalysts beyond scheduled wholesale price increases.
Analysts’ consensus opinion on VRSN stock is moderately bullish, with a “Moderate Buy” rating overall. Out of five analysts covering the stock, three advise a “Strong Buy” rating, and two give a “Hold.” VRSN’s average analyst price target is $334.25, indicating a potential upside of 15.9% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.