

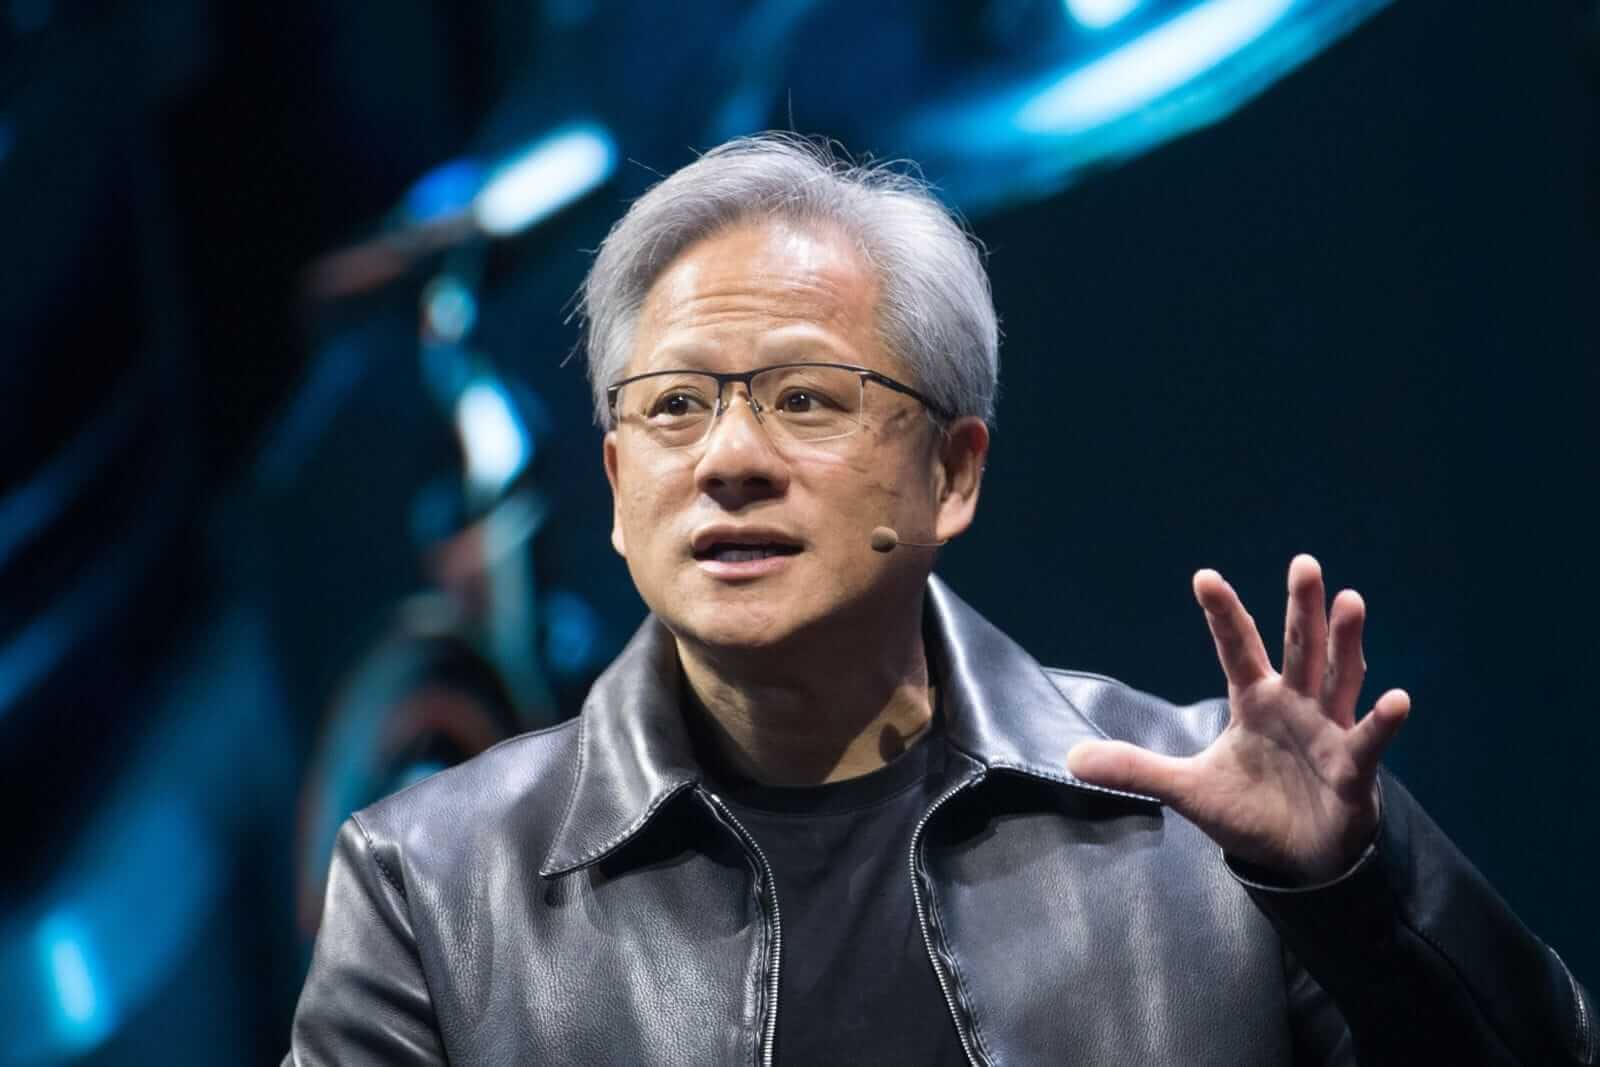
Morgan Stanley once again showed its confidence in Nvidia (NVDA) stock by putting the AI chip giant back at the top of its semiconductor list.
The call is way more than a higher price target. Analysts led by Joseph Moore met with CEO Jensen Huang and CFO Colette Kress and came away more confident that Nvidia is still early in a new growth cycle. Morgan Stanley sees the Vera Rubin ramp, tight power availability, and rising demand for agentic AI as potential catalysts.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
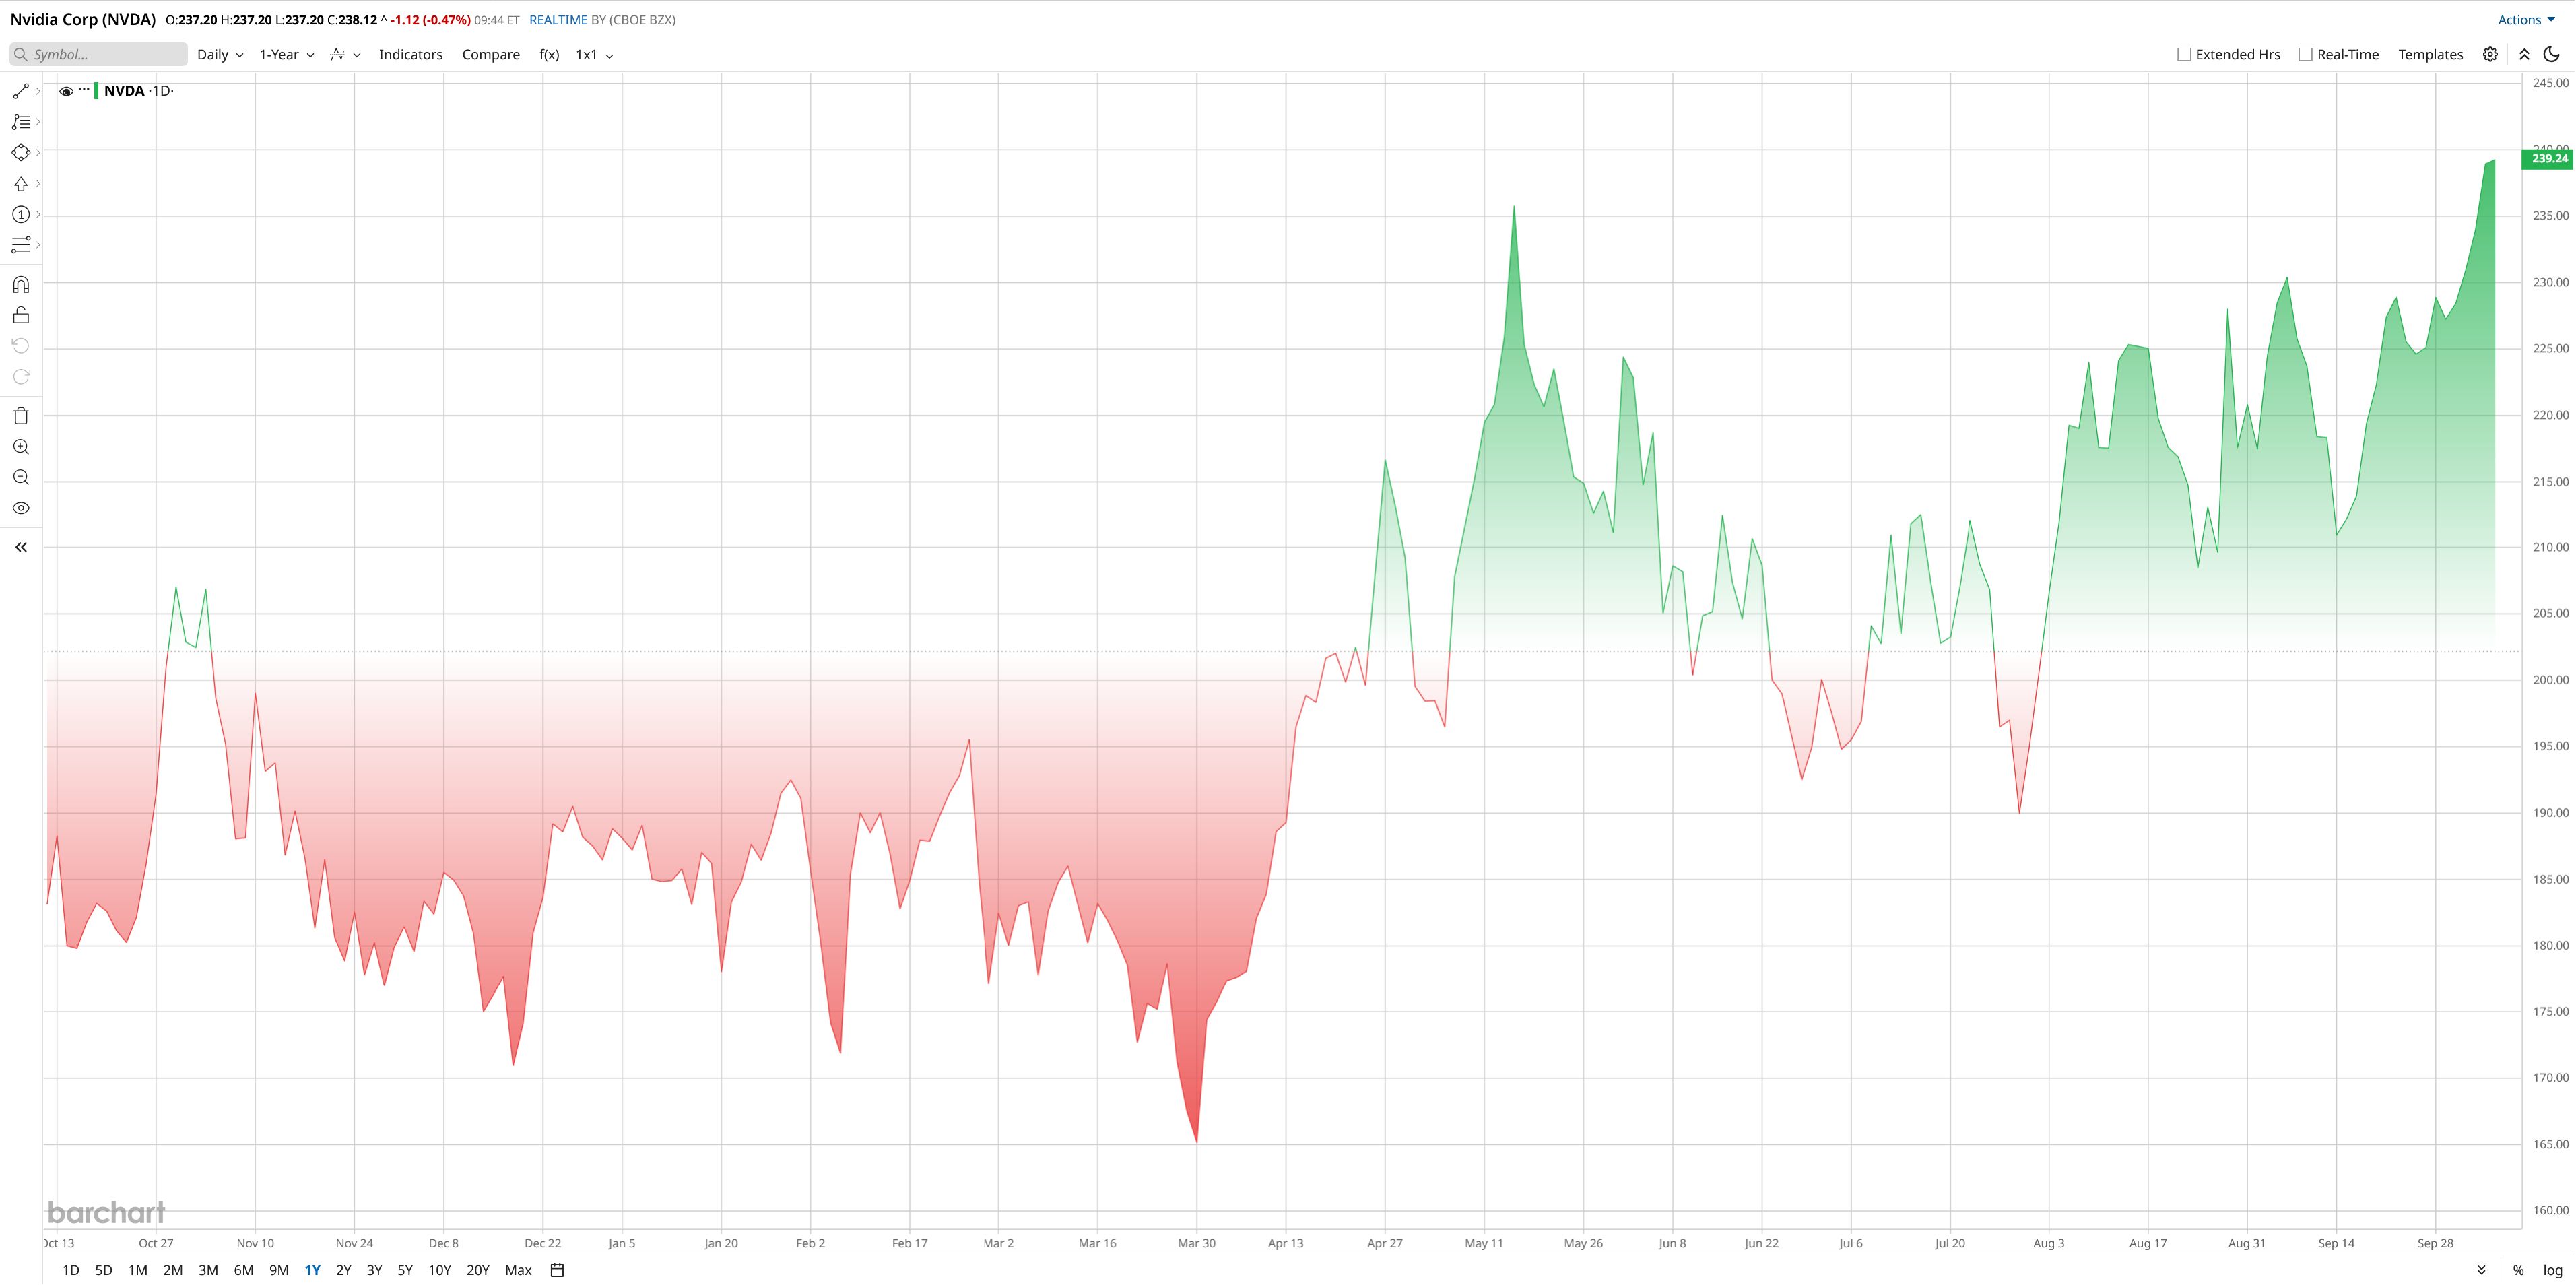
This endorsement comes as NVDA stock already climbed 27% year-to-date (YTD) as investors focused on AI demand, the Blackwell Ultra ramp, and Nvidia’s earnings beat.
However, as you are seeing in the chart, the rally has not been smooth. Supply constraints, memory costs, and restrictions on selling advanced chips into China have created periods of volatility. Still, investors remain focused on the longer-term AI opportunity.
 www.barchart.com
Morgan Stanley Sees Another Nvidia Growth Cycle
Morgan Stanley isn't counting on Nvidia being late to the AI party. Rather, Moore's team believes it will be a new product cycle with the company's next-generation Vera platform starting to ramp up. This may provide Nvidia with yet another chance to expand adds as investors ponder whether spending on AI infrastructure can extend like this.
Shortage of power may be to Nvidia's advantage as well. Customers require increased compute power and are constrained by equipment and data center growth. With that, it's getting increasingly critical to deliver real results in watts, and this is an area that Nvidia feels it can continue to hold its own.
There's a new potential demand factor, Agentic AI. Such systems are capable of carrying out more complex undertakings than just answering the question and can use far more compute. According to Huang, an AI agent can process 15 to 100 times the compute of a regular query.
Nvidia itself is going for the CPU market as well. As revenues for graphics processors end, its opportunity is growing bigger as the firm sees CPU revenue climb to $20 billion in 2026 and to $40 billion in 2027.
Nvidia Beats Q2 Earnings Estimates
As always, Nvidia's earnings never disappoint its investors. In Q2, that also happened when the chipmaker reported a 106% growth in revenue, reaching $96.2 billion, while adjusted EPS reached $2.22. Gross margin remained at a healthy 75%, and free cash flow reached up to $21.3 billion.
Management guided for $108 billion of revenue in the following quarter, suggesting the pace of growth has not yet stalled. Reuters reported that Nvidia is forecasting roughly 70% revenue growth for the fiscal year ending January 2028, well above earlier expectations.
Huang also offered a blunt description of the shift underway. “AI has reached its inflection point,” he said. “Now, compute is revenue.”
That is important for investors because Nvidia is no longer selling chips only into an experimental AI market. The company is increasingly supplying the infrastructure needed to run commercial AI workloads at scale.
The Valuation Argument May Be the Biggest Surprise
NVDA is not a cheap stock. But Morgan Stanley argues investors should focus more on future earnings than the headline multiple.
The firm says Nvidia trades at about 15 times projected fiscal 2028 earnings. That valuation may leave room for further upside if estimates continue moving higher, particularly with management expecting another powerful growth phase.
The risks are still real. There is pressure on margins from memory, supply continues to be an issue, and there is the uncertainty of China. But Nvidia is against an even stronger growth comparison, with its base of revenues turning gigantic.
Nevertheless, it is Morgan Stanley's contention that the next spending on the AI cycle is underway without the market fully appreciating the scale.
What Does Wall Street Think About NVDA stock?
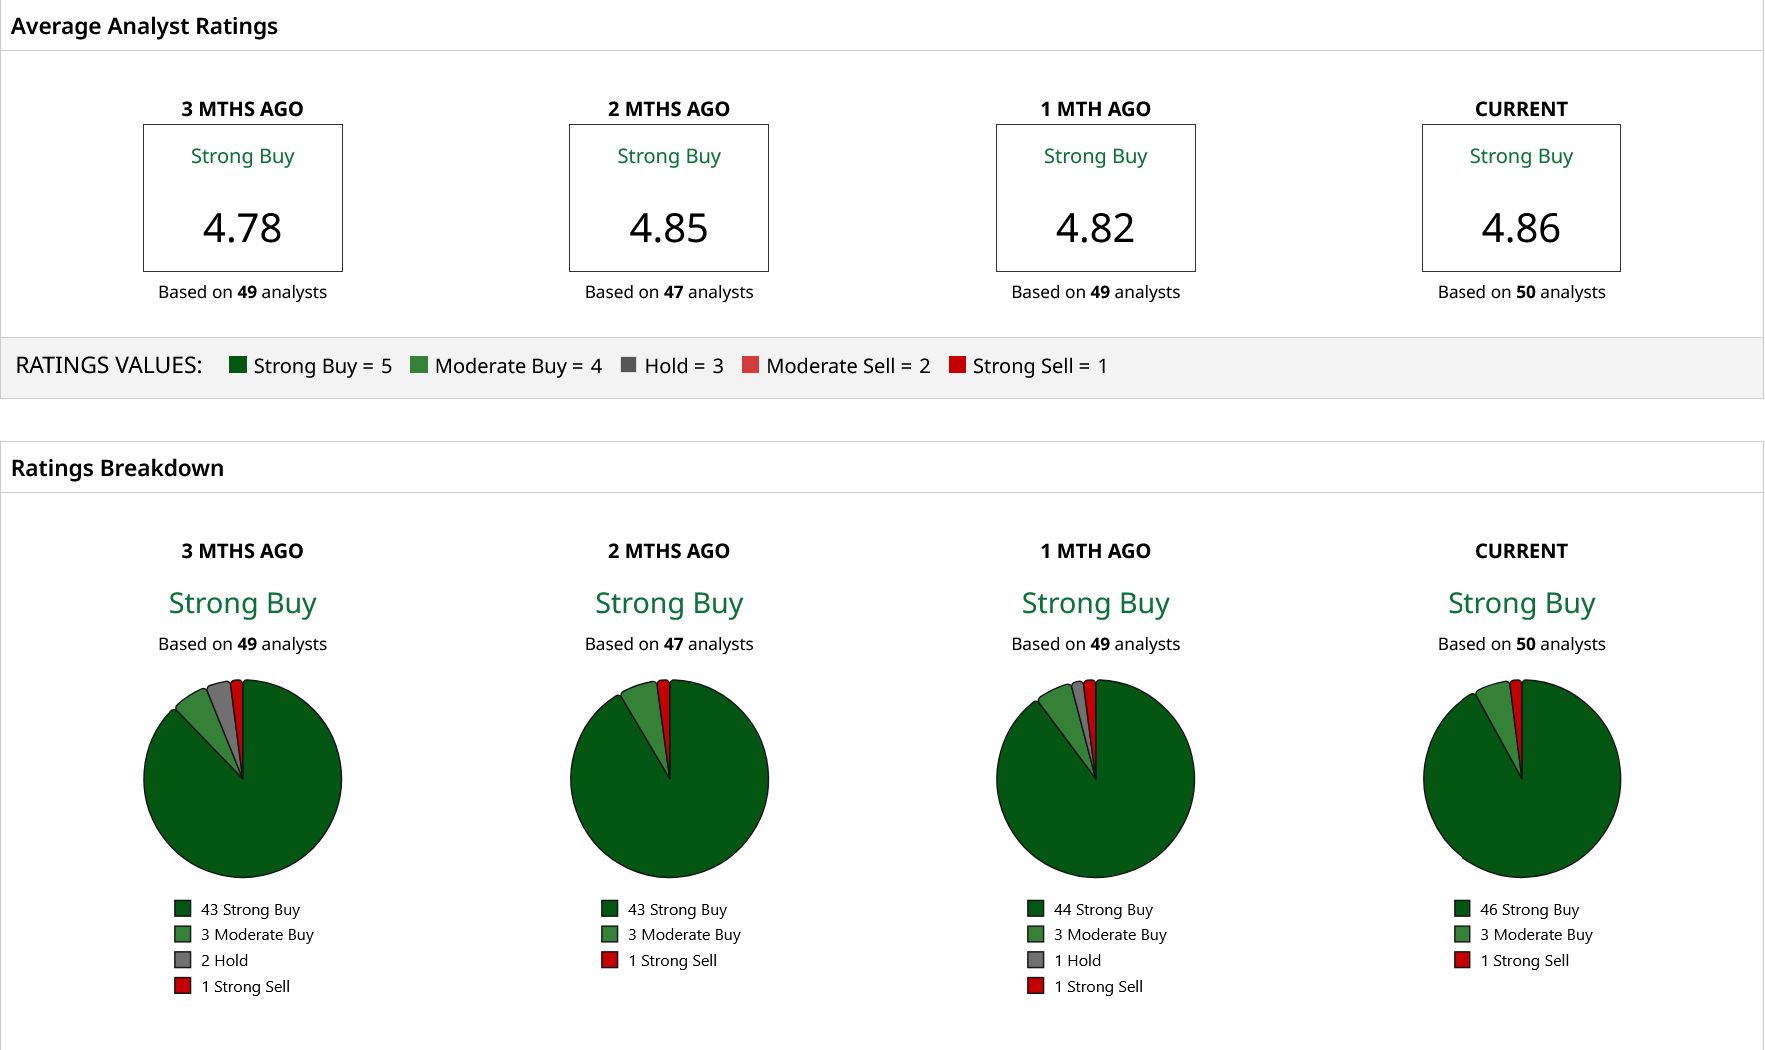
Wall Street remains heavily bullish on NVDA stock prospects.
Based on 48 analysts covering the stock, the consensus is “Strong Buy.” Moreover, the bullish group set an average price target of $324.7, implying about 39% upside from NVDA’s current price.
Morgan Stanley rates the shares “Overweight” with a $300 target. Moore’s team said Nvidia “remains very early in the ramp of a new product cycle,” while arguing that the stock’s roughly 15-times fiscal 2028 earnings valuation leaves room for appreciation.
That is the real takeaway from Morgan Stanley’s call: Nvidia may not need an entirely new AI story. It may simply need the current one to keep expanding.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘The Mission Is to Protect Retirees’: Billionaire Mark Cuban Calls a Viral Tax Post ‘Misleading,’ Because ‘Not All Investments Work’ Why This Top Bank Just Picked Nvidia as Its No. 1 Chip Stock This Analyst Just Upgraded Procter & Gamble Stock. Here's Why. Dear Tilray Stock Fans, Mark Your Calendars for October 8