

A. O. Smith Corporation (AOS), headquartered in Milwaukee, Wisconsin, manufactures and markets residential and commercial gas and electric water heaters, boilers, heat pumps, tanks, and water treatment products. With a market cap of $7.7 billion, the company specializes in offering innovative and energy-efficient solutions and products, which are developed and sold on a global platform. The leading global water technology company is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Oct. 29.
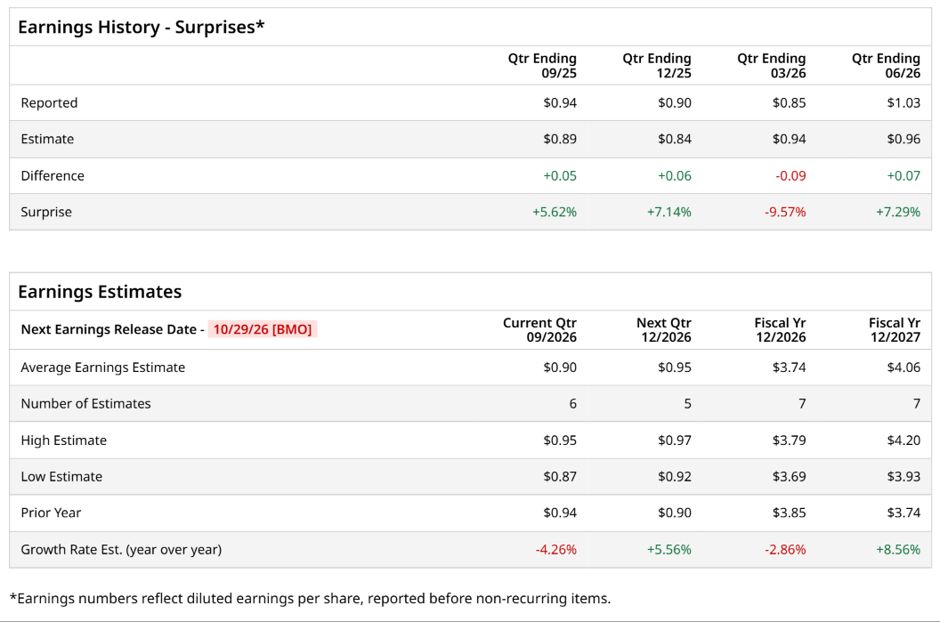
Ahead of the event, analysts expect A. O. Smith to report a profit of $0.90 per share on a diluted basis, down 4.3% from $0.94 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect A. O. Smith to report EPS of $3.74, down 2.9% from $3.85 in fiscal 2025. However, its EPS is expected to rise 8.6% year over year to $4.06 in fiscal 2027.
 www.barchart.com
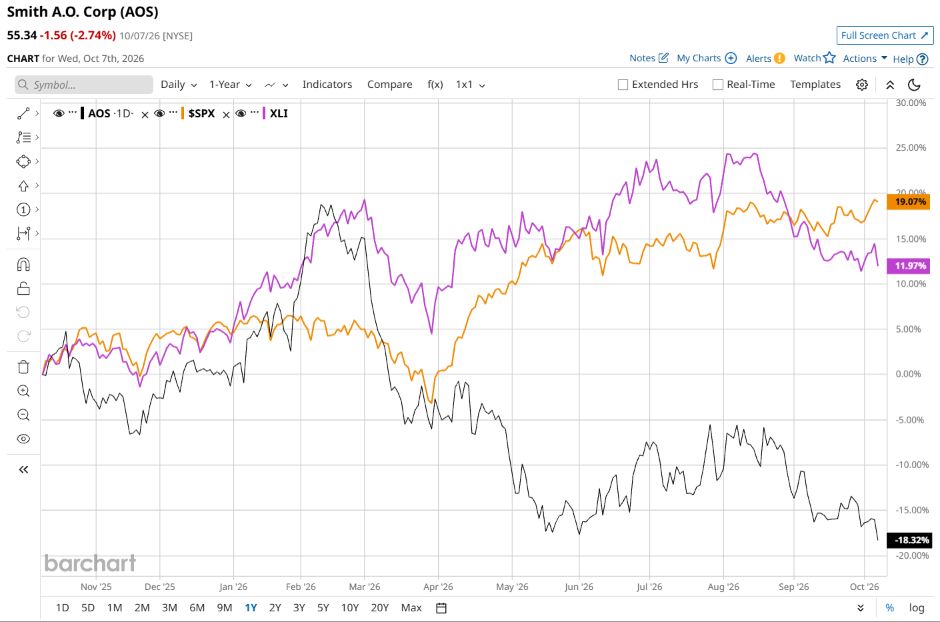
AOS stock has underperformed the S&P 500 Index’s ($SPX) 16.2% gains over the past 52 weeks, with shares down 22.5% during this period. Similarly, it underperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 8.8% gains over the same time frame.
 www.barchart.com
AOS underperformed as margin pressure and continued softness in China overshadowed flat sales and a profit beat. Strength in North America boilers on commercial demand and stabilizing share in residential water heaters was offset by higher input costs and weak China and water treatment sales. Management lowered the residential outlook, flagged demand and tariff headwinds, and plans to complete a strategic review of China next quarter alongside a CFO transition.
On Jul. 30, AOS shares closed down by 3.6% after reporting its Q2 results. Its adjusted EPS of $1.03 topped Wall Street expectations of $0.96. The company’s revenue was $1 billion, beating Wall Street forecasts of $986.4 million. AOS expects full-year adjusted EPS in the range of $3.70 to $3.85.
Analysts’ consensus opinion on AOS stock is cautious, with a “Hold” rating overall. Out of 13 analysts covering the stock, four advise a “Strong Buy” rating, seven give a “Hold,” and two recommend a “Strong Sell.” AOS’ average analyst price target is $69, indicating a potential upside of 24.7% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
These 3 Catalysts Make Microsoft Stock a Bargain Before Year-End GE Vernova Isn’t an AI Stock. It’s the Reason AI Stocks Work. There’s 1 Problem Standing Between ASML Stock and a Breakout. October 14 Will Reveal the Answer. This Insurance Stock Just Raised Its Dividend by More Than 10%