

United Microelectronics (UMC) has carved out a strong position in the global semiconductor foundry market, particularly in mature and specialty nodes. These chips serve a broad range of industries and are gaining more importance as foundry demand rebounds, and the rapid expansion of artificial intelligence (AI) infrastructure creates additional demand for specialty chips.
United Microelectronics’ share price has already reflected much of the improvement. The stock has jumped 177.7% over the past two years, and the latest sales figures gave investors another reason to stay interested. September revenue reached NT $25.35 billion ($797.3 million), up 27.22% from a year earlier, after revenue grew 30.71% in August.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Through the first nine months, revenue was up 16.08%, which is a fairly healthy handoff into the final quarter, as growth has not simply spiked and faded. The stock, however, fell 6.2% over the past five trading sessions, largely as investors weighed the company’s $1.8 billion convertible-bond offering.
The deal gives United Microelectronics more money to expand capacity, but convertible debt can also mean dilution for existing shareholders. After such a large run-up, that is not a minor detail. So, let us now see how to play the stock.
About United Microelectronics Stock
United Microelectronics, based in Hsinchu City, Taiwan, is a semiconductor wafer foundry that manufactures integrated circuits. The company has a market cap of nearly $60.2 billion and provides services spanning circuit design, mask tooling, wafer fabrication, assembly, and testing.
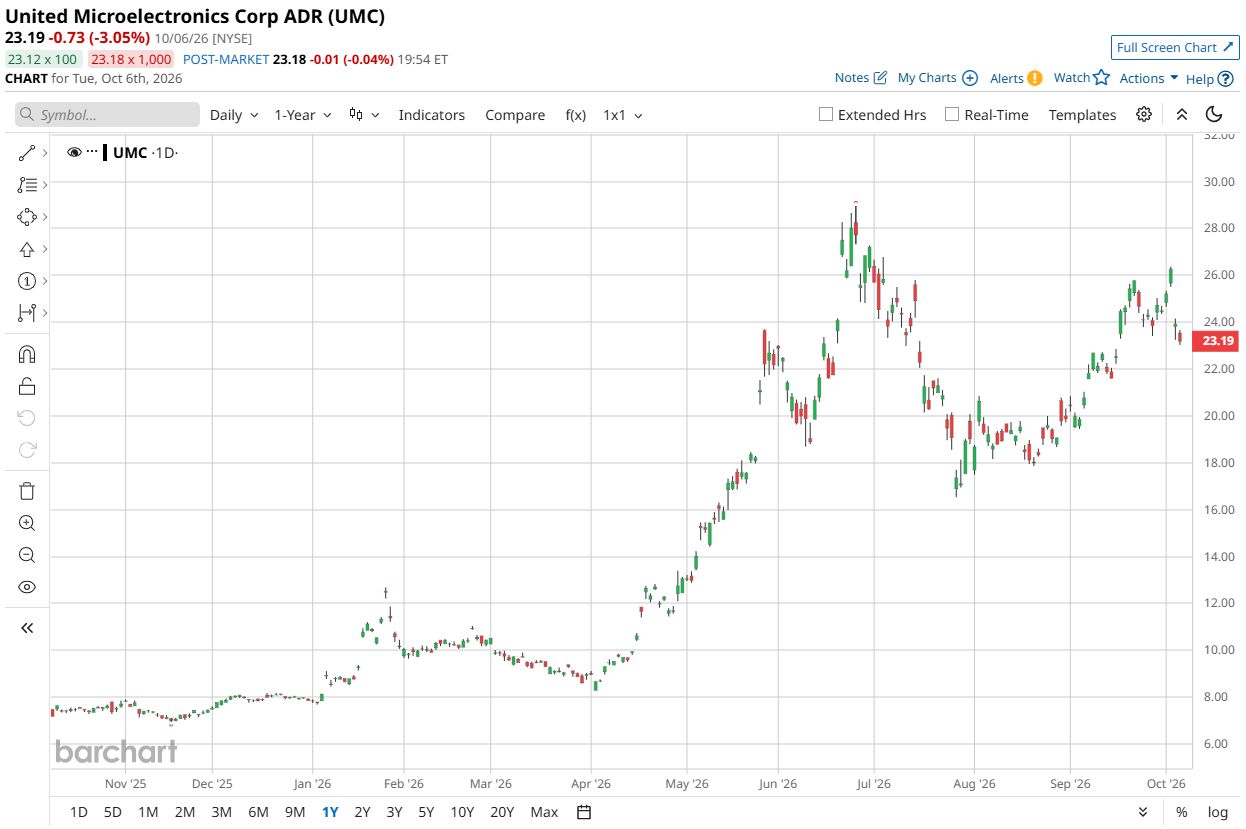
UMC’s stock performance has been even stronger over the shorter term. Shares have risen 215.5% over the last 52 weeks and are up 195% in 2026. The recent momentum has not disappeared either, with the stock rising 11.7% in just the last month.
 www.barchart.com
The valuation is where the numbers start asking tougher questions. UMC stock is currently trading at 26.05 times forward adjusted earnings and 6.83 times sales. Both figures are above the industry averages and UMC’s own five-year historical averages. Investors are therefore paying more for each dollar of expected earnings and sales than they have historically paid for the company.
There is also a dividend in the mix. United Microelectronics pays $0.40 per share annually, giving the stock an annual dividend yield of 1.68%. The company’s most recent dividend was $0.40 per share, paid on Thursday, Aug. 6 to shareholders of record as of Wednesday, Jul. 8.
A Closer Look at United Microelectronics’ Q2 Earnings
On July 29, the company reported its Q2 FY2026 earnings results, after which the stock climbed 10.7% in the following trading session. Revenue rose 17% year over year (YOY) to $2.2 billion, while wafer shipments increased 10.6% quarter-on-quarter (QOQ) as demand improved across communications and consumer electronics, and capacity utilization reached 85%.
The improvement also showed up in the margins. Gross margin rose 32.5% YOY, and operating margin reached 21.8%. Gross profit climbed 32.3% from the year-ago value to $707 million, growing faster than revenue. With factories running at better utilization rates, UMC was able to squeeze more profit from the additional sales.
Expenses were higher, however. Operating expenses increased 22.2% YOY to $250 million. General and administrative costs rose 44.2%, while R&D expenses increased 13.2%. Even with those increases, operating income grew faster than revenue. In practical terms, the improvement in factory utilization more than made up for the heavier cost burden.
Net income jumped 377.2% from the previous year’s period to $1.4 billion, while earnings per ADS came to $0.537, adding another strong figure to a quarter that showed a broad improvement in UMC’s financial performance.
Management has increased its 2026 capital-expenditure budget to $2 billion. The additional spending will expand capacity in Singapore and Taiwan, with the company looking to meet sustained demand, particularly from AI-related applications.
Analysts are expecting further earnings growth as well. Q3 FY2026 EPS is forecasted to increase 15% YOY to $0.23. For full-year FY2026, analysts expect EPS to climb 132.1% from the previous year to $1.23.
What Do Analysts Expect for United Microelectronics Stock?
The cautious view on United Microelectronics is largely tied to the stock’s valuation and the challenge of delivering enough growth after such a powerful rally. Semiconductor demand is improving, revenue growth remains strong, and utilization is heading higher. Those are useful arguments for the bulls.
But the share price has already moved sharply, which means investors now need the business to keep delivering at a high level. Competition is another consideration, as is the possibility that earnings growth may not keep up with the expectations built into the stock.
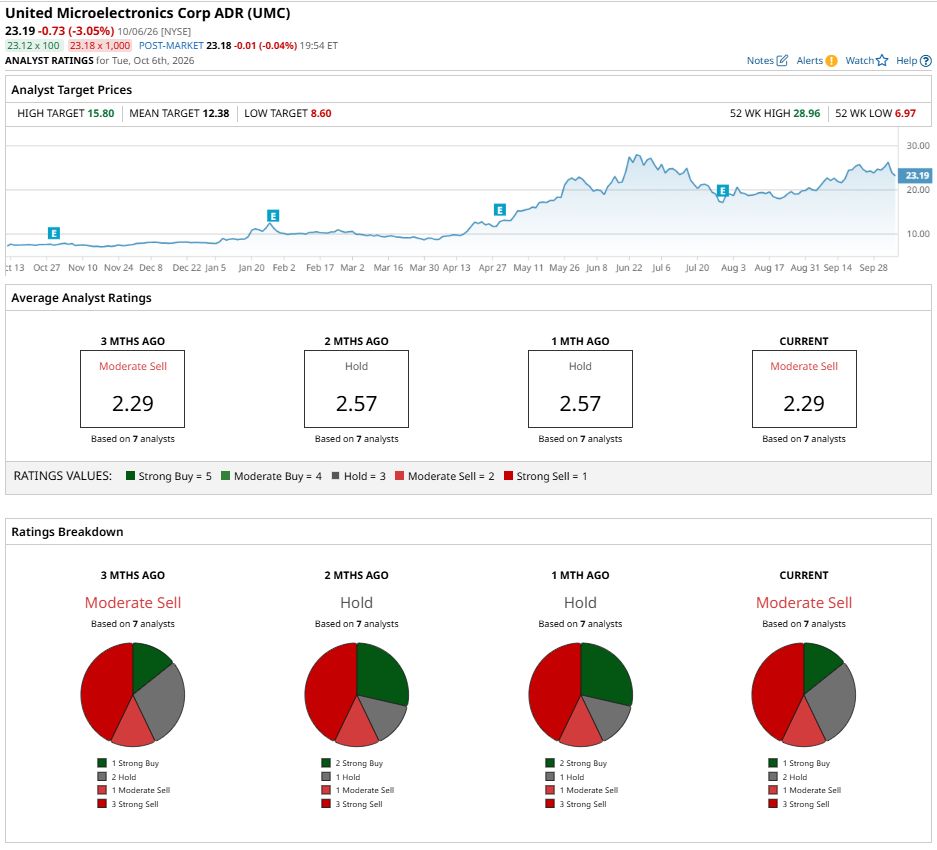
That helps explain Wall Street’s overall “Moderate Sell” rating. Among seven analysts currently covering the name, one rates it a “Strong Buy,” two have a “Hold” rating, one has a “Moderate Sell,” and three rate it a “Strong Sell.”
Price targets are hardly screaming bargains, either. UMC stock is already trading above the average analyst price target of $12.38 and even sits above the Street-high target of $15.80.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
TSMC Could Partner with Elon Musk’s Terafab. How Intel Stock Could Lose Big. How to Play United Microelectronics Stock as Revenue Surges U.S. Stock Futures Slump as Oil Prices and Bond Yields Surge These 3 Catalysts Make Microsoft Stock a Bargain Before Year-End