

With a market cap of about $74.9 billion, Florida-based Royal Caribbean Cruises Ltd. (RCL) operates some of the world’s best-known cruise brands, including Royal Caribbean International, Celebrity Cruises, Azamara, and Silversea Cruises. The cruise operator is expected to report its fiscal third-quarter earnings for 2026 in the near future.
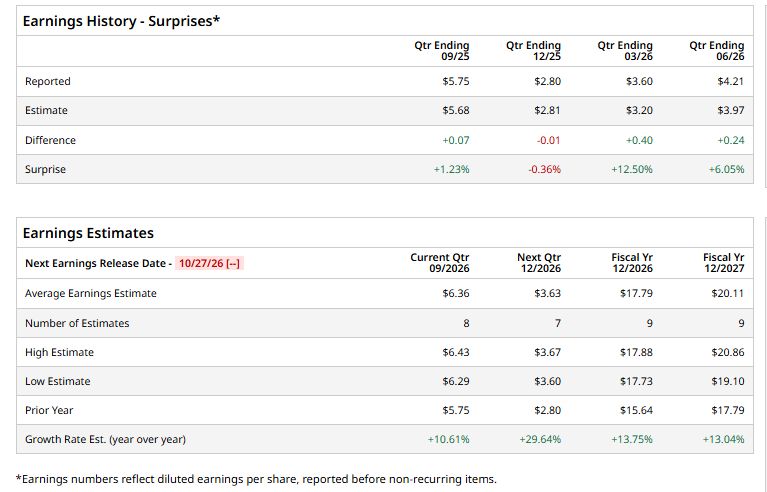
Wall Street is heading into the report with an upbeat outlook. Analysts expect RCL to post a profit of $6.36 per share, representing a 10.6% increase from $5.75 per share in the year-ago quarter. The company has topped consensus estimates in three of the past four quarters and missed the forecast just once.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The growth story is expected to continue beyond the upcoming quarter. Analysts project fiscal 2026 EPS of $17.79, up 13.8% from $15.64 in fiscal 2025, while fiscal 2027 earnings are expected to climb another 13% to $20.11 per share.
 www.barchart.com
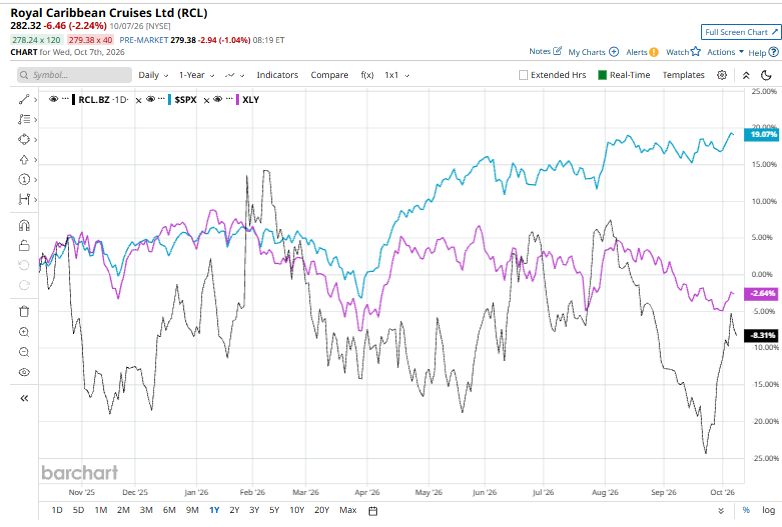
RCL stock has underperformed the S&P 500 Index’s ($SPX) 16.2% gains over the past 52 weeks, with shares up 10.3% during this period. However, it has outperformed the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 5.5% fall over the same time frame.
 www.barchart.com
RCL shares popped 7.5% on Sept. 29, after Deutsche Bank analyst Chris Woronka upgraded Royal Caribbean to “Buy” and set a $299 price target, arguing that the stock’s recent selloff has been overdone and that shares could now move higher. RCL has fallen more than 20% from its early-August peak, pressured by concerns over higher oil prices and potential weakness in cruise demand.
However, Woronka believes those fears are overstated, noting that fuel represents only about 7% of revenue, while strong results from rivals suggest cruise operators can pass higher fuel costs on to customers amid resilient demand.
Investor sentiment around RCL remains firmly positive, with the analyst consensus carrying a “Strong Buy” rating. Of the 26 analysts covering the stock, 19 rate it a “Strong Buy,” one recommends a “Moderate Buy,” and six give a “Hold” rating. The optimism is reflected in the average price target of $351.65, which implies roughly 24.6% upside from current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
BofA Just Sent a Warning Shot for Apple Investors Why Nvidia Stock Is Worth Buying Before It Touches $327 Dear JPMorgan Stock Fans, Mark Your Calendars for Oct. 13 How to Play Rubrik Stock at New All-Time Highs