

Moody’s Corporation (MCO), with a market capitalization of approximately $77.9 billion, is a global financial intelligence company headquartered in New York. It provides credit ratings, research, data, analytics and decision solutions that help organizations assess risk and make informed decisions.
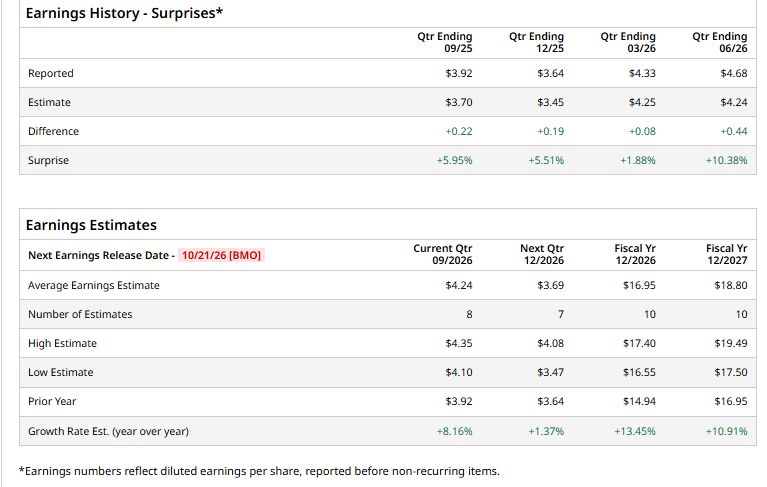
MCO is set to report its Q3 earnings on Wednesday, October 21, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of $4.24, up 8.2% from $3.92 in the year-ago quarter. Moreover, MCO has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect MCO to report EPS of $16.98, reflecting a 13.5% increase from $14.94 in fiscal 2025. EPS is projected to increase another 10.9% year over year to $18.80 in fiscal 2027.
 www.barchart.com
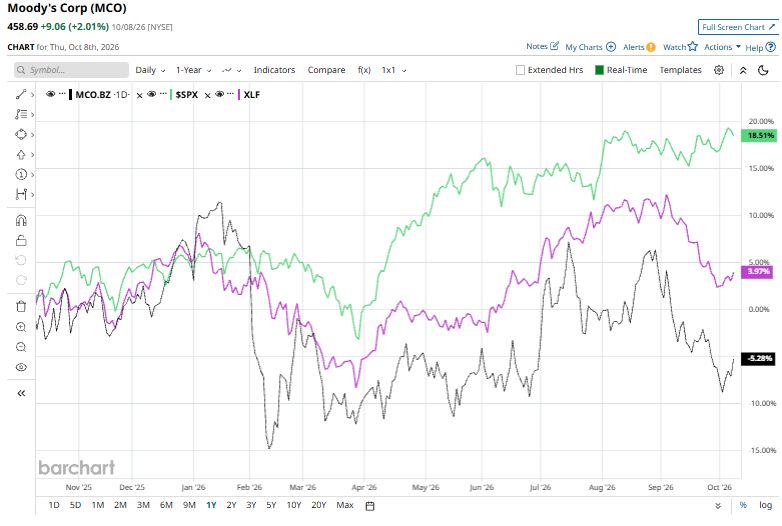
MCO stock has declined 6.4% over the past 52 weeks, underperforming both the S&P 500 Index ($SPX), which returned 15%, and the State Street Financial Select Sector SPDR ETF (XLF), which posted a 1.4% gain over the same period.
 www.barchart.co
Moody’s stock has underperformed the broader market over the past year amid debt-market uncertainty and a more cautious cash-flow outlook. In April 2026, Reuters reported that market volatility, private credit concerns and geopolitical uncertainty were weighing on investor sentiment despite strong earnings growth. More recently, Moody’s lowered its full-year operating cash flow guidance to $3.15 billion to $3.35 billion from $3.25 billion to $3.45 billion and its free cash flow outlook to $2.7 billion to $2.9 billion from $2.8 billion to $3.0 billion, adding to concerns about its cash generation.
Analysts remain cautiously bullish on MCO, with the stock carrying a consensus "Moderate Buy" rating. Of the 25 analysts covering the stock, 17 recommend a "Strong Buy," one rates it a "Moderate Buy," and seven recommend a "Hold." Meanwhile, MCO’s average price target of $560.09 implies a 22.1% premium over the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Big Tech Needs Power. Constellation Just Found a $1 Billion Buyer in Google. Uber’s ezCater Acquisition Looks Like a Smart Move to Diversify Revenue Streams Amazon Stock Has Been Flat for the Past Month, But AMZN Put Credit Spreads Have Worked Out Well HPE Stock Has Nearly Tripled. Here’s Why Wall Street Expects It to Reach $92.