

Valued at $37.8 billion by market capitalization, Sysco Corporation (SYY) is a major force in the global food-service supply chain and a key player in the consumer staples sector. Headquartered in Houston, Texas, the company keeps restaurants, hotels, hospitals, schools, and other food-service operators running by distributing an extensive range of products, from fresh produce, meat, seafood, dairy, and frozen foods to beverages, imported specialties, kitchen equipment, and cleaning supplies.
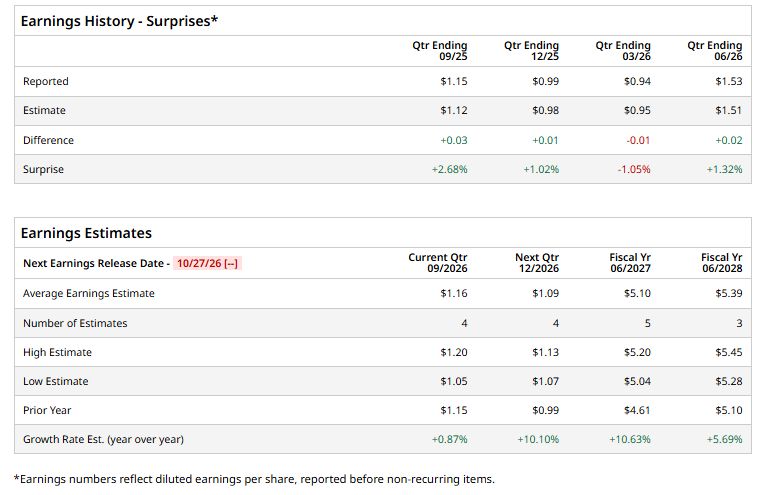
The food-service giant is gearing up to report its fiscal first-quarter earnings soon. Analysts expect Sysco to deliver diluted EPS of $1.16, edging up marginally from $1.15 per share in the same quarter last year. Sysco has also shown a mixed earnings track record, beating consensus in three of the past four quarters but missing once.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Looking ahead, analysts expect earnings growth to gather momentum, projecting fiscal 2026 EPS of $5.10, up 10.6% from $4.61 in fiscal 2025. For fiscal 2027, earnings are forecast to climb another 5.7% to $5.39 per share.
 www.barchart.com
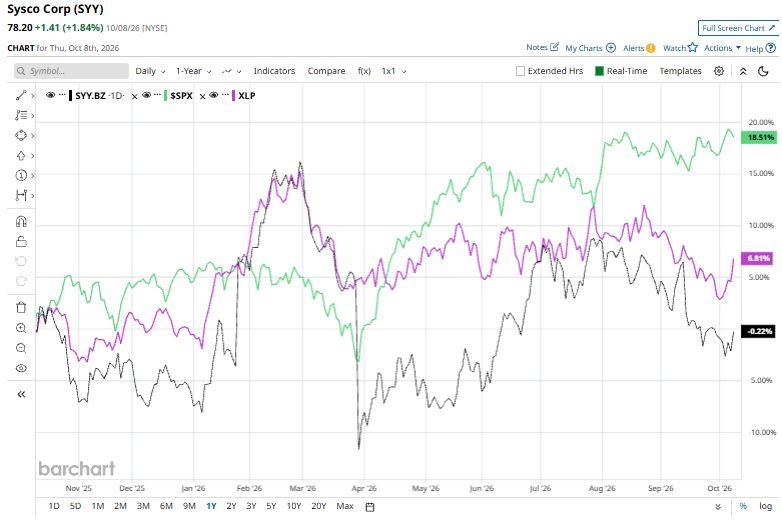
SYY stock has plummeted marginally over the past year, trailing the S&P 500 Index’s ($SPX) 15% gains and the State Street Consumer Staples Select Sector SPDR Fund’s (XLP) 7.2% rise over the same time frame.
 www.barchart.com
Sysco has trailed the broader market over the past year as slow sales growth and mounting concerns over capital efficiency have weighed on its performance. Despite serving more than 730,000 commercial kitchens across North America and Europe, the food distributor has struggled to translate steady demand into stronger growth, with unit sales averaging just 0.9% over the past two years. Expectations for stagnant free cash flow margins and diminishing returns on capital have further fueled concerns about its ability to drive profitable growth and generate stronger shareholder returns.
Analysts’ consensus opinion on SYY stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 14 analysts covering the stock, six advise a “Strong Buy” rating, seven give a “Hold,” and one “Strong Sell.” SYY’s average analyst price target is $90.82, indicating a potential upside of 16.1% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Big Tech Needs Power. Constellation Just Found a $1 Billion Buyer in Google. Uber’s ezCater Acquisition Looks Like a Smart Move to Diversify Revenue Streams Amazon Stock Has Been Flat for the Past Month, But AMZN Put Credit Spreads Have Worked Out Well HPE Stock Has Nearly Tripled. Here’s Why Wall Street Expects It to Reach $92.