

With a market cap of $57.4 billion, AMETEK, Inc. (AME) is a global leader in industrial technology solutions, serving diverse niche markets. Guided by its AMETEK Growth Model, the company drives sustainable growth through operational excellence, technology innovation, global expansion, strategic acquisitions, and disciplined capital deployment.
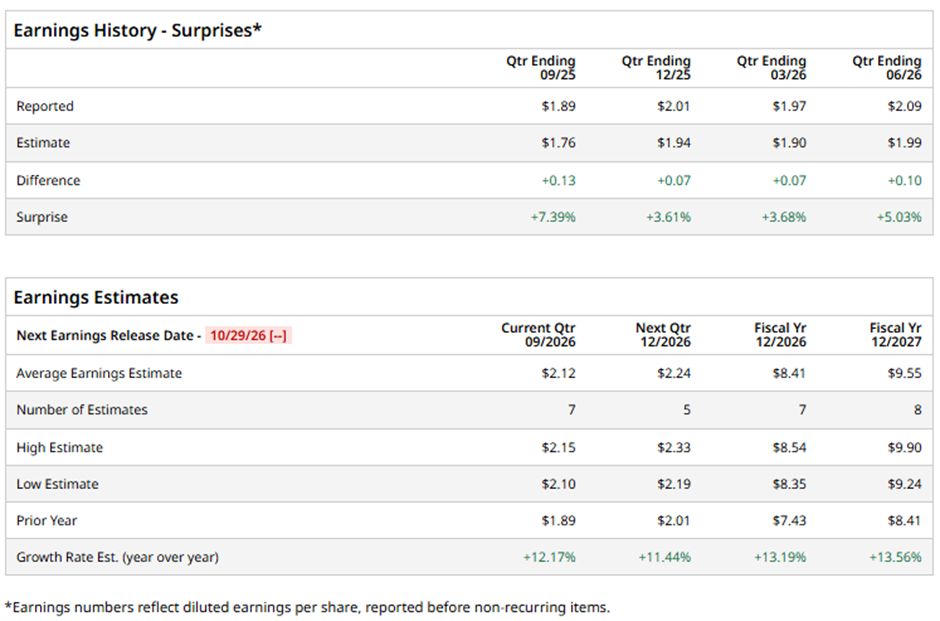
The Berwyn, Pennsylvania-based company is scheduled to release its fiscal Q3 2026 results soon. Ahead of this event, analysts expect AME to report an adjusted EPS of $2.12, up 12.2% from $1.89 in the previous year's quarter. The company has surpassed Wall Street's bottom-line estimates in each of the past four quarters.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts project AMETEK to post adjusted EPS of $8.41, up 13.2% from $7.43 in fiscal 2025. Moreover, adjusted EPS is projected to grow 13.6% year-over-year to $9.55 in fiscal 2027.
 www.barchart.com
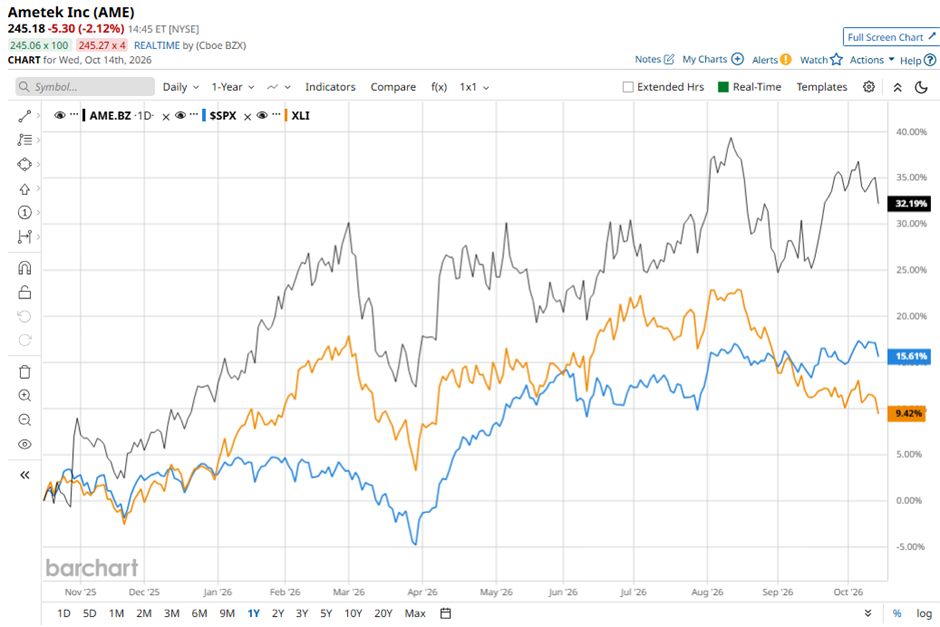
AME stock has increased 32.1% over the past 52 weeks, outpacing both the S&P 500 Index's ($SPX) 15.9% rise and the State Street Industrial Select Sector SPDR ETF's (XLI) 8.2% return over the same period.
 www.barchart.com
AMETEK shares rose 4.2% on Aug. 4 after the company reported record Q2 2026 results, with sales increasing 15% year-over-year to $2.04 billion and adjusted EPS rising 17% to a record $2.09, surpassing the prior-year performance. Investor sentiment was further boosted by exceptional order growth of 28% for the second consecutive quarter, an 18% increase in adjusted operating income to a record $544.4 million, operating margins expanding to 26.6%, and operating cash flow climbing 35% to $483.7 million.
The rally was reinforced by AMETEK raising its 2026 adjusted EPS guidance to $8.20 - $8.30, implying 10% - 12% growth, while projecting approximately 10% annual sales growth and highlighting strong demand across semiconductor, commercial aerospace, medical technology, defense, and automation markets.
Analysts' consensus rating on AME stock is cautiously optimistic, with an overall "Moderate Buy" rating. Out of 21 analysts covering the stock, opinions include 14 "Strong Buys," one "Moderate Buy," and six "Holds." This configuration is slightly more bullish than three months ago, with 13 analysts suggesting a "Strong Buy."
The average analyst price target is $281.16, suggesting a 14.7% potential upside from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Hold, Roll, or Close? The Options Chart Too Many Traders Ignore. A $450 Reason to Buy Alibaba Stock Ahead of Taiwan Semiconductor Earnings, Here's What Barchart Data Says Comes Next for TSM Stock Forget Becoming the Next Tesla, Lucid Group Stock Has Been a Bottomless Pit