

Apple (AAPL) is reportedly asking several key suppliers to scale back component production for its flagship devices, as higher retail prices driven by rising memory chip costs appear to be cooling consumer demand. And if iPhone sales lose steam, the ripple effects could reach far beyond Apple itself.
Take Cirrus Logic (CRUS), for instance. The semiconductor company relies heavily on Apple, which contributes the lion’s share of its revenue, according to KeyBanc Capital Markets analyst John Vinh. With Apple reportedly taking a more cautious approach to iPhone production, Vinh sees a risk that unit sales could stay flat or slip slightly in 2027, dampening Cirrus Logic’s growth prospects. That concern prompted him to downgrade CRUS stock, adding to the pressure on shares.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Cirrus supplies custom audio and mixed-signal chips used in smartphones, making it particularly sensitive to changes in Apple’s production plans. With its potential PC growth opportunity also facing delays, investors have more than one reason to pay attention. So, if Apple trims iPhone production in 2027, could Cirrus Logic be among the biggest losers? Let’s take a closer look.
About Cirrus Logic Stock
Founded in 1984, Cirrus Logic is a fabless semiconductor company headquartered in Austin, Texas, with offices across the United States, Europe, and Asia. The company designs high-performance analog, mixed-signal, and audio digital signal processing (DSP) integrated circuits used in smartphones, tablets, laptops, smartwatches, automotive entertainment systems, and other consumer electronics.
Its product portfolio includes smart codecs, amplifiers, haptics and sensing solutions, camera controllers, and battery and power ICs. With approximately 1,717 employees worldwide, Cirrus Logic focuses on power efficiency, audio quality, and innovative chip designs. The company has a market capitalization of around $5.4 billion.
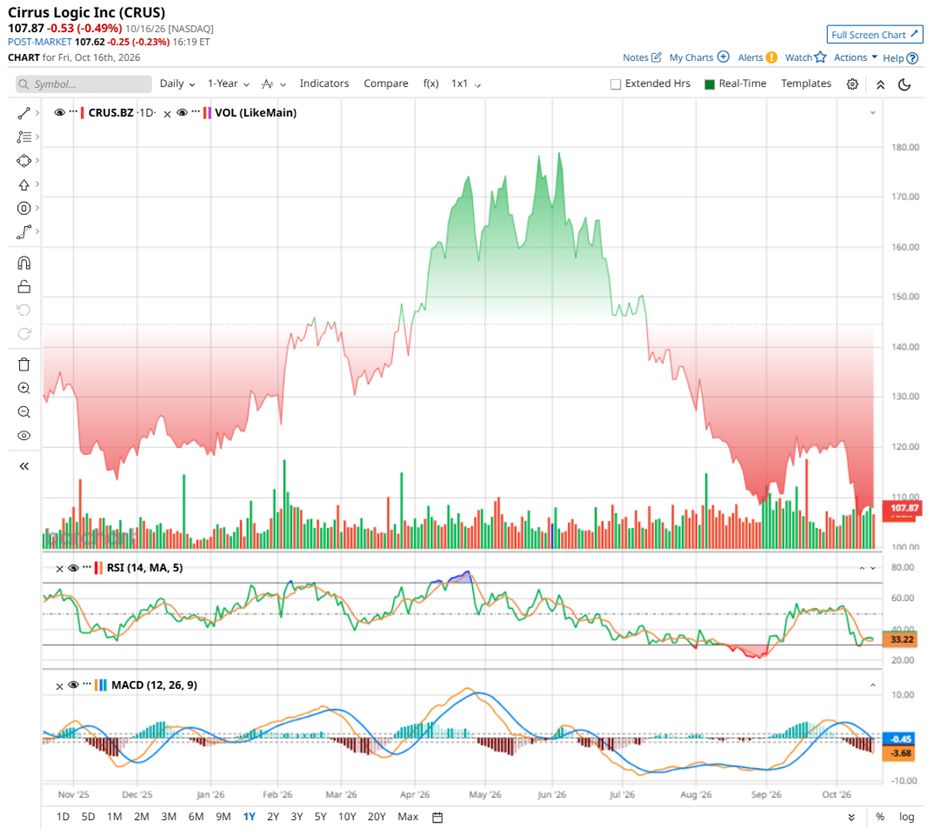
Cirrus Logic's stock started the year on a high note, climbing to $180.42 in May 2026 as strong fiscal 2026 results and optimism around the semiconductor sector gave investors plenty to cheer about. But that enthusiasm has since faded. By Oct. 15, shares had tumbled to a 52-week low of $105.10, down 40% from their peak. CRUS stock has lost 14% over the past year and 35% over six months, with recent losses reflecting softer PC market expectations and concerns about its heavy reliance on Apple, its largest customer.
Things got more interesting after Cirrus announced its acquisition of Italy-based INVENTVM Semiconductor on Oct. 6. The deal aims to expand its technology portfolio and reach new markets, but the financial terms remain undisclosed, and management expects no material revenue impact. That may explain why investors have not warmed up to the deal just yet, as they weigh its long-term potential against the lack of an immediate financial boost.
Technically, CRUS stock shows signs of stabilization, but the picture remains shaky. The 14-day RSI has bounced back from oversold territory to around 34, though it is still below the neutral mark. Meanwhile, the MACD line remains below its signal line, with a negative histogram pointing to continued bearish momentum.
On the valuation front, CRUS stock looks relatively affordable, trading at 12.88 times forward adjusted earnings and 2.68 times forward sales. Both multiples sit below the stock’s five-year averages and those of its sector peers, making its current valuation worth a closer look.
 www.barchart.com
A Closer Look at Cirrus Logic’s Q1 Earnings Report
In August, Cirrus Logic released its Q1 2027 earnings report and started the year on a strong note, posting record first-quarter revenue and earnings. That’s largely due to healthy demand for custom chips used in premium smartphones. The company also made progress on its broader growth plans, although its PC business faced a few speed bumps.
Revenue rose 12.9% year-over-year (YoY) to $460 million, almost in line with Wall Street’s expectations. Sales also increased 2.5% sequentially as stronger shipments of smartphone components lifted results. Demand for custom-boosted amplifiers and smart codecs remained strong, helping the company deliver record quarterly earnings. Adjusted EPS climbed 21.9% annually to $1.84, beating analysts’ estimates. However, previously anticipated pricing reductions partly offset the revenue gains. Cirrus remains heavily reliant on its biggest customer, Apple, which accounted for 90% of first-quarter revenue.
Beyond smartphones, Cirrus is working to expand its footprint in AI-enabled PCs and other markets. Interest in its latest low-power smart codec for AI PCs remains strong, with multiple customers working on designs expected to launch next calendar year. However, supply constraints involving a key industry platform, memory and other components, along with delayed PC launches, have pushed expected growth further out.
As a result, management lowered its fiscal 2027 PC revenue expectations, describing the challenges as timing issues rather than a change in the long-term opportunity. Several customers have also announced PCs based on Nvidia’s (NVDA) RTX Spark platform that are expected to ship later this year with Cirrus amplifiers and codecs.
The company is also advancing its next-generation camera controller and smart power IC for 3D sensing, while a newly taped-out high-performance analog front-end component targeting metrology applications adds to its general market portfolio.
Cirrus ended the quarter with $1.2 billion in cash and investments and no debt. Operating cash flow reached $64.1 million, while free cash flow came in at $48.6 million, representing an 11% margin. The company repurchased about 211,000 shares for $34.5 million during the quarter and bought another 359,000 shares for $50.5 million after quarter-end. Management continues to prioritize investments in the business, followed by acquisitions and share buybacks, with no near-term dividend planned.
Looking ahead, Cirrus expects Q2 revenue between $510 million and $570 million, with the midpoint implying 17% sequential growth but roughly 4% YoY decline. GAAP gross margin is projected at 52% to 54%. While smartphone demand remains a key support, investors will be watching whether Cirrus can turn its growing AI-PC pipeline into meaningful revenue as supply constraints ease.
Cirrus Logic is gearing up to report its second-quarter fiscal 2027 results on Wednesday, Nov. 4, after the closing bell, and Wall Street will be watching to see how the chipmaker is holding up. Analysts expect revenue to come in at around $540.4 million, while EPS is projected to slip nearly 16% YoY to $2.11. Looking further ahead, fiscal 2027 earnings are expected to fall 8.9% annually to $7.24 per share. There could be some relief in fiscal 2028, though, with EPS projected to rebound 4.7% YoY to $7.58.
What Do Analysts Think About CRUS Stock?
KeyBanc downgraded CRUS stock to a “Sector Weight” from an “Overweight,” citing its heavy reliance on Apple and delayed diversification prospects. Analyst John Vinh noted that Apple’s cuts to TSMC (TSM) wafer starts, equivalent to 15 million to 20 million iPhones, suggest weaker iPhone volumes in 2027.
With roughly 90% of Cirrus Logic’s revenue tied to Apple, Vinh sees limited growth over the next six to 12 months. Meanwhile, elevated memory prices and an expected 10% to 15% decline in PC shipments this year could delay its PC diversification plans, despite meaningful share gains in the segment. KeyBanc also questioned Cirrus’ unsuccessful Synaptics (SYNA) acquisition bid from a strategic standpoint.
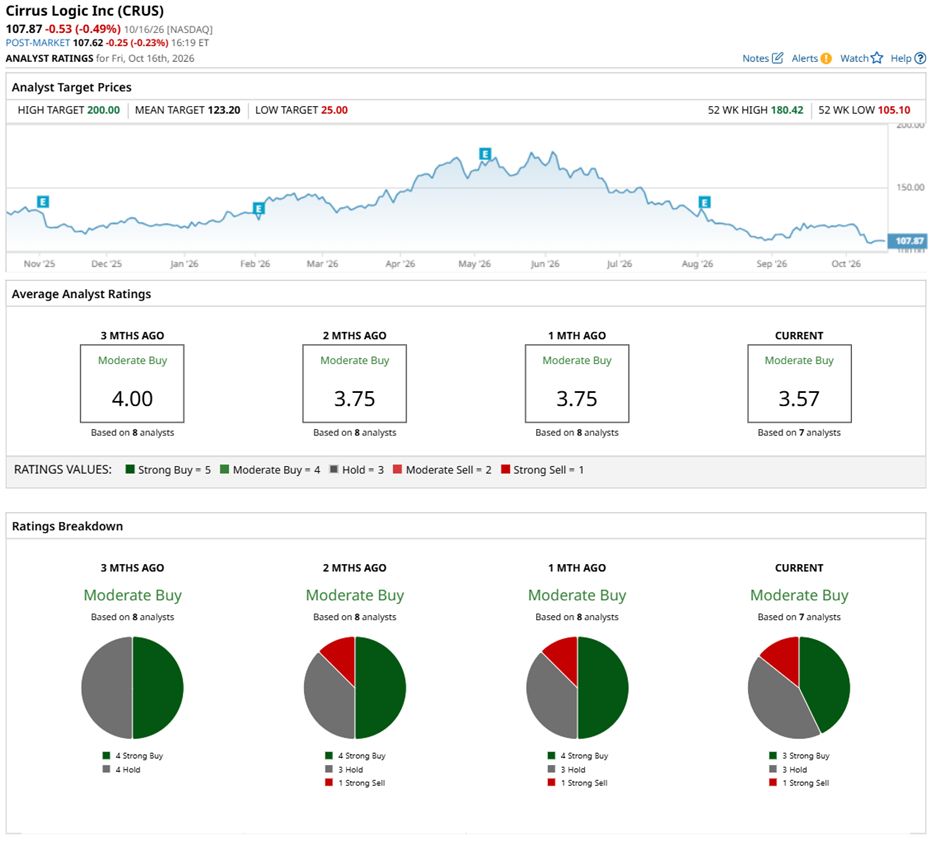
Analysts have been moderately bullish about Cirrus Logic, with seven who cover the stock giving a consensus “Moderate Buy” rating. Among them, three suggest a “Strong Buy,” three are playing it safe with a “Hold” rating, while the remaining one has a “Strong Sell.”
The mean price target of $123.20 indicates CRUS has an upside potential of 13%, and the high target of $200 suggests that the stock could rise as much as 83% from the current price level.
 www.barchart.com
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
If Apple Cuts iPhone Units in 2027, This Stock Could Be a Big Loser How a Possible Dead-Cat Bounce May Trigger a 135% Options Payout for Baidu (BIDU) Stock Dear MicroStrategy Investors, Mark Your Calendar for November 11 Taiwan’s President Called on Micron and Workers to Negotiate Ahead of a Possible Strike. Here’s What to Know.