

Salesforce (CRM) just dropped some big news. The software giant said that it is buying customer engagement platform Braze (BRZE) for $5.66 billion. Braze shareholders get $47.50 a share in cash. That is a fat 58% premium. BRZE stock shot up 50% right after the news. On the other hand, CRM stock barely budged. It actually slipped a fraction on the day.
So here is the big question for investors. Is this deal a smart move that makes Salesforce a buy? Or is it just another pricey acquisition that muddies the story? Let us dig in. We will look at the Braze logic and the latest numbers. Then you can decide if CRM deserves a spot in your portfolio.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
A Rough Year for Salesforce Stock
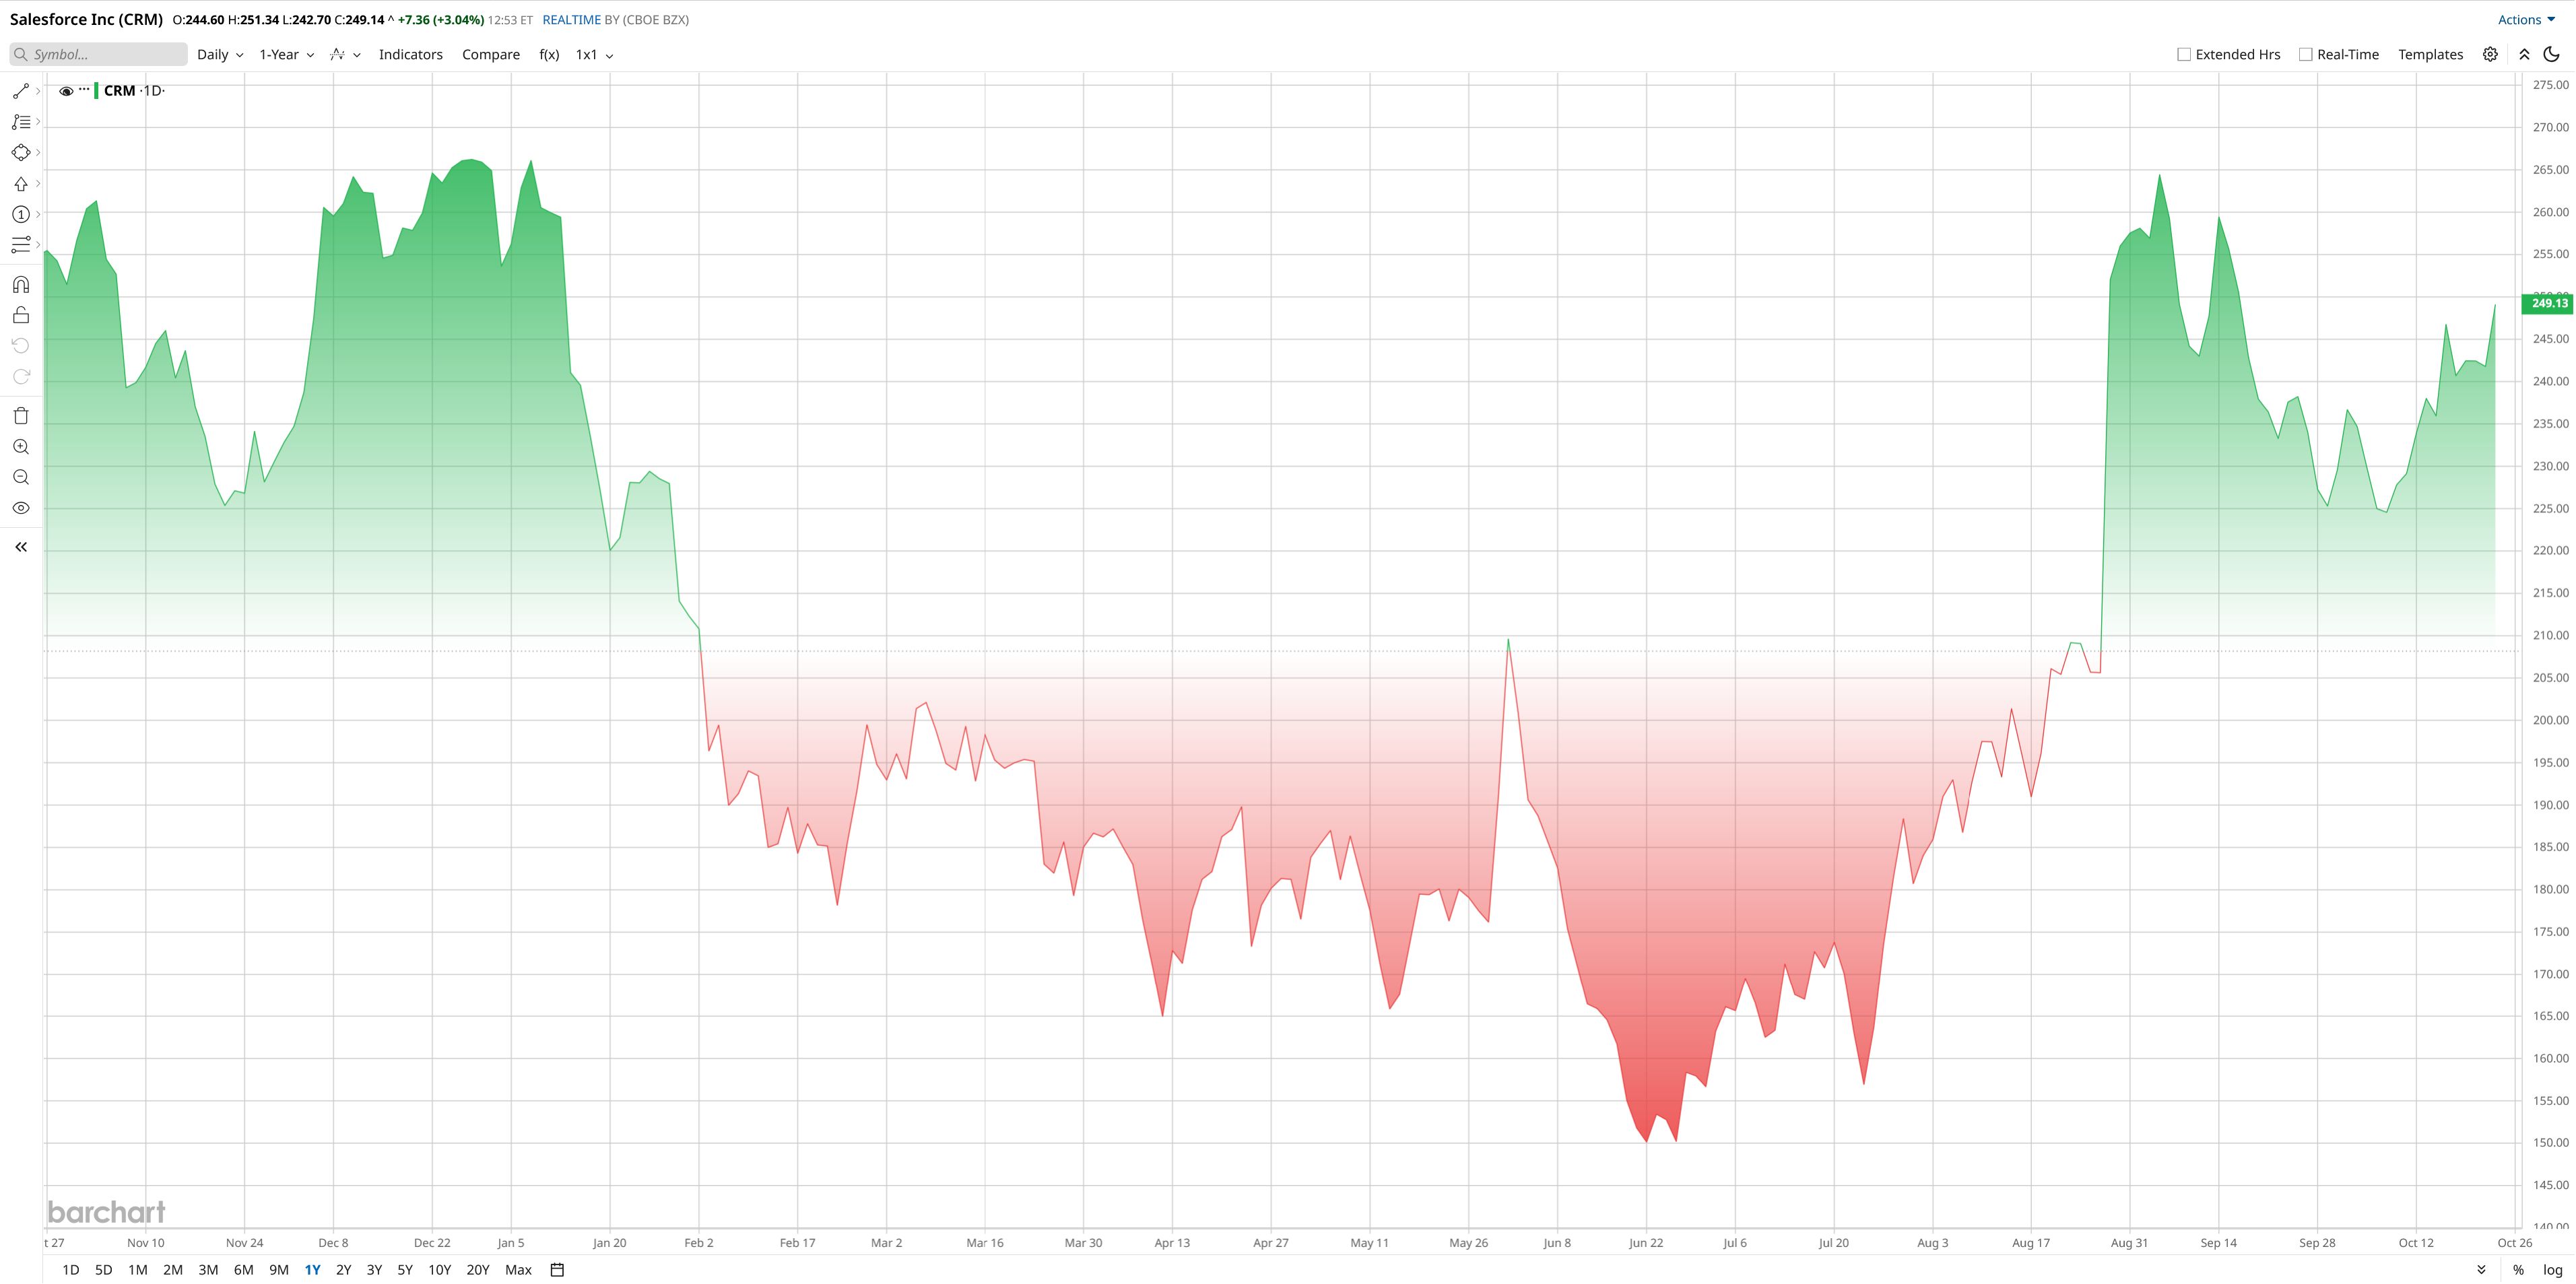
Salesforce's stock has not been a market darling lately. Shares are down about 5% so far in 2026. The one-year return isn't much better. It sits slightly negative while the S&P 500 Index ($SPX) climbed double digits. Investors have fretted about AI disruption and slowing growth. The “SaaSpocalypse” narrative has weighed on the stock. But Salesforce fought back hard after its July earnings report. Shares jumped more than 20% in a single day. That was the biggest pop since 2020. The rally shows how quickly sentiment can flip when results impress.
Turning to valuation, Salesforce trades at roughly 22 times trailing earnings. That is below the industry average of 22 times. It is also way below the peer average of nearly 35 times. On a price-to-sales basis, CRM sits at 4.3 times. The industry average is over 9 times. So Salesforce is not expensive. It is fairly valued with a slight discount. That gives patient investors a margin of safety.
 www.barchart.com
Braze Adds a Real-Time Marketing Layer
Braze focuses on customer engagement that dynamically responds to action as it occurs through apps, websites, email, text message, and more. While Salesforce already has a wide range of marketing applications, Braze introduces real-time customer journeys that could fit in Salesforce's data and Agentforce AI tools.
The proposition on the pitch is elementary: AI agents become more valuable when they respond to new customer signals instead of predetermined campaigns or outdated information. Salesforce states that the blend could enable marketing to be even more intertwined with commerce, sales, and service. About 2,770 customers use Braze, with fiscal 2027 revenue projected to be $910 million to $913 million. The price is not downbeat, as it is about 6.2 times that forecast, but there will be some work ahead for Salesforce to convince people that cross-selling and integration can create value.
The transaction is anticipated to close in Salesforce’s fiscal year 2028, after consulting shareholders and regulatory authorities. The result of the acquisition won't be apparent immediately, as management has stated that the anticipated forecast for fiscal 2027 won't be adjusted.
Strong Results Support the AI Argument
Investors have reasons to consider Salesforce beyond the debate regarding whether AI will change the way businesses build traditional software solutions. For Q2, revenue rose 11% YoY to $11.35 billion, which included $10.8 billion in subscription and support revenue.
Profits improved even more. Adjusted earnings per share rose 103% to $5.90 from a year ago. Agentforce and Data 360's ARR stayed at $3.9 billion, which increased by over 210% annually. The growth shows Salesforce is starting to develop a substantial business regarding putting in place AI services.
Furthermore, management increased its forecast for fiscal 2027 revenue to $46.1 billion to $46.4 billion. The revised outlook boosts the confidence of investors in the company's short-term growth prospects, albeit without a definitive resolution of the uncertainty surrounding the longer-term effects of AI on software subscriptions.
The spiriting of the “SaaSpocalypse” narrative seems unnecessarily alarmist to Benioff, the CEO, who has derided worries regarding AI stifling software firms as overblown. However, Salesforce has to prove that customers are willing to pay for its AI offerings and that it can generate continued profits from them. That performance is going to be pivotal for investors.
Wall Street Sees Upside for CRM Stock
Analysts are generally bullish on the CRM company.
In mid-October, Bank of America upgraded Salesforce, raising its price target to $285 and changing its rating from “Underperform” to “Buy.” AI could “increase reliance” on these enterprise platforms, which contain compliance systems, workflows, and business information, said Tal Liani, an analyst.
Since the Braze announcement, Cantor Fitzgerald has upgraded its rating and price target on the shares to “Overweight” and $300, respectively.
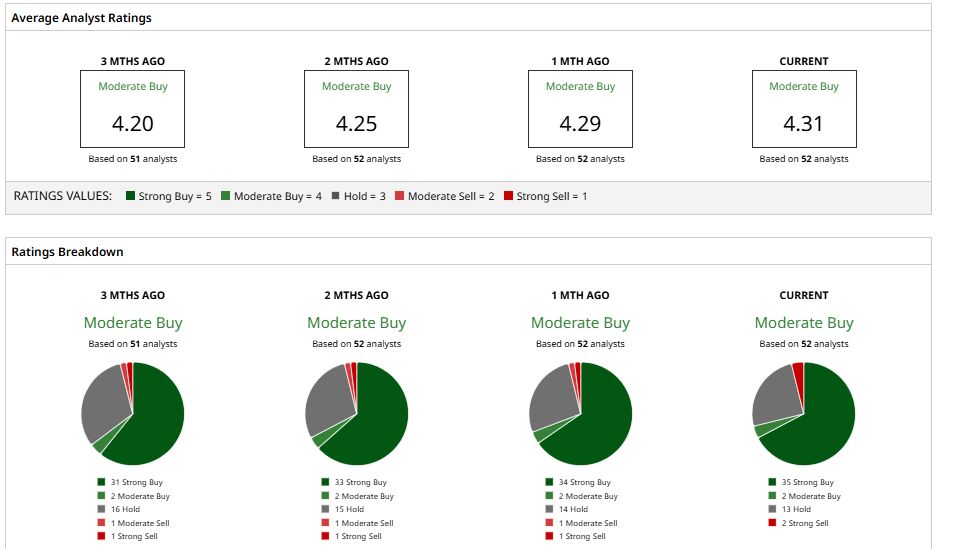
Analysts have projected an average price target of $285.74 for the stock and a consensus “Moderate Buy” rating. Dragging the long bow for that one, roughly 15% upside over the current equity price.
In short, the contract reinforces Salesforce's AI-marketing narrative, but the investment case is not clinched by itself. Patient investors might find this more attractive if the acquisition is used for the company to support long-term growth as they play out the AI revolution instead of just the acquisition buzz.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.