

Alphabet’s (GOOG) (GOOGL) third-quarter results showed slower growth in Google Search, raising concerns about the company’s ability to justify its heavy spending on AI and other infrastructure.
Google Services revenue grew 15% year-over-year (YoY) to $94.5 billion in the second quarter, with Google Search and other revenue increasing 17%. In the third quarter, Google Services revenue growth slowed to 11%, while Google Search and other revenue grew 12%.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
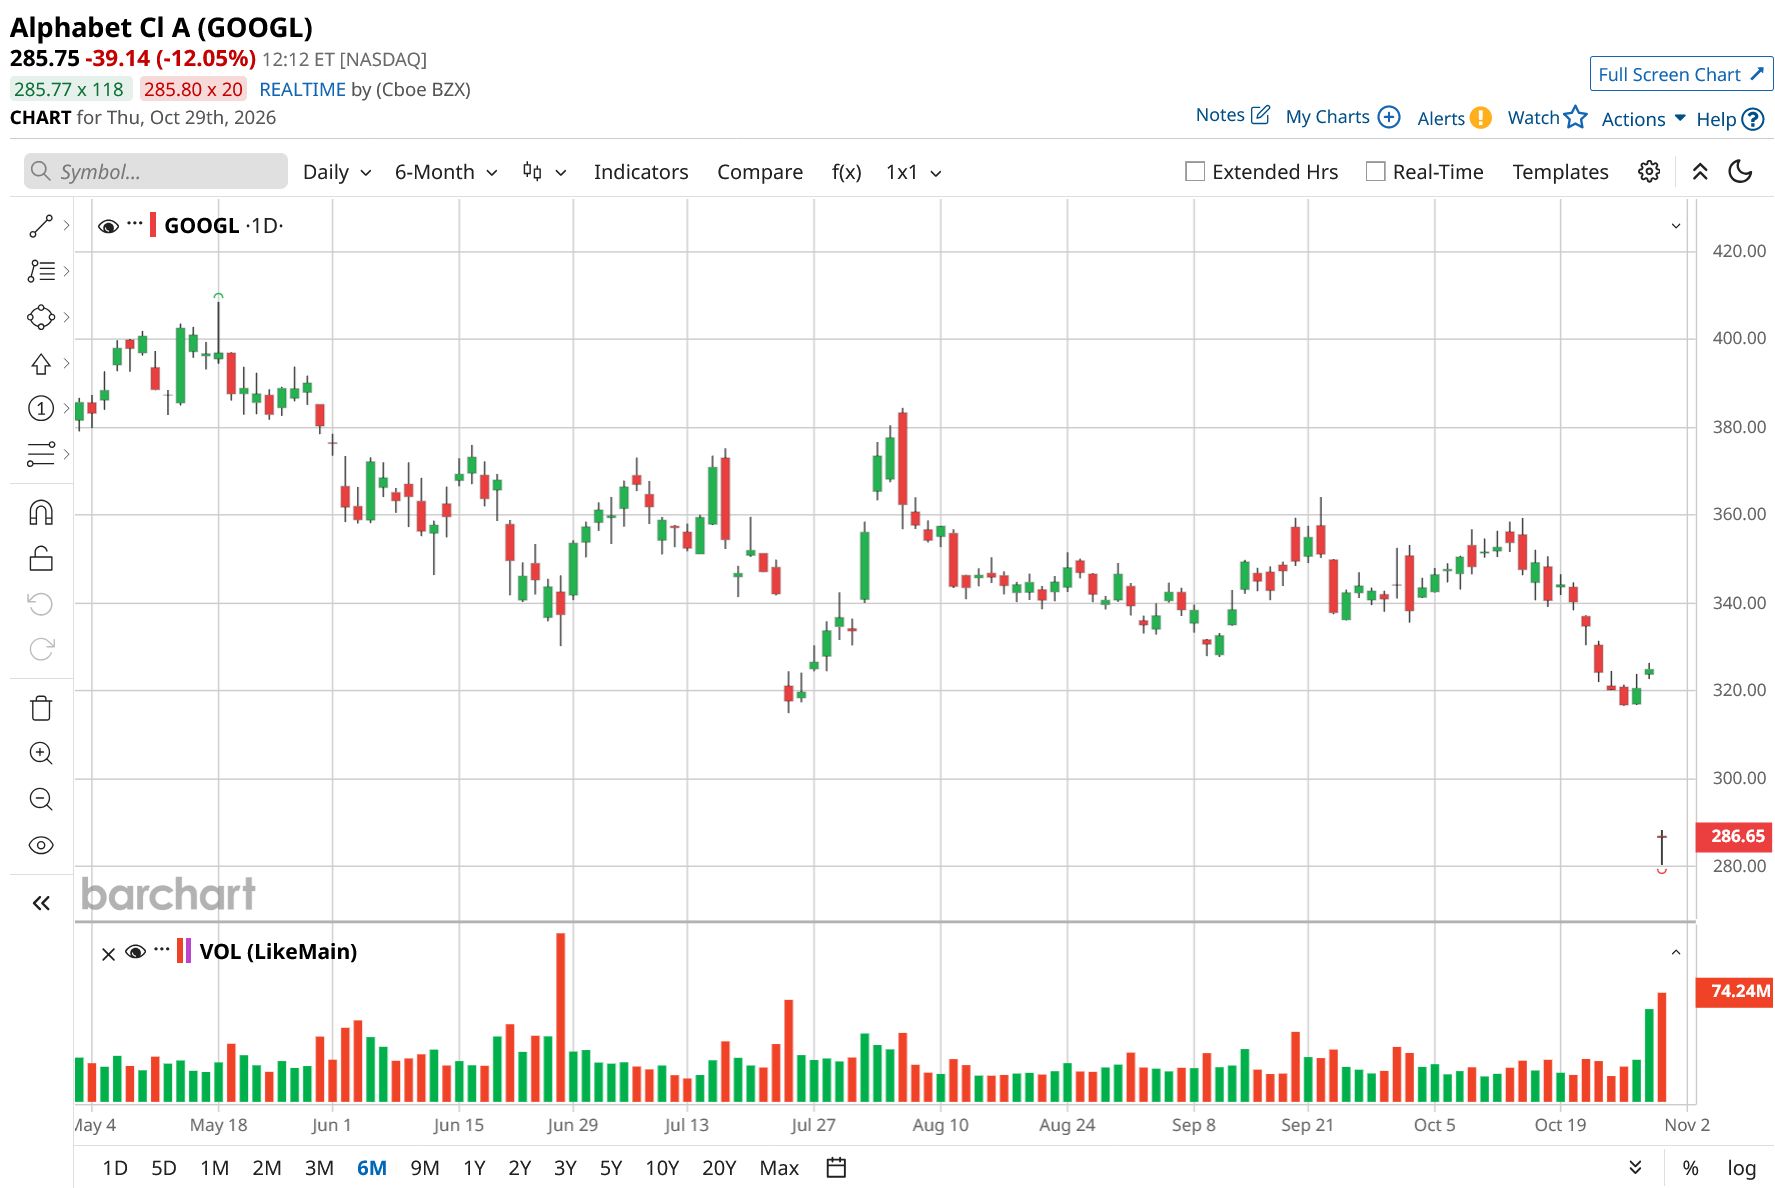
The slowdown disappointed investors, sending GOOGL shares down about 12% during today's morning trading. However, the weaker growth numbers don’t necessarily mean that Google’s core business is losing momentum.
One important factor to consider is the YoY comparison. During its second-quarter earnings call, Alphabet’s management noted that Search growth had accelerated starting in the third quarter of the previous year. As a result, Google faces tougher YoY comparisons in the following quarters, making it harder to maintain the same growth rates.
Despite the moderation in growth rate, there are still reasons to remain optimistic about GOOGL stock. Here are two factors that make Alphabet an attractive investment opportunity.
 www.barchart.com
Cloud Revenue Is Soaring
Although Alphabet’s third-quarter growth fell short of expectations, the tech giant maintained strong growth, with revenue up 25% YoY. Sustained double-digit growth in recent quarters highlights the resilience of its core businesses, with soaring Google Cloud growth emerging as a key catalyst.
Accelerating demand for cloud infrastructure and artificial intelligence (AI) services is strengthening the business. Google Cloud delivered exceptional third-quarter performance, with revenue surging 103% YoY to $30.7 billion, up from 82% growth in the preceding quarter. The acceleration indicates strong demand for Alphabet’s cloud offerings, especially as enterprises expand investments in AI infrastructure and cloud computing.
A key competitive advantage is Alphabet’s integrated AI ecosystem, which combines proprietary chips, AI models, data infrastructure, security solutions, and agent-based platforms. By offering these capabilities through a unified platform, Alphabet can address a broader range of enterprise requirements and increase customer adoption.
The company’s diversified product portfolio further strengthens its business, with 18 Google Cloud product lines each generating over $1 billion in annual revenue. During the quarter, growth was driven by both AI-related services and its core Google Cloud Platform (GCP) business. Sales of Tensor Processing Units (TPUs), Alphabet’s proprietary AI accelerators, also contributed meaningfully to the third-quarter results.
Besides driving the company’s top line, the segment also contributes significantly to its bottom line. The segment’s operating income more than tripled YoY to $11.1 billion, while the operating margin increased from 23.7% in the prior-year quarter to 36.2%.
Looking ahead, Google Cloud’s strong backlog of $561 billion points to solid growth. Alphabet expects to recognize slightly more than 55% of this amount as revenue over the following 24 months. Moreover, strong demand for its AI-related services and core GCP offerings points to continued growth. Management also expects TPU system sales to continue scaling in the fourth quarter, followed by a more substantial revenue ramp in 2027.
Overall, Google Cloud is one of Alphabet’s most important growth drivers. With the segment’s revenue accelerating, profitability remaining strong, and TPU system sales expected to scale further, the business will likely sustain solid momentum, supporting GOOGL stock.
Alphabet Stock’s Valuation Appears Attractive
Alphabet is well-positioned to deliver solid growth ahead. At the same time, its stock appears attractively valued. Trading at around 15.6 times forward earnings, the stock looks reasonably priced compared with its large-cap technology peers.
By comparison, Microsoft (MSFT) trades at 26.7 times forward earnings, while Amazon (AMZN) commands a multiple of approximately 32.9.
Alphabet’s lower forward price-to-earnings (P/E) ratio, soaring Cloud revenues, growing subscription revenue, and resilience in the Search business make its risk-reward profile compelling.
GOOGL Stock: Cloud Growth and Valuation Support the Bull Case
With Cloud revenue accelerating, profitability improving, and Search continuing to generate substantial revenue, Alphabet appears well-positioned to sustain growth despite tougher comparisons.
Trading at a discount to several large-cap technology peers, the stock offers an attractive risk-reward near the current levels.
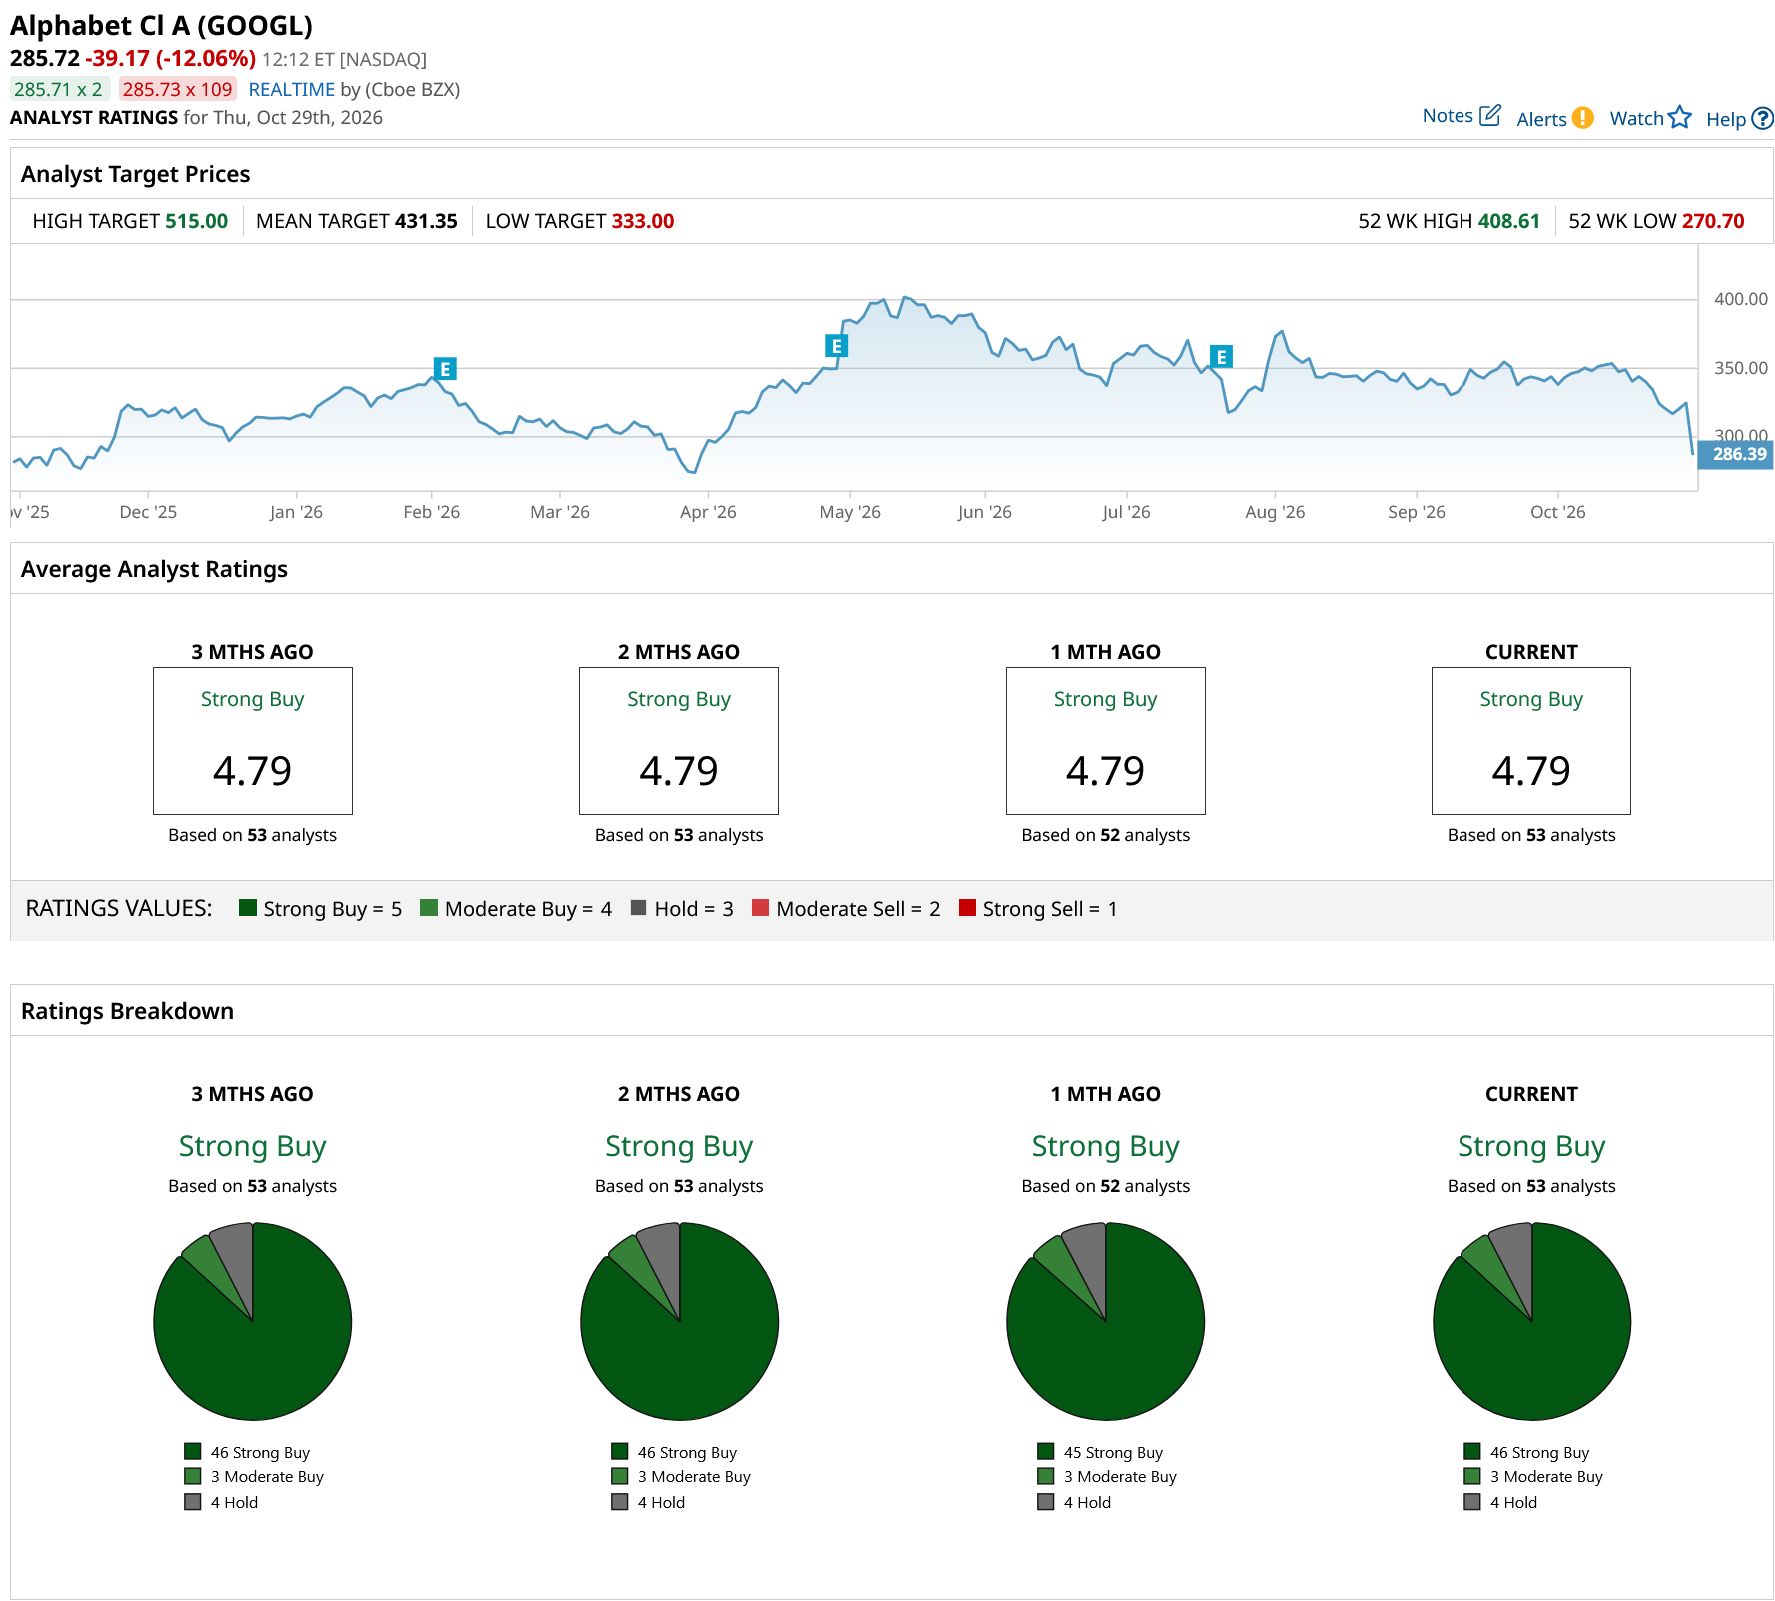
Wall Street remains bullish on GOOGL stock, with consensus ratings pointing to a “Strong Buy.”
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Mizuho Is Sweetening on CrowdStrike Stock Thanks to the Guardian Launch Ahead of Chevron Earnings, Here's What Barchart Data Says Comes Next for CVX Stock Don’t Panic Over Search Slowdown: 2 Reasons Why GOOGL Stock Still Looks Attractive AMD Stock Outlook: AMD's Meta Deal Boosts AI Growth Prospects