

Today’s commentary on Wednesday’s unusual options activity centers on Canadian cannabis producer Cronos Group (CRON), Anheuser-Busch InBev (BUD), and Altria Group (MO). The cigarette maker owns a stake in both CRON and BUD.
Why this trio?
Can’t Get Enough Options?: Join the list for Barchart’s daily unusual options report, delivered free.
A few days earlier, I happened to read a press release from Cronos that announced the completion of its acquisition of CanAdelaar B.V., the largest of the 10 licensed producers involved in the Netherlands’ Weitexperiment (weed experiment), the country’s adult-use cannabis pilot project at 69 licensed coffee shops in 10 Dutch municipalities other than Amsterdam.
It’s been a long time since I’ve considered anything cannabis-related, but this news piqued my interest.
At a purchase price of 57.5 million euros ($64.0 million) plus contingent payments in 2026 and 2027, the Ontario-based company, whose cannabis brands include Spinach, Peace Naturals, and Lord Jones, gains entry into the European adult-use market at a relatively inexpensive investment.
While it's tempting to invest directly in Cronos Group stock, CRON is up 37% over the past year but well below its Nov. 8, 2021, five-year high of $6.79; I love finding lower-risk backdoor ways to invest.
That points directly to Altria Group. Yesterday, MO had three unusually active options, all calls, all expiring in the next 30 days.
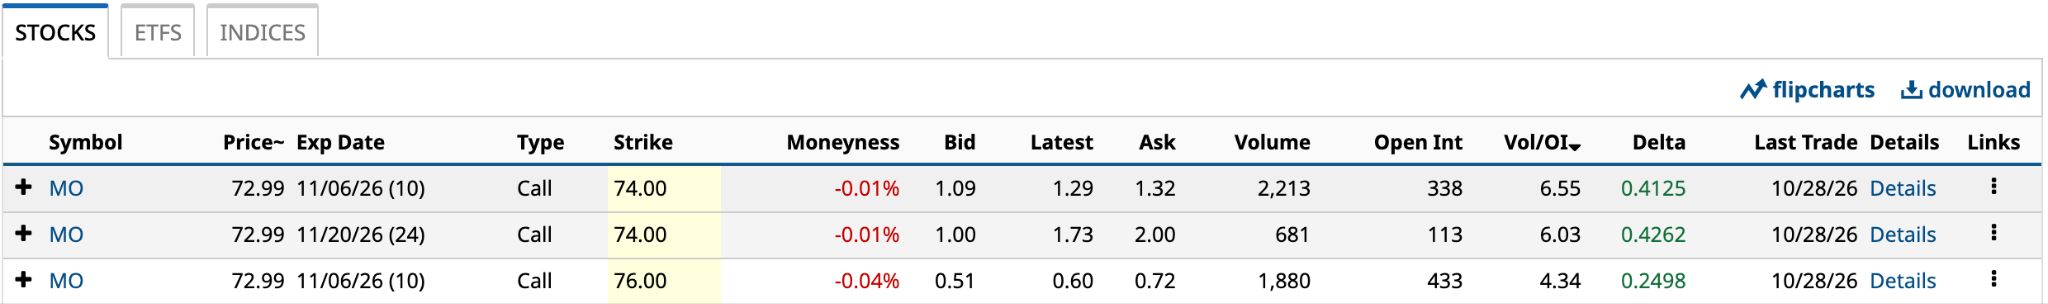
I’ll consider how I can use one or more of these to make a side-door bet on CRON, and to a lesser extent, BUD.
What Makes CRON Interesting Other Than the CanAdelaar Acquisition?
Most investors know cannabis investments have been a black hole of losses for several years. At one point, cannabis ETFs were all the rage. The largest, AdvisorShares Pure US Cannabis ETF (MSOS) traded as high as $55.91 in February 2021. It’s still the largest, with net assets of $751 million, but well below the $1 billion-plus in 2021.
Cronos is not one of MSOS’ holdings because it is Canadian. It is, however, the second-largest holding of the oldest cannabis ETF, Amplify Alternative Harvest ETF (MJ), with a 12.03% weighting. You could buy MJ if you’re feeling more optimistic about the industry. That’s a subject for another day.
Two reasons compel me to reconsider Cronos stock.
First, the business is in the best financial position of its entire history. In the past five years, its revenue has more than doubled to $147 million in 2025 from $65 million in 2021. More importantly, it has reduced its EBIT (earnings before interest and taxes) from a $166 million loss in 2021 to a $17 million EBIT loss in 2025, and is on the verge of generating a 12-month EBIT profit.
Second, in July 2025, it bought CAD$30 million ($21.5 million) in junior secured convertible notes from Canadian cannabis retailer High Tide (HITI) for CAD$25.2 million ($18.0 million), a 16% discount, and paid 4% annual interest.
The notes included the right to convert the $25.2 million in notes into shares at an exercise price of CAD$4.20 ($3.00). It also received a five-year warrant to buy up to 3.84 million shares of High Tide at an exercise price of CAD$3.91 ($2.80 per share).
High Tide’s retail business, which includes 228 Canna Cabana locations across five provinces and one in Germany, is also improving, like Cronos, with annual GAAP profits likely in the next 12-18 months.
Lastly, Altria, the maker of Marlboro cigarettes, owns 42.5% of Cronos. It invested CAD$2.4 billion ($1.8 billion) in the company way back in December 2018. That gave it a 45% stake. It did not exercise the warrants it received to buy an additional 84.2 million shares.
The carrying value of its stake on its books had fallen to $314 million by the end of 2025. At the end of September, the carrying value was $323 million. Today, those shares are worth $527.7 million, or about 30% of its original investment. Ironically, Cronos’ current market cap equals Altria’s 2018 investment in the company.
The Backdoor Cronos Buy
The risk of investing in Cronos stock remains high. The business isn't guaranteed to keep strengthening. I believe it will, but it’s not a slam dunk. Buying CRON is not for risk-averse investors.
However, if you buy 100 shares of MO at $75.60, the share price as I write this on Thursday around midday, you get paid $111 every three months (5.9% yield) to wait for good things to happen at Cronos.
Furthermore, and this only applies to people who don’t mind owning cigarette stocks, you own shares in a company that generates $9.1 billion in annual free cash flow. Despite Altria’s $143 billion enterprise value and a 31% share price gain in 2026, it still has a very attractive free cash flow yield of 6.3%. I consider anything at 8% or higher to be value territory.
Lastly, it also owns 8.1% of Anheuser-Busch InBev, which it carries on its books at $9.0 billion, 28% less than the current value of $12.44 billion. Effectively, that adds $3 billion in cash to its balance sheet.
So, let’s get back to Altria’s three unusually active call options from yesterday.
All three are OTM (out-of-the-money), with strikes between 1% and 4%. You could do a Bull Call Spread by buying the Nov. 6 $74 call for $1.32 and selling the Nov. 6 $76 call for $0.51 in premium and a net debit of $0.81. That translates to a maximum profit and loss of $1.19 [$76 strike price - $74 strike price - $0.81 net debit] and $0.81, respectively, a risk/reward ratio of 1.47 to 1, and a profit probability of 60%, which is quite good.
However, I’m more interested in using calls to own MO stock. So, I’ll focus on the Nov. 20 $74 call.
The cash-secured call strategy--which is really just buying a long call--involves buying 1 Nov. 20 $74 call for $2.00 and setting aside cash to buy 100 shares. Essentially, on Nov. 20, you either exercise your right to buy 100 shares at $74, which is effectively $76 [$74 strike + $2.00 call cost], or, if the share price is less than $74, you let it expire worthless and buy 100 shares at the current share price.
So, the expected move by the Nov. 20 expiration date is 3.87%, up or down. If MO falls by the expected move of 3.87%, the share price would be $70.12 at expiration. Including the $2 cost of the call, your effective purchase price would be $72.12, below where it currently trades.
The downside is that 24 days isn’t enough time. You’d be better off buying an OTM call 90 to 180 days to expiration, where time decay is lower, and you have more time to decide what to do with the call. However, the premium would be considerably higher.
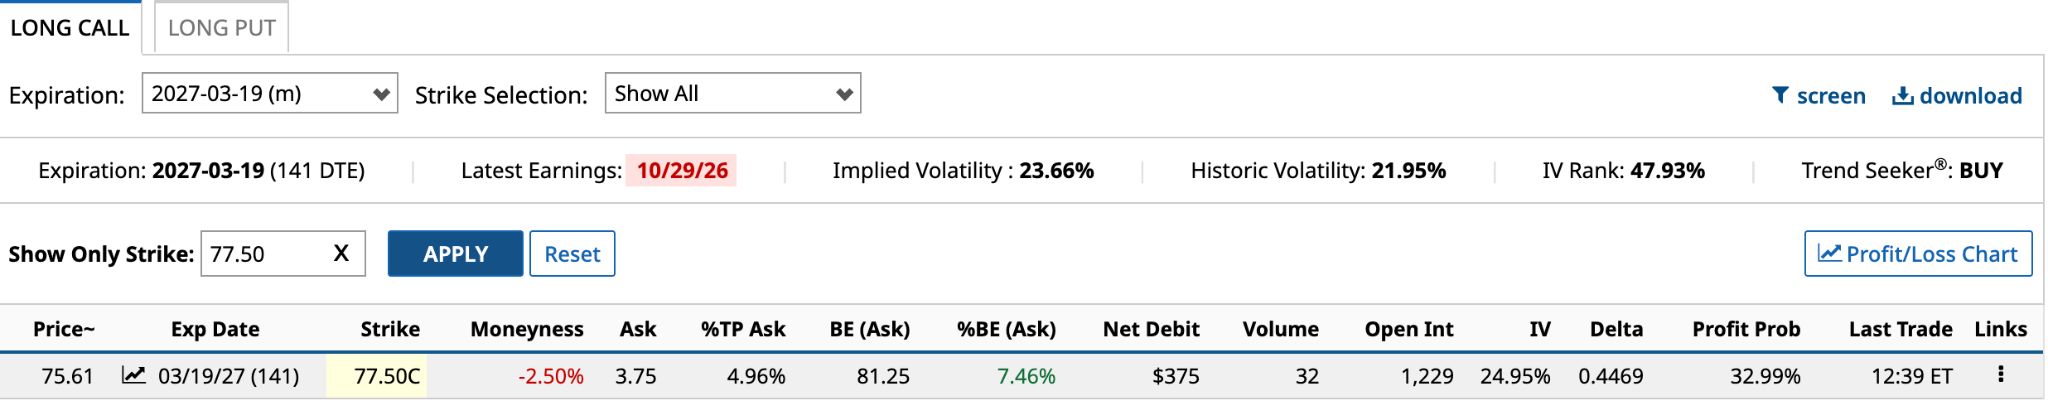
Here’s what the March 19/2027 $77.50 call looks like based on today’s higher share price. It’s not too bad, just $1.75 higher, with a 141-DTE compared to 24 days for the Nov. 20 $74 call. The higher cost is worth it.
On the date of publication, Will Ashworth did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.