

Texas Pacific Land Corporation (TPL), headquartered in Dallas, Texas, owns and manages tracts of land and resource, and water services and operations businesses in Texas. Valued at $19.9 billion by market cap, the company’s income is derived from land sales, oil and gas royalties, grazing leases, and interest.
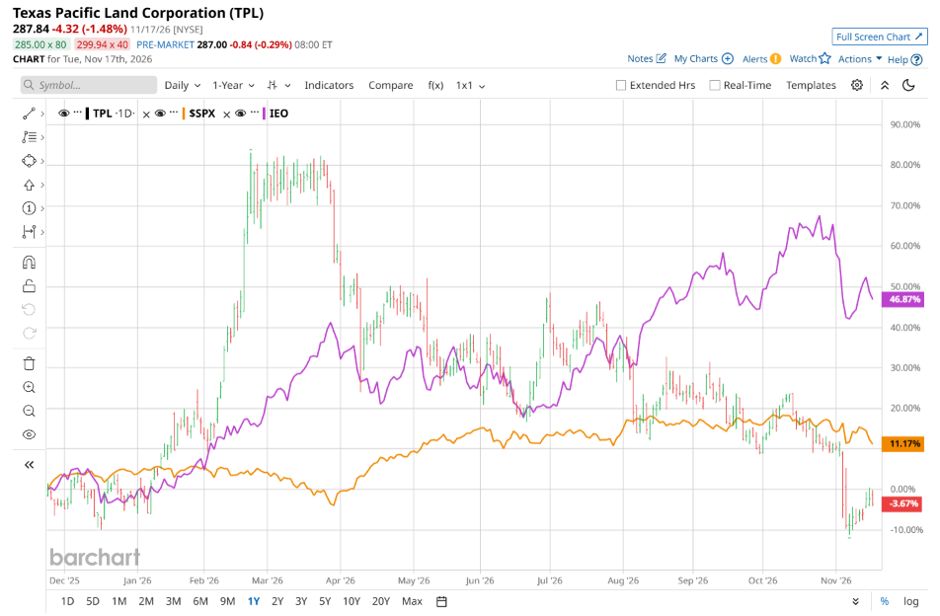
Shares of this leading owner of oil and gas surface acreage and subsurface mineral interests have underperformed the broader market over the past year. TPL has declined 9.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10%. In 2026, TPL stock is up marginally, compared to the SPX’s 7.2% rise on a YTD basis.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
Narrowing the focus, TPL’s underperformance is also apparent compared to the iShares U.S. Oil & Gas Exploration & Production ETF (IEO). The exchange-traded fund has gained about 44.6% over the past year. Moreover, the ETF’s 50.3% returns on a YTD basis outshine the stock’s marginal gains over the same time frame.
 www.barchart.com
TPL’s underperformance, sliding sharply from its early-2026 peak to near 52-week lows despite consecutive quarters of record revenue, oil and gas royalty production, and produced-water volumes, stems primarily from valuation compression and mounting regulatory uncertainty around its AI data center diversification thesis. Bolstering its fundamental strength, the company posted Q3 revenue of $273.4 million, beating analyst estimates of $261.6 million and an EPS of $2.42, marking a 4.2% beat. However, having traded at a steep premium well above historical and industry earnings multiples, the stock faced multiple contraction as investors reassessed high-multiple energy names amid crude oil volatility and unhedged commodity exposure. This pullback accelerated sharply following Democratic gains in the Texas midterm elections, most notably the gubernatorial upset by Gina Hinojosa, who campaigned on a moratorium for state data center construction, which cast doubt over permitting timelines and delayed major hyperscale agreements across TPL’s West Texas acreage.
For the current fiscal year, ending in December, analysts expect TPL’s EPS to grow 27.4% to $8.88 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last three quarters.
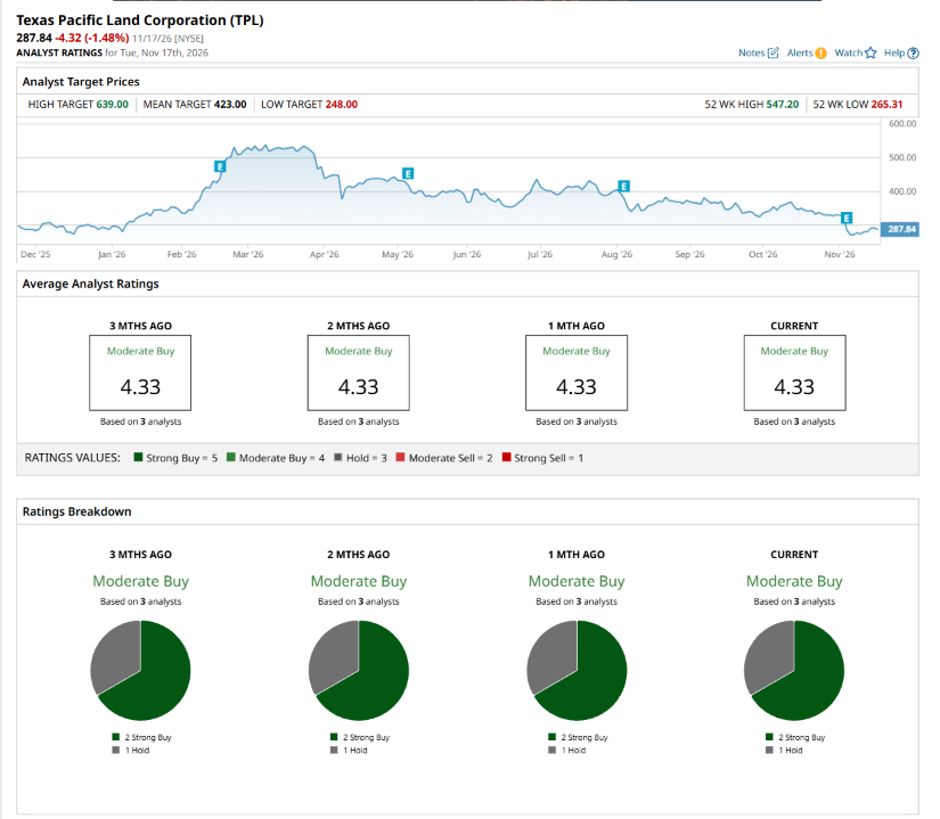
Among the three analysts covering TPL stock, the consensus is a “Moderate Buy.” That’s based on two “Strong Buy” ratings, and one “Hold.”
 www.barchart.com
The configuration has been consistent over the past three months.
On Jun. 3, Tim Rezvan from KeyBanc maintained a “Buy” rating on TPL, with a price target of $639, the Street-high price target, implying an ambitious potential upside of 122% from current levels.
The mean price target of $423 represents a 47% premium to TPL’s current price levels.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play OKLO Stock as Oklo Secures Key Fuel Supply for Its Ohio Plant Fermi Stock Drops After Q3 Results: How a $200M Hyperscaler Deal Could Drive a Recovery Sugar Prices Face Seasonal Headwinds: Will Energy Markets Add More Selling Pressure? Could Last Friday's Events Have Ripple Effects for This Week's Markets?