

When a big hedge fund exits a position, headlines scream. Investors panic. But smart investors react differently and dig deeper.
Whale Rock Capital Management just sold its entire stake in Western Digital (WDC). That is a fact. But is it a warning sign or is it a gift wrapped in fear? I think it is the latter. WDC is not a broken business. It is a cash-generating machine riding an AI storage boom that most people still underestimate.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Although the stock has been volatile, the fundamentals tell a very different story than the price action suggests.
Why WDC Stock Got Hit This Year
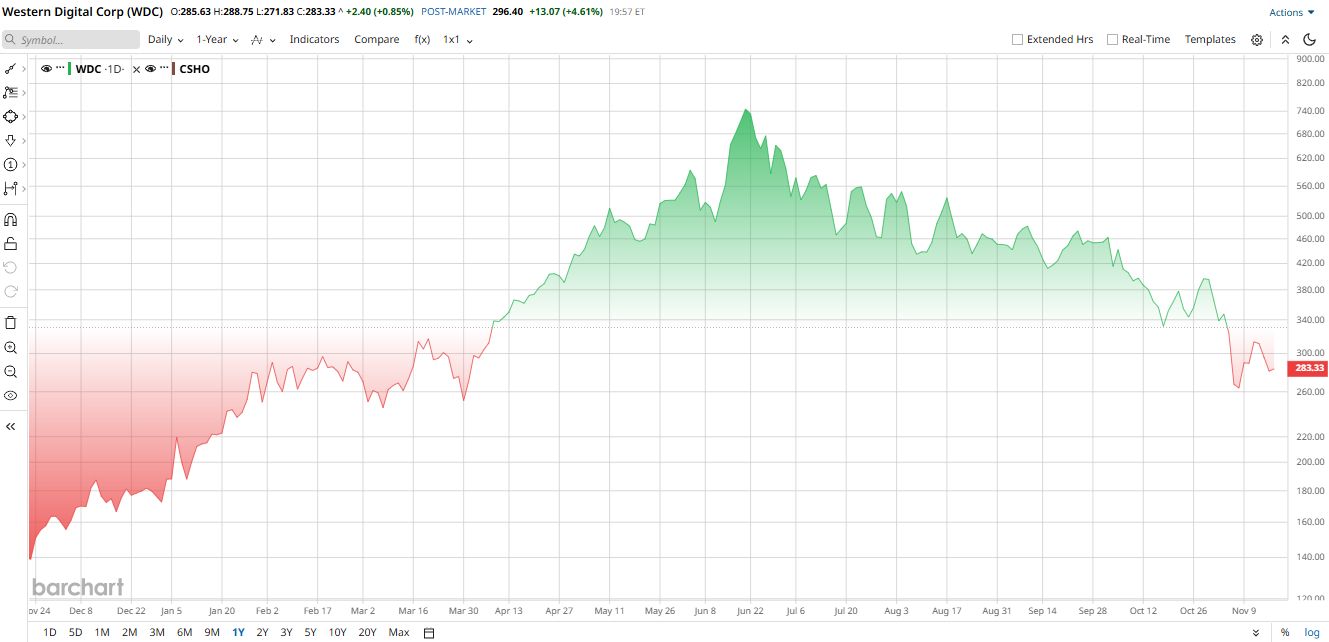
Western Digital stock is down roughly 37% over the past three months, yet up more than 67% year to date. It hit a 52-week high of $799.80 and has since fallen to around $283. That is a painful drop. But the reasons are not about the business breaking. Instead, the AI trade got crowded. Then it got scared. Fears about data center spending slammed storage names. WDC got caught in the blast. The market repriced WDC on fears, not facts. The business did not slow down. It accelerated.
But the numbers tell a different story. WDC is trading at a steep discount. The forward P/E is 12, much lower than the sector's 26, signaling the stock trades at a substantial discount compared to peers. The forward PEG ratio is just 0.15, compared to the sector’s 1.05, making WDC appear extremely undervalued for its growth profile.
 www.barchart.com
What Whale Rock’s Exit Really Means
Whale Rock sold its WDC stake, that is true, but hedge funds rotate. They take profits. They reposition. It’s not always negative news for a company.
Whale Rock also dumped Apple (AAPL) and Astera Labs (ALAB) in the same quarter. This is a portfolio decision, not a verdict on Western Digital’s future.
Here is what matters more: WDC management is buying its own stock. The company repurchased $1 billion worth of shares in fiscal Q1 2027 at an average price near $500 per share. And it still has $2.26 billion left in its buyback authorization. If management deploys that cash at today’s lower prices, they can retire a lot more shares. Whale Rock sold. WDC is buying. I know which signal I trust more.
The Quarter That Proves the Business Is Thriving
Western Digital reported fiscal Q1 2027 results on October 22. The numbers were indeed ahead of analysts’ expectations.
Revenue hit $4.38 billion, up 55% year over year. Net income came in at $1.779 billion, up 54% year over year. Free cash flow was a monster $1.38 billion. That is 31% of revenue turning into cold, hard cash.
The major growth driver was Cloud, which is its engine, making up roughly 88% of sales. Customers are buying more capacity at higher prices. That is the dream setup for any storage company.
CEO Irving on the earnings call said fiscal 2027 is off to a strong start with results exceeding expectations driven by robust customer demand and disciplined execution.
The guidance is even better. For fiscal Q2 2027, management expects revenue of $5.1 billion at the midpoint, up 66% to 72% year over year. Non-GAAP EPS is guided to $5.80. Analysts are modeling full-year EPS of $23.62, up 141% from last year.
The business is not slowing down. It is speeding up. Management is not sitting still. They are returning capital to shareholders, paying down debt, and investing in capacity to meet surging demand.
The company also recently announced plans to expand manufacturing for high-capacity drives. That is exactly what the AI storage boom needs. More data means more storage. Western Digital sells the picks and shovels for that pile.
What Wall Street Analysts Are Saying About WDC Stock
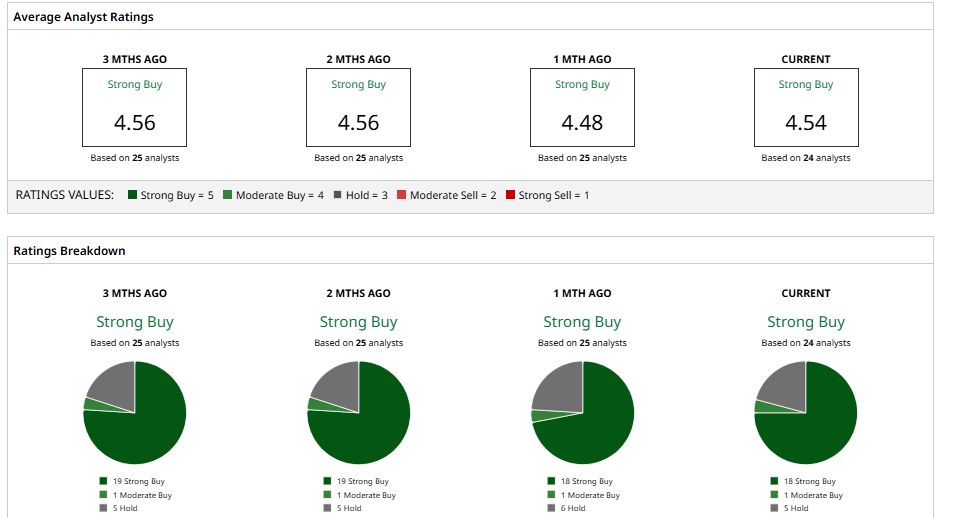
Wall Street is not running for the exits. Analysts see the sell-off as a potential buying opportunity here.
The Consensus rating is a “Strong Buy.” Barchart data shows the average price forecast of $614.96. That means that the upside is almost 113% off current prices. The street high target of $1050 presents an even more breathtaking 264% upside.
However, some analysts are still cautious. TD Cowen has cut its price forecast down from $540 to $430, but still rates the stock a buy. Analyst Krish Sankar referred to elevated capex and demand strength. Not too long ago, Bernstein listed WDC among the greatest misvalued stocks in the sell-off of AI firms.
Whale Rock sold. That is noise. The signal is the company is earning lots of free cash flow and is growing by 55%. Artificial intelligence-based storage is really here. Unfortunately, data is not going away. It is piling up.
The stock is highly volatile. It will swing. However, preparations are happening in the business. I am with the buyers. Not the sellers.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nvidia Without Jensen Huang: Strong Growth and Attractive Valuation Sustain the Bull Case Whale Rock Dumps Western Digital. Buy the AI Storage Dip for 113% Upside. Nvidia’s Board Shuts the Door on the Huang Comeback Trump Was Rooting For Why AMD Stock Could Hit $662 in 2027