

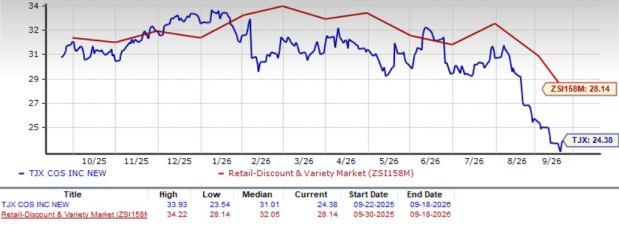
The TJX Companies, Inc. TJX is trading at a modest discount to the Zacks Retail - Discount Stores industry, offering investors a potential blend of growth and value. The stock’s forward 12-month price-to-earnings (P/E) ratio stands at 24.38, below the industry average of 28.14.
TJX P/E Ratio (Forward 12 Months)
Image Source: Zacks Investment Research
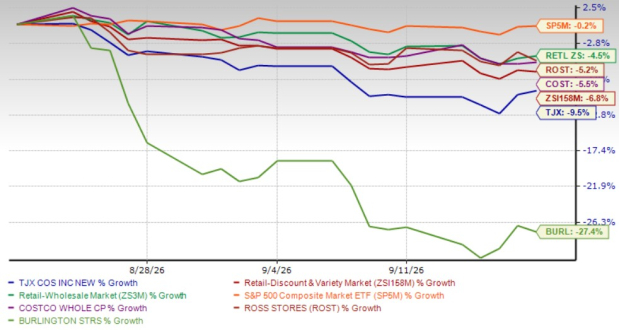
TJX also presents a balanced valuation compared with peers Costco Wholesale Corporation COST, Ross Stores, Inc. ROST and Burlington Stores, Inc. BURL. TJX trades at a discount to Costco and Ross Stores, which carry forward P/E multiples of 39.59X and 25.61X, respectively, while commanding a premium to Burlington’s 17.8X. This valuation positions TJX between its higher-multiple peers and lower-valued off-price rival, reflecting a combination of consistent execution and a resilient business model.
Despite its relatively attractive valuation, TJX's shares have declined over the past month. During this period, The TJX Companies stock has fallen 9.5%, compared with declines of 6.8% for the industry, 4.5% for the Zacks Retail and Wholesale sector and 0.2% for the broader S&P 500. Among peers, TJX posted a steeper decline than Costco and Ross Stores, which fell 5.5% and 5.2%, respectively, but held up considerably better than Burlington, which dropped 27.4%.
TJX Stock Past Month Performance
Image Source: Zacks Investment Research
TJX’s valuation and recent stock performance provide useful context for investors assessing the stock. A closer look at the company’s fundamentals offers further insight into its underlying prospects.
What’s Supporting TJX’s Business Momentum?
TJX’s diversified off-price model remains a key fundamental strength, supported by broad-based demand across its retail banners. In the second quarter of fiscal 2027, consolidated comparable sales rose 4%, driven by higher customer transactions and average basket size. HomeGoods, TJX Canada and TJX International delivered strong comparable sales growth of 7%, 6% and 7%, respectively, helping offset softer growth at Marmaxx.
Merchandising capabilities and product availability also remain central to TJX’s competitive positioning. Management noted that branded merchandise availability continues to be outstanding, supported by a global sourcing network spanning roughly 21,000 vendors and more than 1,400 buyers. This scale gives TJX flexibility to source differentiated assortments, refresh merchandise frequently and respond to changing consumer preferences across income and age groups.
TJX is also expanding its long-term growth runway through a larger store-development opportunity. The company raised the global store potential by 500 locations to 7,500 stores across its existing banners and countries and plans to accelerate annual store growth to 4% beginning in fiscal 2028. TJX ended the fiscal second quarter with 5,285 stores, indicating substantial room for further expansion.
How Are Estimates Stacking Up for TJX?
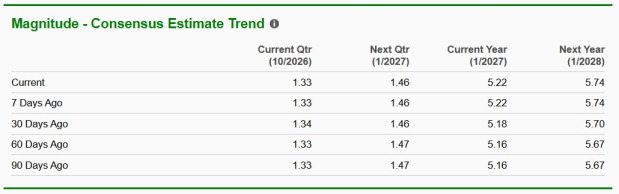
Reflecting the positive sentiment around TJX, the Zacks Consensus Estimate for earnings per share has seen upward revisions. Over the past 30 days, earnings per share estimates for fiscal 2027 and 2028 have increased 4 cents each to $5.22 and $5.74, respectively. Based on the revised estimates, TJX is expected to deliver earnings growth of 10.4% in fiscal 2027 and 9.9% in fiscal 2028.
Image Source: Zacks Investment Research
The TJX Companies Navigates Key Challenges Ahead
Despite TJX’s solid operating fundamentals, rising costs remain a near-term concern. Adjusted SG&A expenses increased 20 basis points year over year to 19.7% of sales, largely due to higher store wage and payroll costs. Looking ahead, higher fuel and freight costs remain margin headwinds, with fiscal third-quarter adjusted gross margin projected to decline 40-50 basis points year over year.
Tariff and foreign-currency uncertainty also remains a key risk. While TJX has benefited from tariff refunds, the timing and extent of any additional recoveries remain uncertain. Meanwhile, currency movements reduced fiscal second-quarter reported sales growth 1 percentage point, highlighting the potential volatility associated with TJX’s international operations.
TJX’s Investment Analysis
TJX’s reasonable valuation, resilient off-price model and solid comparable-sales performance support its investment case. Strong merchandise availability, an extensive sourcing network and a sizable store-expansion runway add to its longer-term prospects, while upward earnings estimate revisions provide further support. However, rising labor, fuel and freight costs, along with tariff and currency uncertainties, could weigh on near-term performance. Given this balance of strengths and risks, the stock appears more suited to holding than aggressive buying. TJX currently carries a Zacks Rank #3 (Hold).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The TJX Companies, Inc. (TJX): Free Stock Analysis Report
Costco Wholesale Corporation (COST): Free Stock Analysis Report
Ross Stores, Inc. (ROST): Free Stock Analysis Report
Burlington Stores, Inc. (BURL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).