

Opendoor Technologies Inc. OPEN expects the fourth-quarter 2026 contribution margin to exceed the third-quarter level, supported by improving acquisition economics and progress in clearing legacy inventory. This could reverse its historical pattern, as the fourth-quarter contribution margin has been lower than the third-quarter level every year since the company went public.
The company delivered a contribution margin of 5.8% in the second quarter, within its targeted 5-7% range. Homes listed for more than 120 days accounted for 9% of inventory, while margins on recently acquired homes were performing in line with expectations. Approximately 100 homes acquired under the earlier operating model remained, with most expected to sell during the third quarter. Completing these sales would reduce a lingering source of margin pressure ahead of the fourth quarter.
The improvement also comes as Opendoor expands acquisition activity. Second-quarter acquisition contracts reached 6,908, up from 5,136 in the first quarter. Stronger seller conversion at comparable spread levels has supported this growth without requiring the company to pay above fair value for homes. This pricing discipline is important to the margin outlook, as Opendoor seeks to increase transaction volumes while maintaining healthier unit economics.
Near-term seasonality could weigh on performance. OPEN expects the third-quarter contribution margin of approximately 4-4.5%, down from 5.8% in the second quarter, with Doma integration likely adding a temporary drag. However, the implied sequential decline of 130-180 basis points is smaller than its historical second-to-third-quarter average of 470 basis points, excluding 2023. The outlook points to a more moderate seasonal decline before the anticipated fourth-quarter recovery.
For Opendoor, the next phase of the margin recovery depends on maintaining margins on recently acquired homes and completing the expected legacy inventory sales. If healthier acquisition economics hold as volumes expand, OPEN could reverse its historical fourth-quarter decline and provide stronger evidence of the operating progress under Opendoor 2.0.
Peer Comparisons: Offerpad & Zillow
Offerpad Solutions Inc. OPAD provides a close comparison to OPEN because its margin recovery also depends on clearing aged inventory and accelerating home sales. Second-quarter contribution profit after interest reached $13,500 per real estate transaction, up from $5,500 in the first quarter. Fewer than 10 aged homes remained, while non-aged homes sold during the second quarter took approximately 82 days to sell, ahead of its 100-120-day target. Offerpad expects further improvement in contribution profit after interest per transaction during the second half, supported by healthier inventory and a greater mix of fee-based services.
Zillow Group, Inc. ZG offers a different perspective on margin expansion, with cost discipline and improving mortgage economics supporting profitability. In the second quarter of 2026, adjusted EBITDA reached $176 million, representing a 23% margin, while third-quarter guidance implies an adjusted EBITDA margin of approximately 25% at the midpoint. Zillow expects approximately $75 million in annualized adjusted EBITDA cost savings relative to its second-quarter expense run rate. Zillow Home Loans also has positive per-loan economics after accounting for fixed and variable costs, and the company expects year-over-year adjusted EBITDA margin expansion in the fourth quarter.
OPEN’s Stock Price Performance, Valuation & Estimates
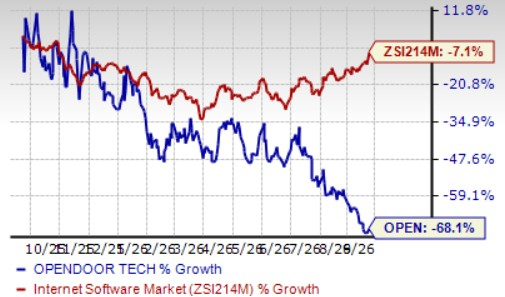
Shares of Opendoor have declined 68.1% in the past year compared with the industry’s 7.1% fall.
OPEN One-Year Price Performance
Image Source: Zacks Investment Research
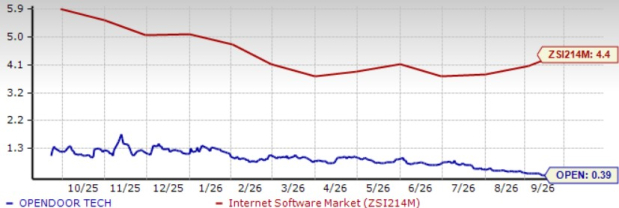
From a valuation standpoint, OPEN trades at a forward price-to-sales (P/S) multiple of 0.39, significantly below the industry’s average of 4.4.
OPEN’s P/S Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
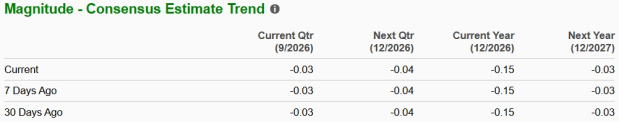
The Zacks Consensus Estimate for OPEN's 2026 loss per share suggests a 42.3% year-over-year improvement. Loss per share estimates for 2026 have remained unchanged in the past 30 days.
EPS Trend of OPEN Stock
Image Source: Zacks Investment Research
OPEN stock currently has a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Opendoor Technologies Inc. (OPEN): Free Stock Analysis Report
Zillow Group, Inc. (ZG): Free Stock Analysis Report
Offerpad Solutions Inc. (OPAD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).