

Somnigroup International Inc. SGI is strengthening its growth strategy by leveraging its vertically integrated business model, investing in product innovation, consumer-focused marketing, omnichannel capabilities and operational efficiencies. The company is focused on expanding its market reach while improving profitability through synergies, productivity and disciplined capital allocation. In the second quarter of 2026, Somnigroup generated sales of $1.8 billion, while adjusted operating margins benefited from synergies and operational efficiencies.
Innovation remains a key component of Somnigroup’s growth strategy. The company is refreshing its product portfolio to address evolving consumer preferences and strengthen its premium positioning. Consumer engagement and marketing are also important growth priorities. SGI is investing in advertising and targeted digital media while strengthening its direct-to-consumer and retail channels.
Mattress Firm continues to refine its marketing strategy and store experience, supported by technology investments, product training and its sleep-expert selling model. The company is also progressing with its store refresh and brand-wall programs, which are intended to improve the in-store shopping experience and support sales. Somnigroup continues to expand its vertically integrated retail presence internationally through businesses such as Dreams and its Tempur-Pedic retail stores.
Operational efficiency is another important pillar of the company’s strategy. Somnigroup is realizing cost and sales synergies from the Mattress Firm integration while pursuing productivity improvements across its operations. In the second quarter, the company generated about $15 million in cost synergies and sales synergies from a larger share of Tempur Sealy products at Mattress Firm also contributed to the performance. The company is additionally pursuing logistics consolidation, real estate optimization and other efficiency initiatives.
Overall, Somnigroup is focused on building a more integrated and commercially effective bedding platform by combining strong brands, product innovation, consumer-focused marketing, retail scale and vertical integration. Mattress Firm remains an important growth and synergy opportunity, while Tempur-Pedic and Sealy continue to benefit from brand strength and product innovation. International operations provide additional avenues for expansion, while the Leggett & Platt combination is expected to broaden Somnigroup’s capabilities and create additional sourcing, operational and product-development opportunities.
SGI’s Price Performance, Valuation and Estimates
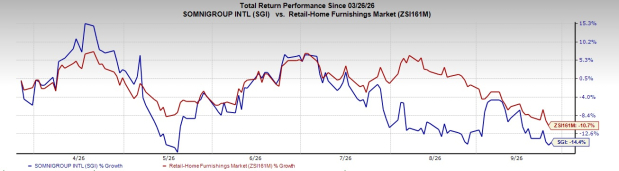
Somnigroup shares have lost 14.4% in the past six months compared with the industry’s 10.7% decline.
Image Source: Zacks Investment Research
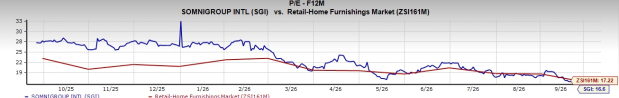
From a valuation standpoint, SGI trades at a forward price-to-earnings ratio of 16.6X compared with the industry’s average of 17.22X.
Image Source: Zacks Investment Research
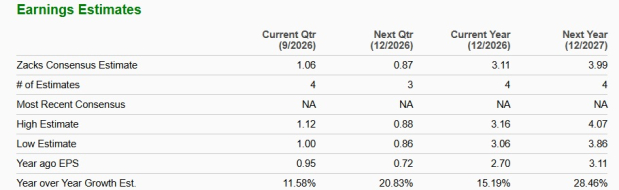
The Zacks Consensus Estimate for SGI’s 2026 and 2027 earnings per share (EPS) indicates year-over-year growth of 15.2% and 28.5%, respectively. The company’s EPS estimate for fiscal 2026 and 2027 has increased in the past 30 days.
Image Source: Zacks Investment Research
Somnigroup currently carries a Zacks Rank #3 (Hold).
Key Picks in the Retail Space
FIGS, Inc. FIGS is an apparel company focused on the healthcare industry. Its offerings include lab coats, jackets, footwear, bags, socks and other accessories used by healthcare professionals. The company carries a Zacks Rank #2 (Buy) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for FIGS’ current financial-year earnings and sales suggests growth of 89.5% and 18.2%, respectively, from the year-ago actuals. FIGS delivered a trailing four-quarter average earnings surprise of 201.8%.
Boot Barn Holdings, Inc. BOOT is the largest lifestyle retailer in the United States, specializing in western and work-related footwear, apparel and accessories. The company also carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Boot Barn’s current fiscal-year earnings and sales suggests growth of 22.6% and 15.7%, respectively, from the year-ago actuals. BOOT delivered a trailing four-quarter average earnings surprise of 11.4%.
Fossil Group, Inc. FOSL is involved in designing, marketing and distributing consumer fashion accessories. It also carries a Zacks Rank #2.
The Zacks Consensus Estimate for Fossil Group’s current fiscal-year earnings suggests growth of 96.7% from the year-ago actuals. FOSL delivered an earnings surprise of 55.2% in the last reported quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Somnigroup International Inc. (SGI): Free Stock Analysis Report
Boot Barn Holdings, Inc. (BOOT): Free Stock Analysis Report
Fossil Group, Inc. (FOSL): Free Stock Analysis Report
FIGS, Inc. (FIGS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).