

National Energy Services Reunited Corp. NESR is pairing faster earnings growth with expanding contract visibility across the Middle East and North Africa. The operating picture has strengthened quickly, led by Jafurah, Kuwait awards and better cost absorption.
The counterweight is valuation. NESR now trades well above its own five-year sales multiple median, leaving less room for execution setbacks even as earnings and estimate momentum remain favorable.
NESR’s Earnings Growth Is Gathering Pace
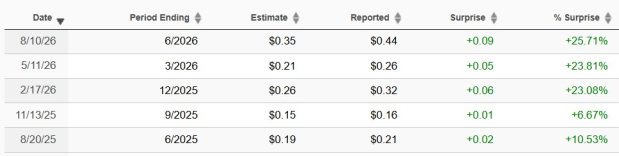
Second-quarter adjusted earnings rose 109.5% year over year to 44 cents per share and beat the Zacks Consensus Estimate by 25.7%. Revenues increased 59.1% to $520.8 million, while adjusted EBITDA reached a record $106.2 million.
Profitability also improved with scale. Cost of services declined to 84.4% of revenues from 86.6% a year earlier, while the adjusted EBITDA margin reached 20.4% despite incremental logistics costs tied to regional disruption.
National Energy Has a Visible Growth Runway
Jafurah remains the central growth engine, with four hydraulic fracturing fleets active throughout the second quarter. Multi-year Kuwait awards totaling $300 million add another layer of contract visibility, while management now views $2 billion as the minimum 2026 revenue objective.
The broader 3B3 strategy targets a $3 billion revenue run rate through a larger contract funnel, expansion in anchor markets and technology commercialization. For industry context, SLB SLB reported a 13% sequential decline in Middle East revenues in the second quarter amid conflict-related disruptions, while Halliburton Company HAL said Middle East/Asia revenues fell 2% sequentially. Those results underscore that regional growth opportunities still carry execution and geopolitical risk.
NESR’s Balance Sheet Adds Flexibility
Net debt fell to $99.6 million at the end of the second quarter from $185.3 million at 2025 year-end. Net leverage declined to 0.3X adjusted EBITDA, giving the company more room to fund equipment, technology and contract mobilization.
Management targets leverage at or below 1.0X and has said a zero-net-debt position within two years is realistic. NESR also plans to initiate a quarterly dividend in the fourth quarter of 2026 while maintaining its $50 million share-repurchase program.
National Energy’s Valuation Raises the Bar
NESR trades at 1.3X forward 12-month sales, above the Zacks sub-industry multiple of 1.2X. The stock also stands well above its own five-year median of 0.7X, although the historical range has extended as high as 1.6X.
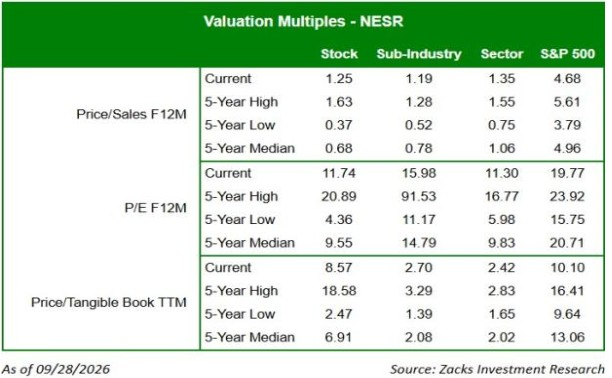
That premium is easier to defend if Jafurah, Kuwait and technology-led growth continue translating into higher earnings and cash flow. At the same time, the richer multiple increases sensitivity to slower utilization, margin pressure, working-capital timing or contract execution shortfalls.
NESR’s Fundamental Scores Support the Debate
NESR’s current setup combines favorable earnings momentum with a valuation that is no longer near its historical norm. The growth case remains supported by accelerating results, visible contract opportunities and a low-leverage balance sheet, but the stock now demands sustained execution to support its expanded multiple.
The stock currently carries a Zacks Rank #1 (Strong Buy). It also has a Growth Score of A, Momentum Score of A and VGM Score of A, alongside a Value Score of B. The combination points to favorable growth and momentum characteristics, with value still scoring well despite the stock’s richer sales multiple. That mix keeps the investment case constructive without removing the higher expectations embedded in the current valuation. You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
National Energy Services Reunited (NESR): Free Stock Analysis Report
SLB Limited (SLB): Free Stock Analysis Report
Halliburton Company (HAL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).