

McCormick & Company, Incorporated MKC delivered a solid third-quarter fiscal 2026 performance, benefiting from the McCormick de Mexico acquisition, organic sales growth and improved profitability.
Adjusted earnings of 86 cents per share rose 1.2% year over year and beat the Zacks Consensus Estimate of 75 cents. Net sales increased 17.4% to $2,024.8 million, surpassing the consensus mark of $1,979 million. Organic sales grew 1.9%, while adjusted gross margin expanded 180 basis points.
McCormick & Company, Incorporated Price, Consensus and EPS Surprise
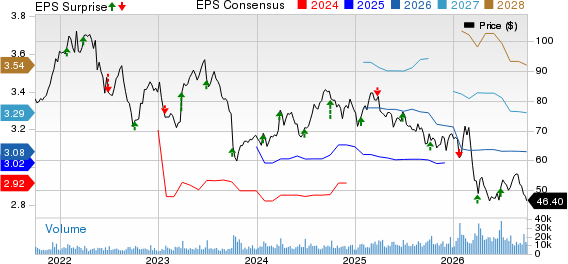
McCormick & Company, Incorporated price-consensus-eps-surprise-chart | McCormick & Company, Incorporated Quote
MKC's Top Line Gets Acquisition Support
McCormick's reported sales growth included a 14.6% contribution from the McCormick de Mexico acquisition and a 0.9% favorable currency impact. On a constant-currency basis, net sales advanced 16.5%.
Organic sales growth reflected a 2.2% contribution from pricing, partly offset by a 0.3% decline in volume and product mix. Management noted improving trends in Consumer Americas, while demand remained softer among certain CPG and quick-service restaurant customers in Flavor Solutions.
McCormick's Margin Expansion Supports Profit
Adjusted gross profit was $794.9 million in the quarter, up 23% year over year. Adjusted gross margin expanded 180 basis points to 39.3%, aided by McCormick de Mexico accretion, higher sales and savings from the Comprehensive Continuous Improvement program. Higher commodity and freight costs partly offset these benefits.
Adjusted operating income increased 22.1% year over year to $358.5 million, including a 1.2% favorable currency impact. On a constant-currency basis, adjusted operating income rose 20.9%. The increase reflected higher gross profit and productivity savings, partly offset by higher selling, general and administrative expenses related to acquisitions, brand marketing and technology investments.
MKC's Segment Results Show Broad-Based Growth
Consumer segment sales increased 24.9% year over year to $1,215 million. McCormick de Mexico contributed 23.2% to growth, while organic sales increased 1.1%. Pricing rose 2.2%, more than offsetting a 1.1% decline in volume and product mix. Consumer-adjusted operating income advanced 24.4% to $241 million.
Flavor Solutions sales climbed 7.7% to $809 million, including a 3.4% acquisition contribution. Organic sales grew 3%, supported by a 2.2% increase in pricing and 0.8% growth in volume and mix. Adjusted operating income rose 17.6% to $117 million. Asia-Pacific was a notable growth area, with organic sales increasing 8.3%, supported by new product launches and limited-time offers with QSR customers.
McCormick's Cash Flow Strengthens
Net cash provided by operating activities totaled $598.8 million for the first nine months of fiscal 2026 compared with $420.2 million in the prior-year period. The company paid $387 million in dividends and spent $131.2 million on capital expenditures.
McCormick ended the quarter with cash and cash equivalents of $331.1 million. Long-term debt stood at $2,906.1 million, while short-term borrowings and the current portion of long-term debt totaled $2,112.1 million. Management reported a quarter-end leverage ratio of approximately 2.9 times and expects to continue reducing debt ahead of the proposed Unilever Foods combination.
MKC Reaffirms Fiscal 2026 Outlook
McCormick reaffirmed its fiscal 2026 net sales growth outlook of 13-17%, including an expected 11-13% contribution from McCormick de Mexico. Organic sales are projected to grow 1-3% on a constant-currency basis. Management now expects organic growth to land between the low end and midpoint of that range.
Adjusted operating income is still projected to increase 16-20%, while adjusted earnings are anticipated between $3.05 and $3.13 per share, representing growth of 2-5%. Management expects adjusted operating income growth and adjusted earnings to finish around the midpoint of their respective ranges.
McCormick Sees Higher Costs in the Fourth Quarter
The company continues to expect adjusted gross margin expansion of 100-120 basis points for fiscal 2026 and now anticipates reaching the high end of the range. This comes despite management raising its cost inflation expectation to 6-7% from the prior mid-single-digit forecast.
For the fourth quarter, McCormick expects rising commodity and freight expenses, along with increased commercial investments in Consumer Americas, to pressure gross margin. A packaging-material supply constraint could also reduce total company fourth-quarter volume growth by up to one percentage point and is expected to affect full-year organic growth by about 30 basis points.
The Zacks Rank #4 (Sell) stock has tumbled 31.9% year to date compared with the industry’s decline of 6.5%.
Stocks to Consider
Mondelez International, Inc. MDLZ, a global snacking company, currently carries a Zacks Rank #2 (Buy). MDLZ delivered a trailing four-quarter earnings surprise of 5.8%, on average. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for Mondelez’s current fiscal-year sales and earnings per share (EPS) implies growth of 3.7% and 4.5%, respectively, from the year-ago figures.
Mama's Creations, Inc. MAMA, a prepared-foods company focused on fresh, ready-to-eat and deli products, currently carries a Zacks Rank of 2. MAMA delivered a trailing four-quarter surprise of 121.7%, on average.
The Zacks Consensus Estimate for Mama's Creations’ current fiscal-year sales and EPS indicates respective increases of 30.3% and 66.7% from the year-ago period.
Laird Superfood, Inc. LSF, a consumer product company that develops, manufactures and markets plant-based, natural and functional food and beverage products, currently carries a Zacks Rank #2. LSF delivered an earnings surprise of 100% in the last reported quarter.
The Zacks Consensus Estimate for Laird Superfood’s current fiscal-year sales and EPS calls for growth of 188.2% and 104%, respectively, from the year-ago figures.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
McCormick & Company, Incorporated (MKC): Free Stock Analysis Report
Mondelez International, Inc. (MDLZ): Free Stock Analysis Report
Laird Superfood, Inc. (LSF): Free Stock Analysis Report
Mama's Creations, Inc. (MAMA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).